Between Grip And Growth
- By Gaurav Nandi
- September 10, 2026
Britain’s tyre industry has entered 2026 with unexpected momentum driven by a sharp rebound in replacement demand and a growing wave of electric vehicles entering their first tyre replacement cycle. But beneath the stronger sales lies an industry confronting profound structural challenges. From the rapid rise of low-cost Asian imports and persistently high energy costs to the erosion of domestic manufacturing capacity and shortcomings in end-of-life tyre management, the sector is being forced to redefine its future. British Tyre Manufacturers’ Association Chief Executive Dareen Lindsey opined that while premium manufacturers have remained resilient, Britain’s long-term competitiveness will hinge on strengthening circularity, supporting remanufacturing, enforcing fair trade and adapting to a mobility landscape increasingly shaped by automation, electrification and connected transport.
Britain’s tyre industry entered 2026 on a stronger footing than many expected, buoyed by a sharp rebound in replacement tyre demand and an accelerating shift towards electric vehicles (EVs).
According to data by British Tyre Manufacturers’ Association (BTMA), the replacement tyre market has moved firmly into recovery, with the first half of 2026 pointing to the strongest replacement market performance in several years.
The recovery has been led by the following consumer categories: car tyre volumes rose by 24 percent, SUV fitments by 31 percent and light truck tyres by a striking 44 percent, lifting the combined consumer segment 27 percent above a weak first half last year.
Truck tyre volumes grew a more modest 2.5 percent in line with the gentle recovery in freight activity, while motorcycle and scooter volumes were broadly flat at a positive 1.6 percent. The smaller specialist categories moved against the trend, with agricultural volumes down 21 percent and earth mover down 9 percent.
Some of this headline growth reflects the downward restatement of the 2025 baseline and the unwinding of last year’s destocking, but even allowing for that, the underlying picture is one of genuine recovery in sell-in demand.
Despite the latest figures, BTMA Chief Executive Darren Lindsey told Tyre Trends that manufacturers face mounting pressure from low-cost Asian imports, stubbornly high domestic energy costs and a manufacturing landscape that continues to lose ground to overseas competitors.
“The industry’s immediate recovery should not distract policymakers from the structural issues reshaping Britain’s tyre market. While premium manufacturers have largely retained their position, value brands are being squeezed between an expanding budget segment and increasingly sophisticated global competition,” stated Lindsey.
At the same time, Britain’s long-term competitiveness will depend not only on defending domestic manufacturing but also on embracing remanufacturing, circularity and next-generation mobility technologies.
 “We had an exceptional year in 2025 from a sales perspective,” Lindsey said. “More encouragingly, 2026 has started even better.”
Part of that growth reflects a natural correction in the replacement market. Throughout much of 2025, distributors and dealers deliberately reduced inventory levels, particularly within the passenger car segment. That strategy could only continue for so long before replacement demand returned.
The result has been a significant recovery in purchasing activity.
“We’ve seen around 29 percent growth in passenger car tyres during the first quarter of 2026,” Lindsey said, adding that second-quarter figures are expected to confirm whether the momentum has continued.
EVs PUSHING MARKET
One of the biggest forces behind this recovery is Britain’s accelerating adoption of electric vehicles.
Government incentives have steadily increased EV ownership over recent years, with roughly one in every four new vehicles sold in UK now fully electric. Many of the remainder are plug-in hybrids, creating an expanding parc of electrified vehicles that is beginning to enter its first replacement tyre cycle.
“The vehicles sold three years ago are now reaching the point where owners need replacement tyres,” Lindsey explained.
For premium manufacturers, this has proven advantageous. Unlike traditional replacement buyers who may experiment with alternative brands, EV owners have generally opted to replace worn tyres with the same homologated products originally fitted by vehicle manufacturers.
Rather than developing entirely separate EV-specific product lines, manufacturers are increasingly redesigning their broader portfolios around higher load capacities.
“As a result, manufacturers are producing more extra-load tyres that can serve both conventional vehicles and EVs,” Lindsey said.
He sees no significant emergence of domestic companies entering the EV tyre market independently. Instead, established premium manufacturers continue to dominate this rapidly growing segment through their longstanding relationships with vehicle manufacturers and their ability to meet increasingly demanding performance standards.
HOURGLASS ECONOMICS
While premium manufacturers have demonstrated resilience, the wider market is undergoing profound structural change.
Lindsey describes the current landscape as an ‘hourglass’ market. At the top, premium brands remain relatively stable, supported by technological leadership, strong OE relationships and consumer confidence.
At the opposite end, budget tyres, primarily imported from Asia, continue gaining market share through aggressive pricing.
Caught in between are mid-tier value brands, which increasingly struggle to differentiate themselves.
“The premium segment remains relatively strong,” Lindsey said. “The middle-value brands are being squeezed, while the budget segment continues to grow.”
 This shift reflects changing consumer purchasing behaviour as much as global manufacturing economics.
Budget tyres have become increasingly attractive during a period of rising living costs, while premium manufacturers continue to compete on technology, safety, durability and whole-life performance.
The companies suffering most are those occupying the middle ground, where price competition has intensified but brand differentiation remains limited.
TRADE MEASURES
Trade remedies introduced against Chinese truck tyres were designed to counter alleged dumping and create fairer competitive conditions.
According to Lindsey, however, the measures have simply redirected manufacturing rather than reducing imports. “We’ve seen production move from China into countries such as Thailand and Vietnam,” he said.
Consequently, imports of truck tyres from both countries have risen sharply across Britain and continental Europe.
The challenge, he argues, lies less with the trade remedies authority than with the speed at which manufacturers relocate production.
Trade investigations frequently require 9 to 12 months to complete. By the time authorities conclude their investigations, production has often shifted again, making enforcement increasingly difficult.
“It isn’t necessarily a failure of the authorities,” Lindsey noted. “Production simply moves elsewhere before investigations conclude.”
This pattern is not unique to Britain.
Across Europe, manufacturers are experiencing similar market dynamics as Asian producers establish manufacturing capacity outside China while continuing to supply European markets, noted Lindsey.
COST DISADVANTAGE
Although Britain’s trade remedies authority remains actively engaged in investigating unfair trade practices, Lindsey believes the country’s greatest competitive disadvantage lies elsewhere.
“High industrial energy costs have become one of the defining challenges facing British manufacturing over the past decade. I genuinely believe high energy prices have been one of the biggest factors behind the decline of UK manufacturing,” Lindsey said.
Manufacturing costs in Britain can exceed those of some European competitors by more than one-third before comparisons are even made with Asia.
“Those cost disparities make it increasingly difficult to attract new investment or expand existing production facilities. The government has introduced various energy support mechanisms and incentives to help manufacturers, but accessing those programmes often requires navigating complex administrative processes,” he added.
Moreover, public funding remains finite. “It’s not just the tyre industry competing for support,” Lindsey observed. “Steel, ceramics and many other manufacturing sectors are facing exactly the same challenges.”
The situation is particularly stark within truck tyres. Britain no longer manufactures new truck tyres domestically, relying instead on retreading and remanufacturing operations.
Passenger car tyre production continues, but much of that output serves original equipment vehicle manufacturers operating within Britain, where local supply offers important logistical advantages.
Beyond those niches, Lindsey sees rebuilding lost manufacturing capacity as increasingly difficult. “Once manufacturing leaves, it doesn’t simply come back,” he warned.
GLARING ISSUES
If the UK tyre industry is navigating one immediate challenge, it is the relentless influx of low-cost imports. If it faces a longer-term test, however, it lies in how Britain manages millions of end-of-life tyres each year.
For Lindsey, this is one of the industry’s most pressing concerns and one where Britain still has considerable work to do. “It’s not something I’m particularly proud of when it comes to UK’s actions,” he admitted.
Around 70 percent of UK’s exported waste tyres have historically been shipped to India, where, according to Lindsey, a significant proportion ultimately enters illegal pyrolysis operations rather than environmentally compliant recycling facilities.
Nevertheless, he believes Britain has a responsibility to ensure its own waste does not contribute to unsafe or environmentally damaging practices overseas.
Working alongside Tyre Recovery Association, the BTMA has been engaging with UK’s Department for Environment, Food and Rural Affairs (Defra) and the Environment Agency to strengthen oversight of waste tyre exports while also maintaining close dialogue with Indian authorities.
Although new measures introduced during the previous year were intended to tighten controls, Lindsey said the early results have been disappointing.
One of the industry’s biggest concerns centres on the Annex VII documentation that accompanies every shipment of exported waste tyres. The paperwork is designed to record the intended destination of each shipment and should ultimately be signed and returned to UK authorities once the tyres arrive at legitimate recycling or recovery facilities.
In practice, however, the system is failing. According to Lindsey, fewer than 20 percent of Annex VII forms are returned.
That leaves authorities without confirmation that approximately 80 percent of exported shipments actually reached their declared destinations.
“We simply don’t know whether those tyres ended up at environmentally responsible facilities that protect both the environment and public health,” he said.
The BTMA believes improving traceability is essential not only to eliminate illegal disposal routes but also to restore confidence in Britain’s waste management system.
KEEPING VALUE AT HOME
Lindsey argued that Britain should focus less on exporting waste and more on creating domestic industries capable of extracting value from end-of-life tyres.
“The solutions should create UK jobs, support the circular economy, respect the environment and deliver better outcomes for the industry,” he said.
That philosophy underpins the BTMA’s growing emphasis on remanufacturing and retreading.
The association’s Remanufacturing Conference, held ahead of the Tyre Recovery Association’s September event, aims to examine why Britain’s truck tyre retreading sector has declined so dramatically.
Only one in four truck tyres in Britain is now remanufactured. A decade ago, the figure stood closer to one in every two. Lindsey believes the decline cannot be attributed to a single cause.
“Ultra-low-cost imported tyres have reduced the financial incentive to retread. Consumer behaviour has evolved. Distribution channels have changed. Government policies have yet to provide meaningful incentives, while the industry itself must also ask whether it has done enough to communicate the economic and environmental benefits of remanufacturing,” he stated.
Government procurement represents another missed opportunity. Britain operates one of the country’s largest publicly funded vehicle fleets, yet Lindsey questions whether those vehicles routinely use remanufactured tyres.
“The honest answer is they don’t know,” he said. “And if they don’t know, then they’re probably not.”
Several European countries have already incorporated remanufactured products into public procurement policies, requiring roughly 30–35 percent of certain purchases to consist of remanufactured goods.
Lindsey believes similar policies could significantly reduce Britain’s environmental footprint while supporting domestic industry.
BETTER ENFORCEMENT
The broader issue of imports extends beyond price alone. Lindsey accepts that many Asian manufacturers now produce technically advanced tyres in highly sophisticated facilities.
“There are some very good products entering Europe,” he acknowledged. The concern is ensuring that every imported tyre genuinely complies with the safety, durability and performance standards it claims to meet.
He believes stronger market surveillance is essential. “We’re absolutely in favour of competition,” Lindsey said. “But it has to be fair competition.”
Premium manufacturers operate under stringent regulatory obligations while investing heavily in research, development, testing and future legislation.
Newer manufacturers frequently benefit from those advances without carrying the same historical investment burden.
Raw material costs remain broadly similar across the industry. Natural rubber, synthetic materials and petroleum-derived inputs are available to everyone.
The real competitive differences increasingly stem from labour costs, energy costs and manufacturing scale.
In some instances, Lindsey argued, imported tyres appear to reach European markets at prices below what domestic manufacturers require simply to produce them.
Where that occurs, anti-dumping measures become a legitimate policy response, he believed. At the same time, consumers often judge tyres solely on purchase price rather than lifetime operating costs.
That is particularly significant in the truck tyre market, where durability, fuel efficiency and retreadability can dramatically reduce total operating costs over the life of the tyre.
Premium truck tyres are intentionally engineered for multiple lives through remanufacturing. Some lower-cost alternatives are not. “They consume all those raw materials and are simply discarded after their first life,” Lindsey said. “That isn’t a like-for-like comparison.”
The industry therefore carries its own responsibility to better educate customers about lifecycle value rather than initial purchase price alone.
MANUFACTURING GAP
Technology is transforming manufacturing just as rapidly as it is reshaping mobility. Lindsey acknowledged that many of today’s Asian tyre plants rank among the world’s most advanced industrial facilities.
Highly automated production lines, robotics, automated material handling systems and so-called ‘dark factories’ have significantly reduced manual labour while dramatically increasing production efficiency.
“If Europe had the opportunity to start again from scratch, we’d probably build very similar facilities,” he said.
The challenge is that European manufacturers continue operating substantial legacy production assets that cannot simply be abandoned overnight. Instead, the industry must modernise gradually while continuing to utilise previous investments.
Automation has unquestionably narrowed the manufacturing gap between premium manufacturers and emerging competitors. Whether it has closed the quality gap remains another matter.
Quality, Lindsey argued, can only be demonstrated through rigorous testing and consistent compliance with increasingly demanding regulations. Premium manufacturers also continue investing heavily in research, innovation and the development of future industry standards.
NEXT COURSE
Looking ahead, Lindsey believes the industry’s biggest transformation may have little to do with tyres themselves.
Instead, it concerns mobility. Future manufacturers will increasingly sell mobility solutions rather than standalone products.
“Consumers may gradually move away from vehicle ownership towards subscription-based transport services. In that environment, tyre purchasing decisions shift from individual motorists to fleet operators and mobility providers,” said Lindsey.
He added that premium service providers will naturally specify premium vehicles and premium tyres. Lower-cost mobility services will prioritise affordability. The tyre industry therefore becomes part of a broader mobility ecosystem rather than an isolated manufacturing sector.
Britain’s willingness to embrace emerging technologies also positions it at the forefront of autonomous transport. UK remains among the few countries permitting autonomous vehicle testing on public roads and Lindsey expects commercial vehicle platooning to become a reality within the foreseeable future.
“Rather than operating individual trucks with individual drivers, fleets may increasingly deploy connected convoys of 10, 15 or even 20 vehicles travelling together under coordinated autonomous control,” he stated.
For tyre manufacturers, that evolution represents opportunity rather than threat. “Highly automated transport systems will require intelligent, connected tyres capable of delivering consistently reliable performance under far more demanding operating conditions,” he noted.
Fleet operators, Lindsey believes, are unlikely to entrust those applications to unproven products.
Ultimately, Britain’s tyre industry stands at a crossroads. The market is recovering, electrification is creating new replacement opportunities and technological innovation continues to reshape manufacturing and mobility.
Yet those opportunities co-exist with structural challenges ranging from manufacturing competitiveness and energy costs to import pressures, circular economy obligations and global supply chain shifts.
Record-Breaking Pirelli P Zero Trofeo RS Developed For BMW M2, M3 and M4
- By TT News
- November 12, 2026
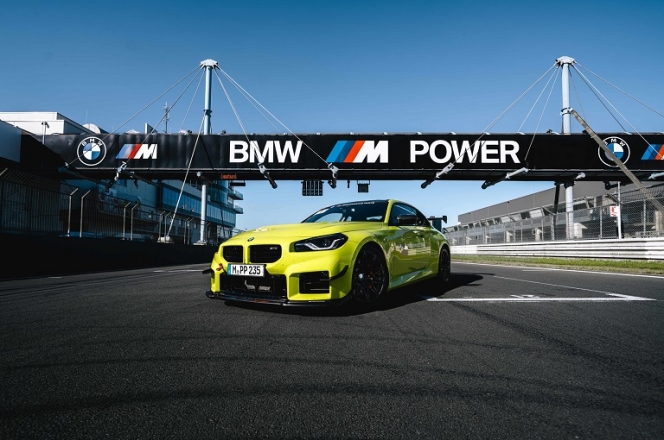
Pirelli has engineered a bespoke version of its P Zero Trofeo RS semi-slick tyre for three flagship BMW M models: the M2, M3 and M4. Developed in partnership with the German manufacturer, the road-legal track tyre is engineered to deliver safety and sporting performance, particularly dry grip, cornering stability and braking, along with consistent performance during track use.
The new fitment has powered two Nürburgring-Nordschleife records. The BMW M2 with M Performance Track Kit, which pairs street-legal driving with an optimised set-up for greater track-day precision, lapped in 7:25.068 minutes, beating the compact car record held by the M2 CS by 0.5 seconds. The BMW M3 CS Touring completed the circuit in 7:29.490, becoming the fastest Touring car ever around the legendary German track and beating the previous record by nearly six seconds. The Nordschleife also served as the main development venue for the tyre.
Close collaboration between Pirelli and BMW M's R&D teams underpinned the bespoke programme. Advanced virtual development techniques allowed the tyre's characteristics to be adapted to different requirements from the earliest project stages, in line with Pirelli's Perfect Fit approach of creating products tailored to each specific model or application. After the virtual phase, development moved to track testing at the Nardò circuit and the Nürburgring, where simulation-derived solutions were validated in real-world conditions.
All Pirelli fitments for the German high-performance car manufacturer carry BMW's star marking, confirming homologation and compliance with stringent performance and safety requirements. The new fitments strengthen a longstanding partnership now spanning more than 30 bespoke tyre projects across the P Zero family, from the latest-generation P Zero and the P Zero R to the P Zero Trofeo RS and P Zero Winter 2.
NEXEN TIRE Secures OE Supply For Hyundai’s All-New TUCSON
- By TT News
- November 12, 2026
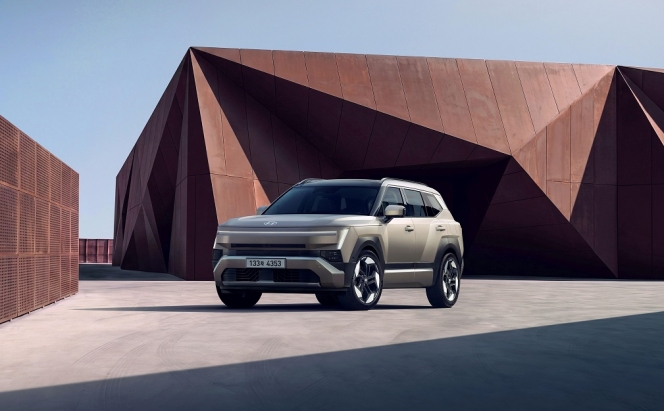
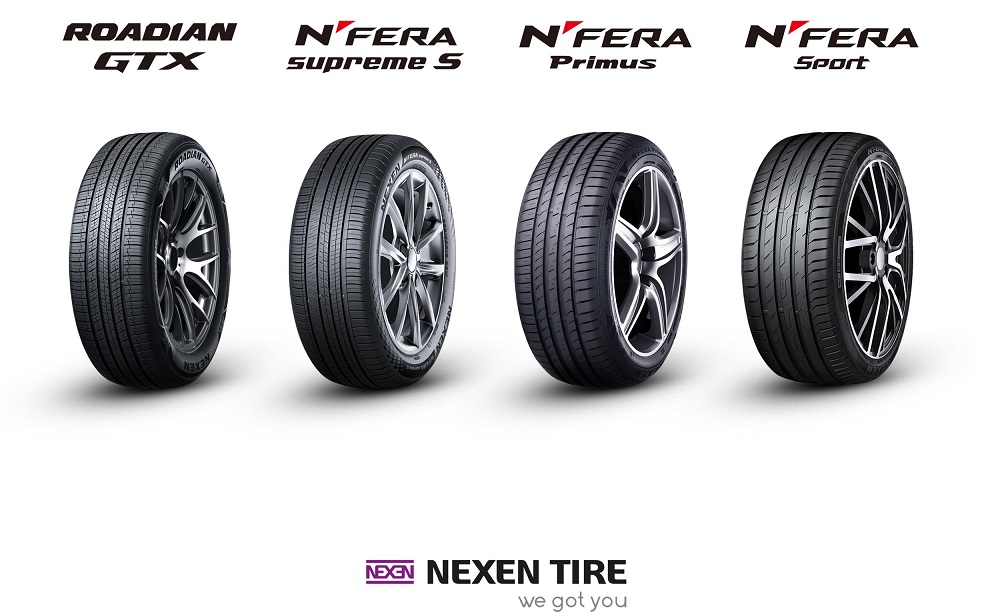
NEXEN TIRE will provide original equipment tyres for the all-new Hyundai TUCSON compact SUV, with the supply rolling out sequentially across Korea, North America and Europe. The company is fitting the Korean-market vehicles with the ROADIAN GTX in 17-inch sizes and the N'FERA Supreme S in 18-, 19- and 20-inch sizes.
North American deliveries are scheduled to start with internal combustion engine variants later this year, followed by hybrid models in the first quarter of next year, using the same product lineup as Korea. For Europe, the N'FERA Primus will be offered in 17- and 18-inch sizes and the N'FERA Sport in 19- and 20-inch sizes, with the selection tailored to local driving conditions.
The ROADIAN GTX, engineered specifically for SUVs, employs an advanced compound that sustains braking performance and ride comfort across a wide temperature range throughout the year. Its zigzag tread design distributes contact pressure to curb vehicle pulling, while improved tread life lengthens replacement intervals. The N'FERA Supreme S, a flagship tyre for high-performance premium vehicles, emphasises quietness and ride comfort. Using convolutional neural network technology, an AI-based image recognition model, NEXEN TIRE optimised the tread pattern to reduce noise and restrict road noise entering the cabin, and pattern retention technology helps maintain consistent performance even after tread wear reaches 50 percent of the wear limit.
The TUCSON contract illustrates NEXEN TIRE's OE capabilities in matching products to vehicle segments and market requirements. The company holds a broad OE portfolio spanning leading global premium automakers and volume models that account for significant regional sales. The supply follows recent OE fits for the Hyundai Avante, known as the Elantra in some markets, and the Kia Sorento.
John Bosco (Hyeon Suk) Kim, CEO, NEXEN TIRE, said, "The all-new TUCSON belongs to a segment with strong demand both in Korea and abroad, and this supply allows us to reach a wider range of drivers. As the supply extends beyond Korea to North America and Europe, we expect it to further strengthen our brand awareness in the global market."
GRI Agricultural Tyres Outperform VF Benchmark In Independent DLG Tests
- By TT News
- November 10, 2026
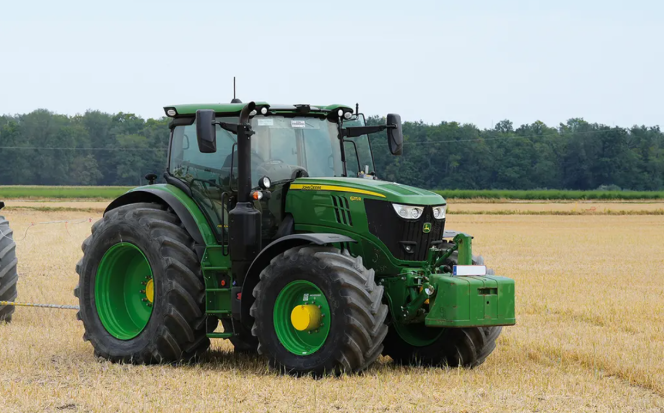
Global Rubber Industries (GRI) has reported higher traction, productivity and fuel efficiency for its GREEN XLR vFLEX 70 agricultural tyres than an established variable-footprint (VF) benchmark, following independent testing by Germany’s DLG TestService.
The Sri Lanka-based tyre manufacturer received the DLG Approved Quality Mark under Test Report 7616 after its tyres were assessed for traction, productivity, fuel efficiency and soil preservation at the testing organisation’s facility in Groß-Umstadt, Germany.
The tests used a John Deere 6R 215 tractor fitted with GRI GREEN XLR vFLEX 70 tyres measuring 710/70 R 42 on the rear axle and 600/70 R 30 on the front axle. The tyres were compared with an established VF reference tyre.
The results showed that the GRI tyres delivered 17.2 per cent higher traction and 3 per cent greater productivity than the benchmark. Hourly fuel consumption, measured in litres per hectare, was 3 per cent lower.
DLG concluded: "Overall, the GRI Green XLR vFLEX 70 impressed in the tested trials, particularly in terms of traction, productivity, and energy efficiency."
The productivity assessment measured hectares covered per hour, taking into account drawbar force, driving speed and wheel slip.
GRI said a three percent productivity improvement could translate into approximately 120 additional hectares covered over 1,000 operating hours, assuming a constant work rate of four hectares an hour. The company described this as an illustrative calculation rather than a measured test result.
The fuel-efficiency results also indicated potential operating savings. Based on an illustrative consumption rate of 20 litres per hectare, a 3 per cent reduction would save approximately 0.6 litres per hectare. Across 1,000 hectares, this would amount to about 600 litres.
GRI estimated that the saving would be worth approximately EUR 900 at a fuel price of EUR 1.50 a litre. It stressed that actual savings would depend on operating conditions, fuel consumption and prevailing fuel prices.
The DLG assessment also examined soil protection. However, the findings were only partially conclusive because usable measurements were available from a soil depth of 20cm under the selected test conditions.
Suresh Damodaran, Head Of Technical at GRI, said the independent assessment provided farmers with measurable evidence of the tyres' performance.
"These results are an important milestone for GRI and a clear validation of what our engineering teams have been working toward," said Damodaran. "Independent testing by DLG now gives farmers measurable evidence of how our tires perform in the field."
He added: "For farmers, the real value lies in what these numbers mean in the field," Damodaran added. "Stronger traction, higher productivity and lower fuel consumption all contribute to more efficient operations and better returns on their equipment. Our objective is not simply to manufacture high-performance tires, but to develop solutions that deliver measurable value to the people who depend on them every day."
GRI said the findings reflected its engineering capabilities in the agricultural tyre segment. It also noted that total cost of ownership would depend on other factors, including purchase price, service life, maintenance and operating conditions.
Global Rubber Industries manufactures specialty tyres for the agriculture, construction and material handling sectors. The company operates tyre production and mixing facilities in Sri Lanka and has a presence in more than 85 markets worldwide.
Continental Secures OE Approval For Volkswagen ID. Cross
- By TT News
- November 06, 2026
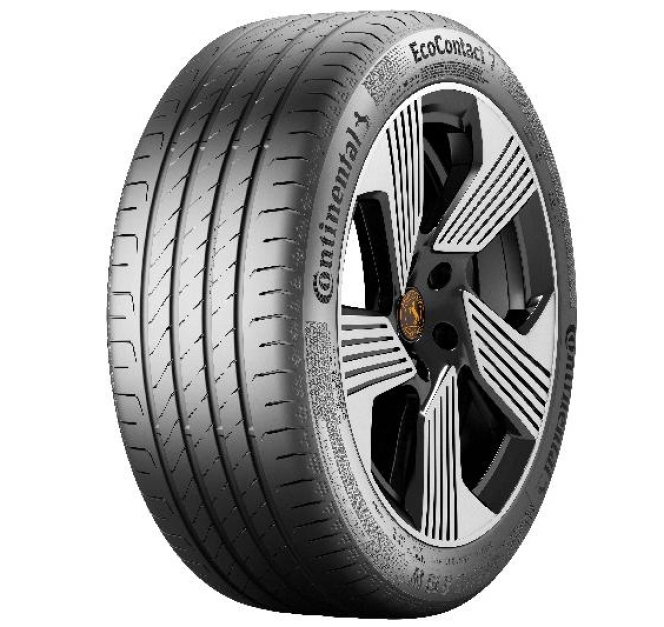
Continental has secured original-equipment approval for Volkswagen's new ID. Cross, an all-electric compact SUV that will leave the factory fitted with the EcoContact 7 summer tyre in 17-, 18- and 19-inch dimensions. For colder conditions, Volkswagen recommends the WinterContact TS 870 P, while the 18-inch AllSeasonContact 2 is suggested for motorists favouring a single year-round set.
Engineered for low rolling resistance and high mileage, the EcoContact 7 supports energy-efficient, cost-effective motoring. Its Smart Energy Casing technology employs innovative materials in the carcass, inner layer and sidewall to cut internal friction, while an Aerodimple sidewall structure reduces air turbulence behind the tyre and thus aerodynamic drag. A Silent Pattern tread design also dampens rolling noise, especially at city speeds.
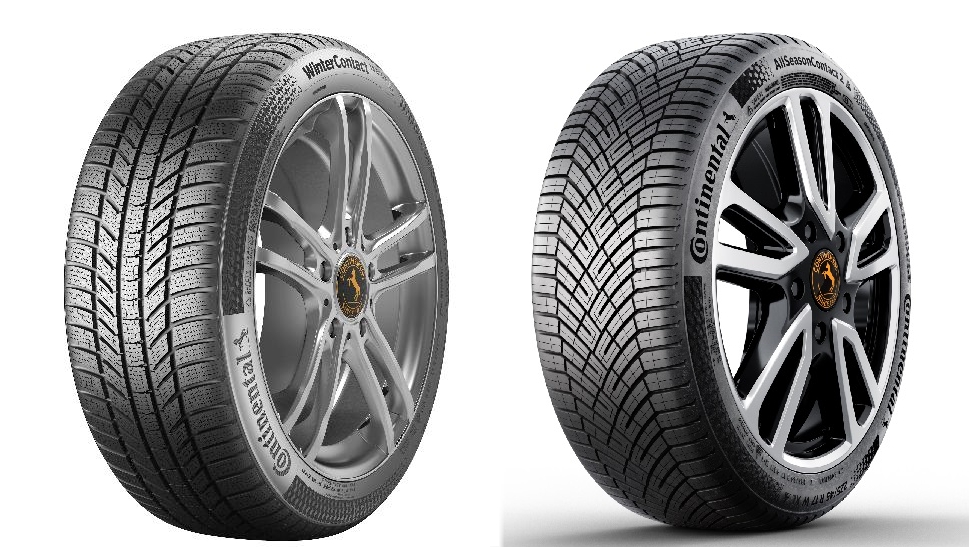
The WinterContact TS 870 P relies on its tread pattern and sipe layout for secure grip on snow and ice. The AllSeasonContact 2, meanwhile, offers dependable traction on dry and wet roads as well as in wintry conditions. Approved fitments span the EcoContact 7 in 225/55 R17 97T FR, 225/50 R18 95V and 225/45 R19 92T FR, plus the AllSeasonContact 2 and WinterContact TS 870 P, both in 215/50 R18 96T XL, across numerous countries.
Comments (0)
ADD COMMENT