Changing Tyre Dynamics In A Changing Car Market
- By Sharad Matade
- February 27, 2026
For Continental Tires India, the passenger vehicle market in India is entering a phase where scale and structure are finally aligning with its longstanding premium ambitions. Passenger vehicle sales reached a record 4.3 million units in 2024, expanding by 4–5 percent year on year, but it is the composition of that growth – rather than the headline volume – that is reshaping the company’s strategy. Utility vehicles now account for approximately 58 percent of total passenger vehicle sales, up sharply from about 51 percent the previous year, cementing SUVs and crossovers as the dominant force in the market.
This structural shift has direct consequences for tyre manufacturers operating at the upper end of the value spectrum. Larger vehicles bring higher kerb weights, bigger wheel diameters and greater expectations around refinement, safety and performance. For Continental, the change represents not merely an increase in addressable demand but a decisive move towards tyre categories where technology differentiation and pricing discipline can coexist.
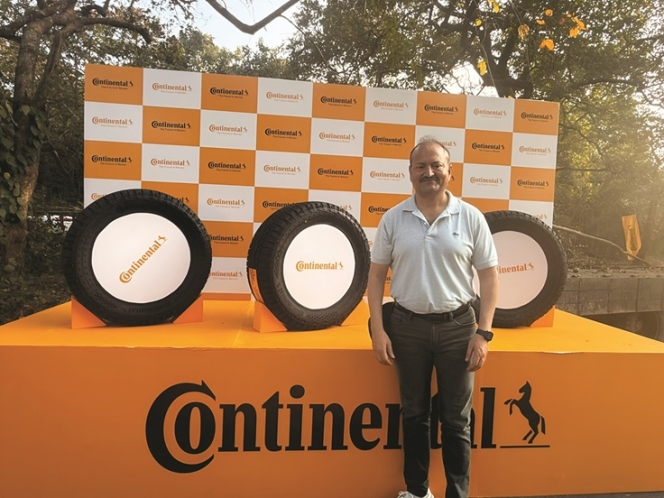
Samir Gupta, Managing Director of Continental Tires India, calls this phase a turning point, not a temporary high. He says the surge in utility vehicles – driven by electrification and more premium cars – fundamentally changes the economics of the passenger tyre market in India.
“Let me clarify one thing first. The utility vehicle segment is no longer small. Last year, around 60 percent of passenger vehicles sold in India were utility vehicles, and including first-time buyers upgrading within this segment, the share goes beyond 65 percent,” Gupta says.
Industry data broadly supports this assessment. SUVs alone contributed close to three-fifths of all passenger vehicle sales in 2024, with compact utility vehicles accounting for a significant share of incremental volumes. The overall passenger vehicle market, at around 4.3 million units, has thus become structurally skewed towards larger formats – an inflection with long-term implications for tyre sizing, load ratings and product mix.
This shift shows in replacement demand. As vehicle footprints grow, rim diameters are increasing. “The market is clearly moving from smaller to bigger rim sizes. Demand for 17-inch and above tyres is rising sharply,” Gupta says. While these tyres are still a minority, their growth far outpaces the overall passenger tyre market.
Electrification is accelerating the shift. A substantial proportion of electric passenger vehicles sold in India today are SUVs, and Continental expects EVs to account for more than 50 percent of the passenger vehicle segment within five years. For tyre manufacturers, this creates new technical requirements – higher torque tolerance, lower rolling resistance and stringent noise control. “That creates a significant opportunity for us because our strengths lie in premium, high-performance tyres,” Gupta says.
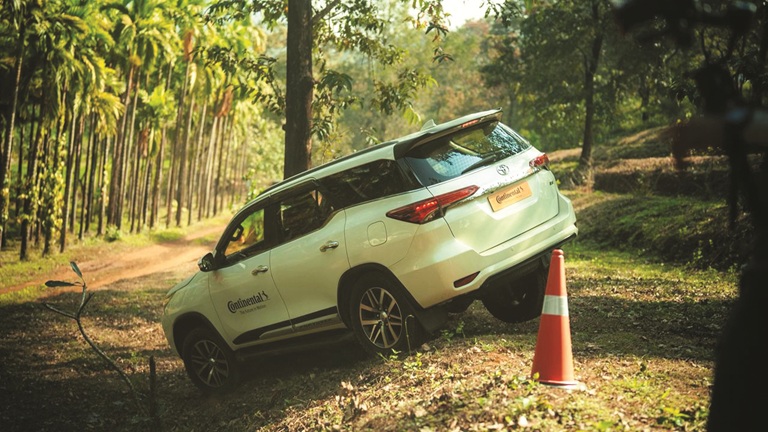
Despite these favourable structural trends, premium tyres have historically struggled to gain traction in India. For much of the past decade, the market remained intensely price-sensitive, with tyres treated largely as commoditised replacement items. Continental’s response, Gupta explains, has been consistent rather than tactical pricing. “Right from the beginning, we have focused on fair pricing. The idea is simple – if we can clearly differentiate on performance and consistently deliver on those promises, price recovery will follow,” he explains.
The broader environment is now becoming more supportive. As vehicle prices rise and consumers migrate towards larger, more sophisticated vehicles, willingness to spend on tyres that enhance safety, comfort and driving confidence is increasing. This trend is also evident at the top end of the market. Premium and luxury passenger vehicle sales reached approximately 51,500 units in 2024, up around 6 percent year on year and crossing the 50,000-unit threshold for the first time – a symbolic marker of premium consumption in India.
Gupta sees premiumisation extending beyond luxury vehicles. “Earlier, India was extremely price-sensitive, but that is changing in higher segments. Consumers are upgrading vehicles and are more willing to invest in tyres that enhance safety, comfort and confidence,” he says.
The intensification of competition, with global premium tyre brands expanding or re-entering India, is viewed as a positive development. “Competition is always good,” Gupta says. “It gives you room to grow and improve.” More importantly, he believes it will help reframe the market. “More premium players will help move the market away from being purely cost-driven to being value-driven,” he adds.
Replacement market dynamics reinforce this view. Of the roughly 32–33 million passenger tyres replaced annually in India, tyres sized 17 inches and above account for about 12–13 percent. While the overall replacement market grows at 5–6 percent per year, this high-diameter segment is expanding at over 20 percent annually, closely tracking the shift in new vehicle sales.
This sharper focus on passenger tyres also explains Continental’s decision to exit the truck and bus radial segment in India. Gupta stresses that the decision was strategic rather than operational. Continental entered the TBR market in 2014, invested significantly and received strong feedback on product performance.
However, the economics proved limiting. Gupta says, “TBR in India is largely a B2B, fit-for-purpose market. Even if you have the best tyre, willingness to pay remains limited because fleet operators are under constant margin pressure.” Although commercial tyres offer higher absolute margins per unit, they consume substantially more raw material. “One commercial tyre uses six to eight times the raw material of a car tyre. Percentage margins are actually higher in passenger tyres,” Gupta explains.
After reviewing its portfolio, Continental chose focus over breadth. Exiting TBR allows the company to concentrate capital, technology and management attention on passenger and light truck tyres, where differentiation is more readily monetised. Gupta rejects the idea that a narrower portfolio weakens the company’s position. Commercial and passenger tyre customers, he argues, are fundamentally different – one driven by procurement economics, the other by consumer perception and emotion.
Indian consumers, Gupta believes, are becoming more tyre-aware. “Premiumisation is happening across the vehicle industry, not just in tyres. As consumers move to larger and more premium cars, their expectations also rise,” he says. Where tyres were once treated as an afterthought, buyers increasingly recognise their role in braking, grip, noise and overall driving confidence.
This change is evident at the retail level. Continental now operates more than 200 brand stores across India, and feedback from retail partners suggests customers are more informed and more demanding. Availability remains critical. “There is no point launching premium tyres if customers cannot find them,” Gupta says.
To support future demand, Continental is investing around INR 1 billion at its Modipuram plant, with the focus squarely on passenger and light truck tyres. The expansion will extend manufacturing capability from the current 20-inch limit to 22–23 inches, aligning local production with emerging vehicle trends.
Localisation, Gupta argues, is about adaptation rather than compromise. Indian road conditions, climate and driving habits require specific tuning without diluting global performance standards. Education and availability remain the principal challenges.
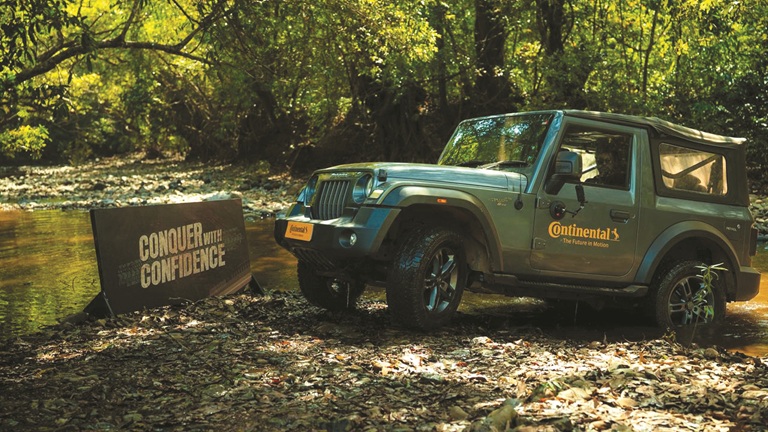
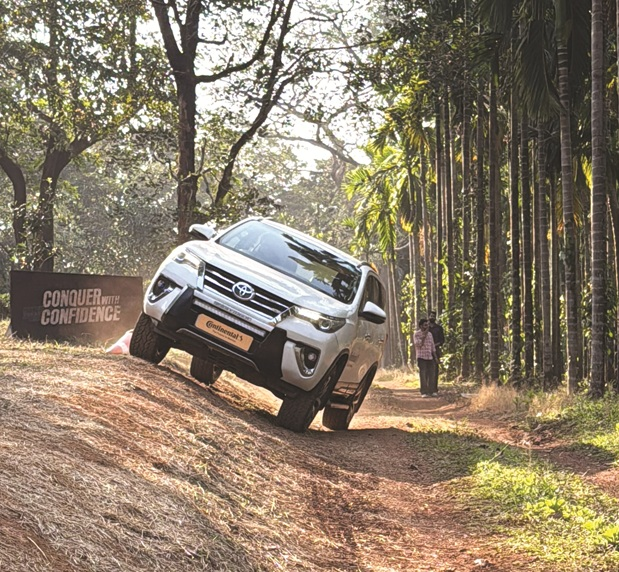
The recent launch of the CrossContact A/T² in India reflects this strategy. Introduced during Continental’s Track Day at Dot Goa 4x4, the product positions India among the early global markets for the tyre. “The first thing you notice is noise – or the lack of it,” Gupta says. “You hear the air-conditioning, not the tyre.” Ride comfort, grip and consistency across terrains define its appeal. As Gupta puts it, “Jahan tak soch jaati hai, wahan tak yeh tyre kaam karta hai.”
Looking ahead, Continental remains largely insulated from shifts in original equipment strategies, such as the gradual removal of spare tyres. Improved carcass design and stronger sidewalls are reducing puncture risk, but the company’s primary focus remains the replacement market.
For Gupta, the question is no longer whether India is ready for premium tyres, but how effectively manufacturers execute. “The market is finally ready for premium tyres,” he concludes. With passenger vehicle sales at record levels, SUVs firmly dominant and premium consumption expanding, Continental believes it is well positioned to grow alongside India’s evolving mobility landscape.
Grismer Tire & Auto Service Appoints New CEO And CFO
- By TT News
- September 28, 2026
Grismer Tire & Auto Service, a tyre and automotive service centre operator backed by CenterOak Partners LLC, has named Chris Blanchette as Chief Executive Officer and Mark Hedstrom as Chief Financial Officer. The announcement marks a significant leadership transition for the portfolio company.
Blanchette arrives with over two decades of senior leadership experience in multi-site consumer services, specialising in operations, strategy and business development. He most recently served as Chief Executive Officer of Service Minds, a residential electrical, plumbing and HVAC services provider. His background also includes serving as Chief Operating Officer of QAS, which operates Valvoline Instant Oil Change locations, along with senior operational positions at Advance Auto Parts, Bridgestone Retail Operations and Best Buy.
Hedstrom brings more than three decades of finance expertise to his new role. He previously held the Chief Financial Officer position at W.S. Connelly & Co., a multi-regional specialty distributor, and has also served as Chief Financial Officer for several private equity-backed consumer and distribution companies.
Eric Holter, Managing Director, CenterOak, said, “Chris Blanchette brings highly relevant leadership experience in the automotive aftermarket. He has led complex, multi-location organisations and understands how to translate operational discipline into sustainable growth. Together, Chris and Mark add important depth to Grismer’s leadership team as the Company pursues expansion in existing and new markets.”
Blanchette said, “Grismer’s 90-year history and the trust it has earned with customers set the Company apart. I am excited to join a business with such a strong legacy and see significant
- International Rubber Conference
- Society Of Rubber Science And Technology Japan
- James Busfield
- Nobuyuki Tamura
- Bridgestone Corporation
- Japan Rubber Manufacturers Association
- Aichi International Exhibition Center
- Aichi Sky Expo
Japan To Host International Rubber Conference After Decade-Long Gap
- By TT News
- September 25, 2026
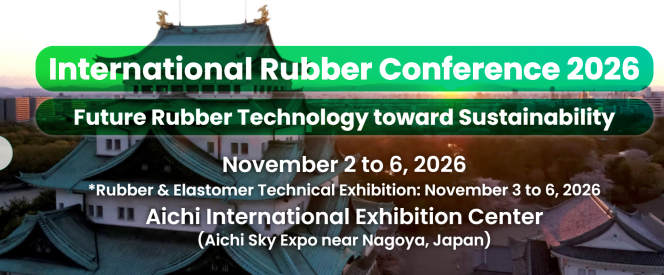
The International Rubber Conference (IRC) will return to Japan in November for the first time in a decade, with more than 271 technical presentations and over 117 exhibitors expected to take part.
The event, known as IRC 2026 Aichi, will be hosted by the Society of Rubber Science and Technology, Japan, alongside the Rubber & Elastomer Technical Exhibition in Aichi. It is scheduled to run from 2nd to 6th November, with the exhibition opening a day later and continuing until 6th November .
Held at the Aichi International Exhibition Center, also known as Aichi Sky Expo, the venue is located near Chubu Centrair International Airport and can be reached from Nagoya Station in about 28 minutes by train.
The conference programme will feature more than 271 presentations spanning rubber science, technology and industrial applications. Participants include James Busfield of Queen Mary University of London and Nobuyuki Tamura of Bridgestone Corporation, who also chairs the Japan Rubber Manufacturers Association. More than 400 delegates have already registered.
Running alongside the conference, the Rubber & Elastomer Technical Exhibition will host more than 117 exhibitors, ranging from raw material suppliers and machinery manufacturers to tyre makers and testing-equipment providers. The exhibition will be open to visitors free of charge.
The International Rubber Conference, first held in 1966, rotates annually across global host cities. The last event in Japan took place in Kitakyushu in 2016, with subsequent editions held in Haikou, Istanbul and Bangkok.
Pirelli Board Approves EUR 1 Billion US Investment Plan And Organisational Restructuring
- By TT News
- September 23, 2026
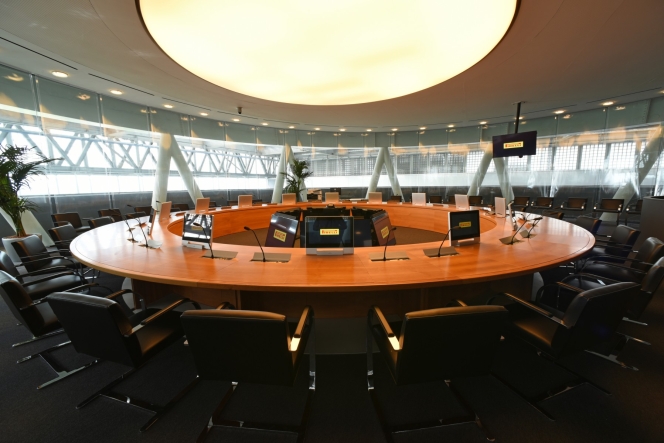
Italian tyre major Pirelli has announced a multi-year investment plan worth approximately EUR 1 billion (USD 1.2 billion) to expand its manufacturing facility in Rome, Georgia in the United States. The motion passed by majority vote, with board members Zhang Haitao, Xi Xiaohong and Wang Kun voting against the proposal.
The capital expenditure program, scheduled to begin in 2027 and will go through 2033, aims to expand annual production capacity at the Georgia site to six million tyres and create approximately 1,000 jobs.
The United States represents the largest market for high-value tyres globally, accounting for roughly 40 percent of global volumes. The project will be carried out in two phases without altering Pirelli's financial targets for 2026.
Phase one of the expansion will introduce modular robotised production systems based on Pirelli's Modular Integrated Robotised System technology, scaling annual output to three million tyres starting in 2028.
In phase two, the company will begin construction of an automated production facility to add three million units of annual capacity. The expanded plant will produce connected tyre systems, including Cyber Tyre technology, following market authorisation granted by the US Bureau of Industry and Security under Italy’s 2026 Golden Power Decree.
Alongside the investment decision, the board approved an organisational restructuring resulting in the immediate elimination of the Corporate General Management function. As part of the changes, Corporate General Manager Francesco Tanzi will step down from his executive role, maintaining an employment relationship through 31 December 2026 to facilitate the leadership transition.
Under the terms approved by the board and the Remuneration Committee, Tanzi will receive a severance payment equivalent to 13 months’ remuneration, payable by February 2027, alongside accrued rights under existing short-term and long-term incentive plans. He has agreed to a two-year non-compete covenant covering Pirelli's primary operating regions in exchange for 130 percent of his gross annual salary, paid in eight quarterly instalments. Following the end of his employment, Tanzi will provide advisory services under a two-year consultancy contract with an annual fee of EUR 350,000, plus non-monetary benefits valued at EUR 45,000.
Bridgestone Appoints Stefano Sanchini As President Of Europe Sales
- By TT News
- September 19, 2026
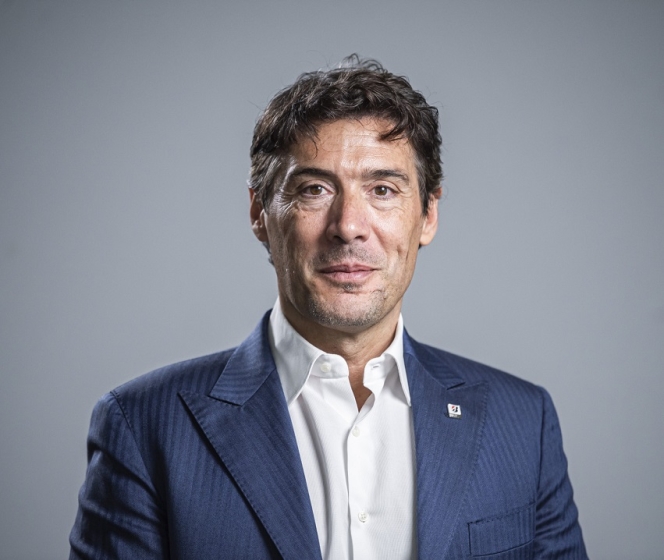
Bridgestone has announced a European leadership appointment aimed at sharpening customer focus, streamlining engagement across product groups and supporting its ongoing growth plans. Stefano Sanchini will become President, Europe Sales, effective 1 October 2026, leading the company’s European sales organisation across both Consumer and Commercial segments.
The expanded role unites sales activities spanning passenger car, truck and bus, agriculture, off-the-road, motorcycle and original equipment. Sanchini brings over 20 years of international leadership experience in the automotive and tyre sectors, with a career covering Europe, Middle East, Africa and India. Since joining Bridgestone in 2017, he has held several senior positions, including Managing Director of Bridgestone India.
Most recently, as Vice President for Consumer Replacement in Europe, he helped strengthen customer engagement, commercial performance, profitability and regional market growth. Bridgestone said the appointment underscores its commitment to customer relationships, commercial execution and simpler cross-market operations. Sanchini will pursue sustainable growth while developing capabilities and partnerships supporting the company’s long-term European strategy.
Mete Ekin, Group President EMEA, said, "Our customers increasingly operate across multiple product categories and expect a consistent experience wherever they engage with Bridgestone. By bringing our sales activities together under one European structure, we are creating a simpler, more connected organisation that will help us respond faster, collaborate more effectively and continue building strong partnerships with our customers."
Comments (0)
ADD COMMENT