Certainty With Certified Rubber
- By Juili Eklahare & Gaurav Nandi
- August 23, 2022
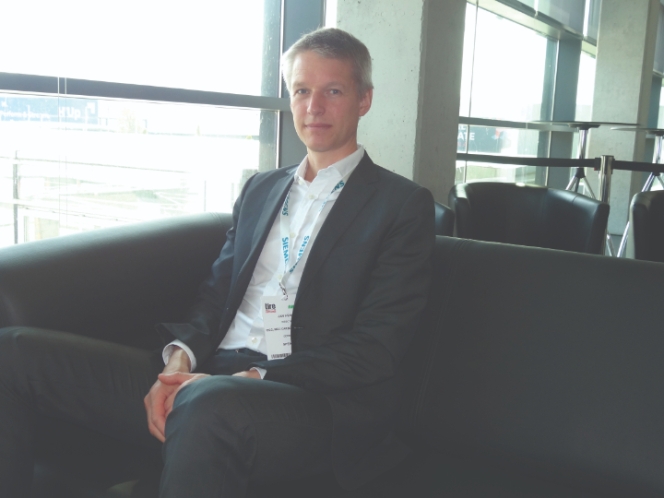
Rubber certainly has its role to play in forest landscapes across the world, with natural rubber plantations having risen as a substantial basis of deforestation. One element that addresses deforestation concerns is the correct certification of rubber – be it natural or synthetic. International Sustainability & Carbon Certification (ISCC), a globally leading certification system, works with the objective of providing sustainability solutions for fully traceable and deforestation-free supply chains, inter alia involving the rubber industry. ISCC was one of the presenters at the Tire Technology Expo 2022 at Hannover, Germany, and Dr Jan M Henke, Director, ISCC, threw light on the nitty-gritty of certifications in the rubber industry, their clients in the tyre and rubber industry and more, in an interaction with Tyre Trends.
Can you tell us about your global sustainability scheme?
Our global sustainability and carbon certification scheme has certified companies in more than 100 countries. We certify entire supply chains from farms to plantations and forestry, and also the point of origin of waste and residues, biogenic and fossil waste. This is also covering rubber and natural rubber. Moreover, we cover biogenic waste and residues, including fossil waste, like carbon black, which is, again, used in the rubber industry. We also certify pyrolysis, where recycled mixed plastic waste can help produce synthetic rubber out of the pyrolysis oil. And we certify the entire supply chain, sustainability of raw material.
What is Meo’s role?
Meo initiated ISCC in a multi-stakeholder process a long time ago. It once was a Meo project and went on to become an operations and certification scheme. It was even recognised by the European Commission and some other authorities. It later got segregated from Meo, and ISCC is governed by the ISCC Association with more than 200 members.
So, what role does Meo play in this in case of certification?
Certification is always by independent, third-party certification bodies. ISCC is the standard development. Today’s ISCC was once a project of Meo. It then went on to become independent and operational, and was no longer a project but an individual entity running and further developing and improving the certification scheme.
The operations of the certification system, database, registration, qualification, training programme, integrity programme, the website and all the day-to-day business is done by ISCC. We are currently incorporating 45 certification bodies that are actually doing the on-site audits based on the ISCC standard.
Is ISCC recognised by the European Union?
Yes, it is being used in many sectors, like in bio energy, bio fuel, renewable transport fuels etc. In fact, ISCC is also recognised by the European Commission and by companies based on their sustainability standards and different industry initiatives.
Hence, ISCC is active on a really broad scale, covering different types of raw materials, natural rubber being one of them. We are also covering waste and residues for pyrolysis and their outputs. We then go to all the different end markets, which can be polymers, rubber, tyres, packaging, all types of plastic products, bio energy or any type of renewable fuels, aviation fuels, maritime fuels etc. This is global and is being used in more than 100 countries.
Tyre companies are talking about sustainability, but the larger part of the industry is of small stakeholders, especially in the natural rubber segment, where traceability and accountability are the main issues. How do you see this?
That’s a big challenge, especially in rubber production. At the cultivation level, there are a lot of small holders. There also exist large plantations that are easier to implement and certify. However, it’s definitely a bigger challenge with the small holders; it always depends on how well they are organised, whether there are certain structures, cooperatives or some central units.
Can you tell us about the certification of natural rubber?
The certification of natural rubber is definitely possible. Palm oil is maybe another example where the setup is quite similar sometimes. Also, with respect to the small holders, sometimes the companies are the same. Furthermore, we are very active in the palm oil sector with ISCC. We now also see a demand for natural rubber sustainability certification.
Is there a different process for getting certified in the rubber industry or is it a standard process?
It’s a standard process. It works on plantation. In fact, it works more or less the same as for palm plantations. But you certainly need to make sure that all the small holders reach a certain level, which is difficult. So starting out, bigger plantations may be easier because it’s easier for them to properly prepare for the certification audits. And then, you need to involve more farmers, step by step.
Who decides the standard process to get the certifications?
ISCC develops the standards and the requirements in the multi-stakeholder process. It then comes down to a company saying that it wants to become certified, use ISCC and also make certain claims and communications to its customers and stakeholders. They then reach out to a certification body, that is cooperating with ISCC. Following this, the certification body will do the audit on site – the third-party auditor will also make a decision on the issuance of the certificate.
Can tyre manufacturers get different certifications? For instance, one for natural rubber and another one for synthetic rubber? Or do they get one for all?
If tyre manufacturers source raw material for manufacturing from natural rubber but also synthetic rubber and everything under ISCC, then it’s one audit. Then the auditor would look into aspects of the volume of natural rubber being used that has been certified, although upstream. If one buys from certified suppliers and if the same auditors check, then aspects like the share of the certified synthetic rubber being used, the share of carbon black, etc. are taken into account. And finally, everything can be put together and a certain claim can be made.
Can tyre companies get a separate certificate for natural rubber?
Yes, they can. They can have separate certificates for natural and synthetic rubber both, or even of everything together. As for the final tyre, let’s say, if it’s 20 percent natural rubber and 20 percent synthetic rubber (40 percent of the tyre), then they can make certain sustainability claims on use of sustainable, circular materials etc.
What is the value of a certification?
It’s no deforestation – that’s key when it comes to natural rubber. When you certify, ‘no deforestation’ is the core requirement and deforestation is not allowed under ISCC. It is about additional environmental and social human rights criteria. This fits fine in this part of ISCC’s sustainability standard. And then it’s certainly about traceability in the supply chain, all the way in the end to the final tyre. And if this is established, then you can certainly make claims about the rubber or the final tyre, saying that it has been sustainably produced, based on sustainably sourced raw materials etc.
Plus, if you do this in a smart way, then you can actually cover the natural and synthetic rubber. Natural rubber and synthetic rubber are both very important parts of the final tyre. Both can be covered under ISCC.
Deforestation is a big issue, mainly in Southeast Asian and African countries. How difficult is it to keep an eye on that?
It’s not always easy to handle. Deforestation is not allowed under ISCC; there is a cut-off date of January 2008. If there was deforestation after January 2008, one cannot become certified. However, replanting or a change from palm to rubber is not considered as deforestation.
For example, if you have a palm plantation and if you cut it and plant rubber after 25 years, then that’s not deforestation. That’s just normal replanting.
Also, ISCC is certainly doing assessments, supported by remote sensing. Our core principle is no deforestation, which is very important to ISCC and its stakeholders. ISCC is not just us doing the operations in Cologne; there’s the ISCC Association for the multi-stakeholder dialogue. It has over 200 members from entire supply chains, industries, plantation companies, mineral oil, chemical companies, converters etc. We also have research organisations from different regions involved. In fact, also a number of non-governmental organisations are members of the ISCC Association.
The association meets annually and makes important strategic decisions and elects the ISCC Board. Due to the representation of the research sector and non-governmental organisations, there is quite a good balance of what people want and further development.
Can you tell us about the commercial benefits involved in having a certification?
There is a big value in it. It reduces sustainability risks for companies, helps to establish monitoring, protects the license to operate and has commercial value. For example, the OEMs ask for more sustainable products or lower greenhouse gas emissions. They all have climate neutrality commitments in place and need to start delivering step-by-step now; they need to show what are the activities that they are engaged in and how those improve sustainability in the overall supply chain. Here, ISCC certification can be used.
How do you maintain transparency in certification as a third party?
There is an annual audit. The certificate is valid for one year and then there is a re-certification. The company needs to provide evidence in every re-certification that the rules are being followed. And if they are not, a renewal of the certificates is not possible.
We certainly have quality management and training for companies and the auditors as well, who conduct on-site audits. What’s more, we have our own integrity programmes, where we send out our own auditors. These auditors work for ISCC and double-check the performance of the companies and the work of third-party auditors. Therefore, this integrity programme is key. We have the website where all the certificates are being published and the entire standard is public.
Do you help companies improve their sustainability supply chain?
No, we don’t consult. At ISCC, we are not involved in supporting the companies in order to improve. We have the standard and we conduct the training for companies. The preparation for the audit is not where ISCC is involved; it’s independent from that type of work. And the certification bodies are not allowed to consult in parallel either. ISCC is the independent standard that is used to certify that companies fulfil the sustainability requirements.
What are the other segments that you cover in the tyre industry?
It’s the entire supply chain. Petrochemical industries, tyre manufacturers etc. can all be covered. This also includes everything from plantations to the end product in the tyre industry.
Which is the easiest and the toughest one to certify?
All elements of the supply chain need to be covered.
This can sometimes be a challenge in the beginning, so as to convince your suppliers and also get certified. But, in truth, we have more than 6,000 certificates under ISCC. So there are already a lot of players that have valid certificates, and now this is starting to move into the space of rubber and tyre manufacturers.
Can you tell us about your clients in the rubber and tyre industry?
We have requests from many tyre producers right now. Some producers are certified already. Plus, we have requests for carbon black and first requests for natural rubber. We see the number of requests increasing, and we do have first certificates and first registrations from tyre producers. So we expect this to rise further as the industry needs to show compliance with their sustainability and climate neutrality commitments.
We see the entire tyre industry now targeting sustainability. So how do you find more opportunities and what’s your plan to get more client support?
ISCC started to get really further engaged in the rubber and tyre industry about a year ago; the industry has started understanding the standards, participating in ISCC trainings, joining our stakeholder events etc. Therefore, step by step, they got to know ISCC better and what it could do for them. They have now even started to get involved and do certifications, including reaching out all the way to the cultivation of natural rubber.
Are you going to focus on the Asian market?
Yes. In fact, we already have a few hundred certificates in Malaysia, Indonesia and other countries in the region. These markets are truly important. Our other key markets are North America and Europe, while we are also active in Africa and South America.
We are, eventually, trying to do more and convince people to become certified, show compliance to sustainability requirements, engage in a continuous improvement approach to become more sustainable and then allow manufacturers to really make claims.
- AZuR Chemical Recycling Project Group
- AZuR Network
- End-Of-Life Tyres
- Tyre Pyrolysis
- Recovered Carbon Black
- Tyre Pyrolysis Oil
- Pyrolysis Gas
New Research Quantifies Environmental Benefits Of End-Of-Life Tyre Pyrolysis
- By TT News
- October 15, 2026
New research findings from a doctoral dissertation by Dr.-Ing. Sebastian Bogdahn examine how end-of-life tyres can yield high-quality recovered carbon black (rCB) through pyrolysis while delivering substantial environmental benefits. The work, titled ‘Production and Environmental Assessment of High-Quality Carbonaceous Materials from End-of-Life Tyre Pyrolysis’, was presented in condensed form at an AZuR Chemical Recycling Project Group meeting in Dillingen/Saar on 1 October 2026.
The dissertation tackles how end-of-life tyres can be recovered and recycled to maximise their value. Pyrolysis is identified as a complementary technology that helps close recycling gaps in the circular economy and offers an alternative to fossil-based carbon black, a material that plays a crucial role in determining tyre properties.
In the pyrolysis process, rubber granules from processed tyres undergo thermal decomposition without oxygen, producing three main streams: solid rCB, tyre pyrolysis oil and pyrolysis gas. Previous evaluations of such technologies often separated technical and environmental perspectives, relied on secondary data and lacked standardised methodologies, making findings difficult to compare.
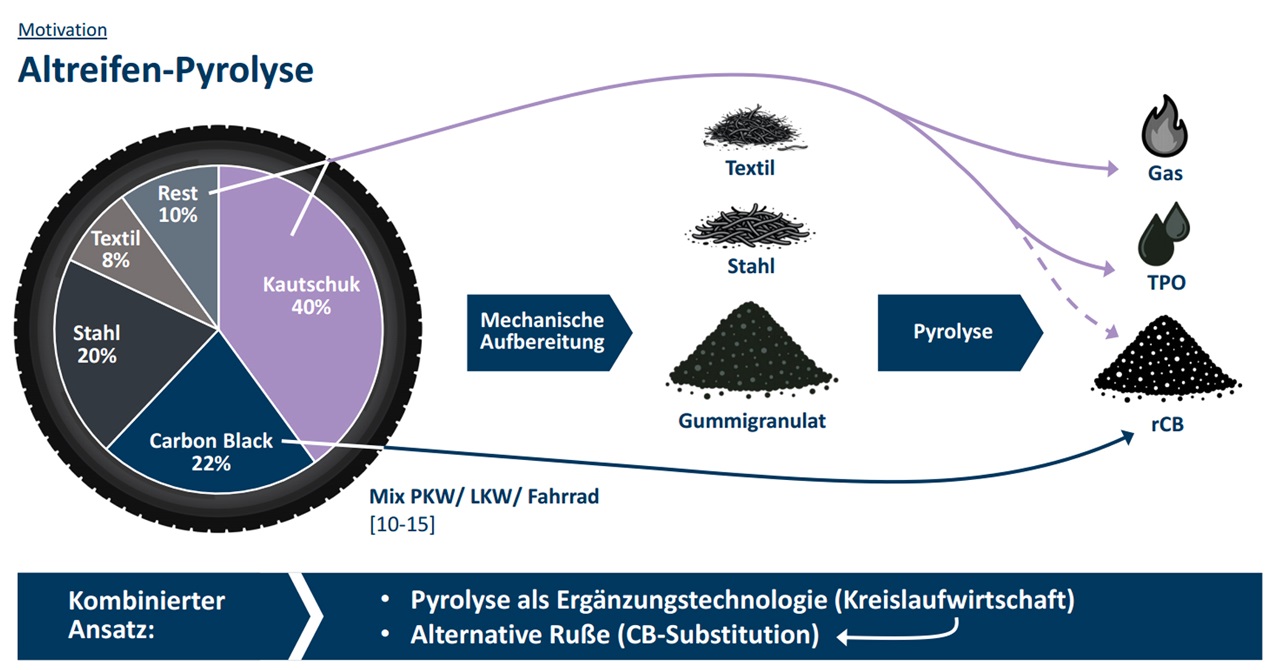
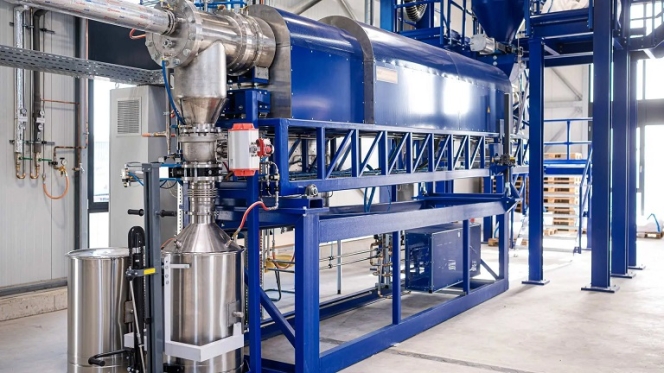
Image credit: Dr.-Ing. Sebastian Bogdahn
Bogdahn overcomes these limitations by integrating a technology-specific process model with a detailed life cycle assessment model. This combination enables a scientifically robust environmental evaluation of pyrolysis and its secondary raw materials using reliable primary data. A central component is a process model that mathematically describes material conversion by combining reaction kinetics, reactor behaviour and mass and energy balances.
Starting with laboratory-scale experiments, the model was scaled up and validated using a pilot-scale rotary kiln at the Institute of TH Köln. Comprehensive laboratory analyses of feedstocks and products supported development and validation. Optimal conditions for the investigated system were found at 650 degrees Celsius with a residence time of about one hour, achieving complete material conversion and high-quality recovered carbon black. Product distribution was roughly 40 percent rCB, 37 percent TPO and 23 percent pyrolysis gas by weight.
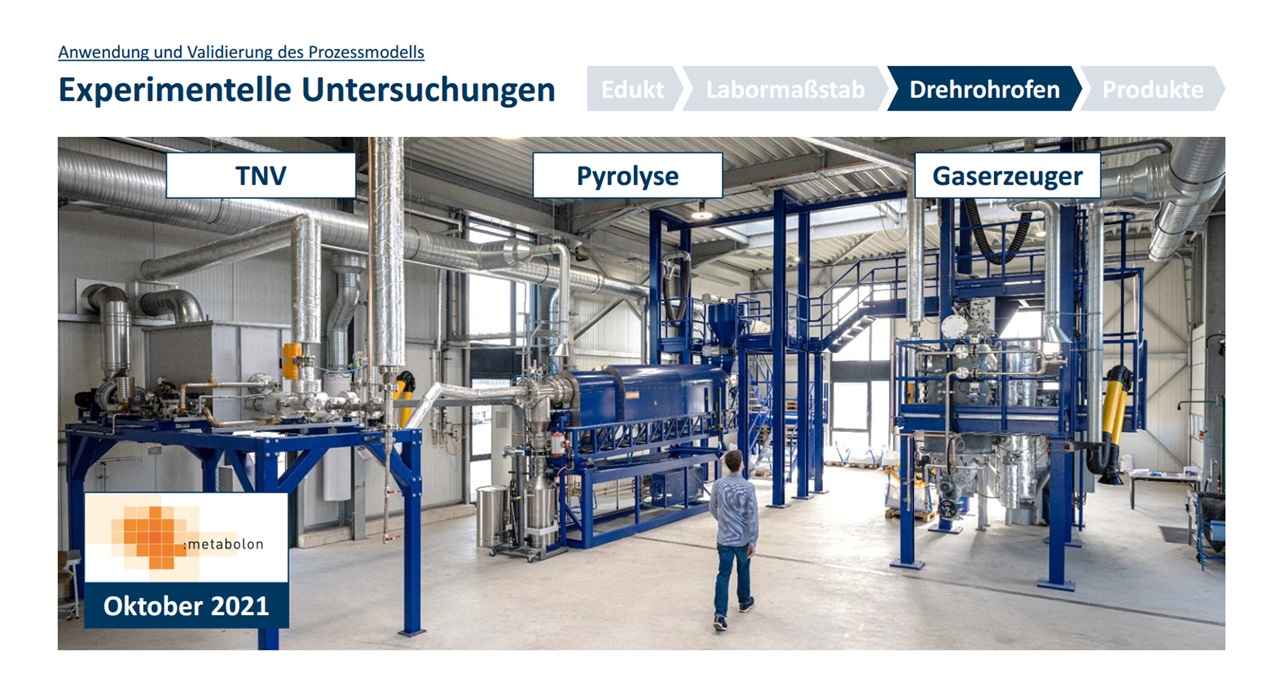
Image credit: Dr.-Ing. Sebastian Bogdahn
Using validated primary data, Bogdahn conducted a comprehensive environmental assessment and developed a methodological matrix covering relevant standards and guidelines to address inconsistent approaches. In the rotary kiln baseline scenario, one metric tonne of recovered carbon black results in a global warming potential over 100 years of about 918 kilogrammes of carbon dioxide equivalents, compared with the International Carbon Black Association’s global industry average of 3,910 kilogrammes for conventional fossil-based carbon black, a reduction of approximately 77 percent. Even after a quality adjustment for lower carbon content, the reduction remains about 70 percent. The study followed ISO 14067 and underwent independent external critical review under ISO 14071, also covering TPO and sustainable carbon black.
Further improvements remain possible. Emissions mainly stem from electricity consumption and gas combustion, with rCB processing accounting for about 44 percent, pyrolysis gas cleaning and combustion about 36 percent and tyre shredding about 19 percent. Sensitivity analysis confirms that renewable electricity offers substantial additional greenhouse gas reductions, reinforcing that a circular economy achieves genuine sustainability only when powered by renewable energy. Enhancing material quality through demineralisation and activation could enable higher substitution rates for fossil-based carbon black.
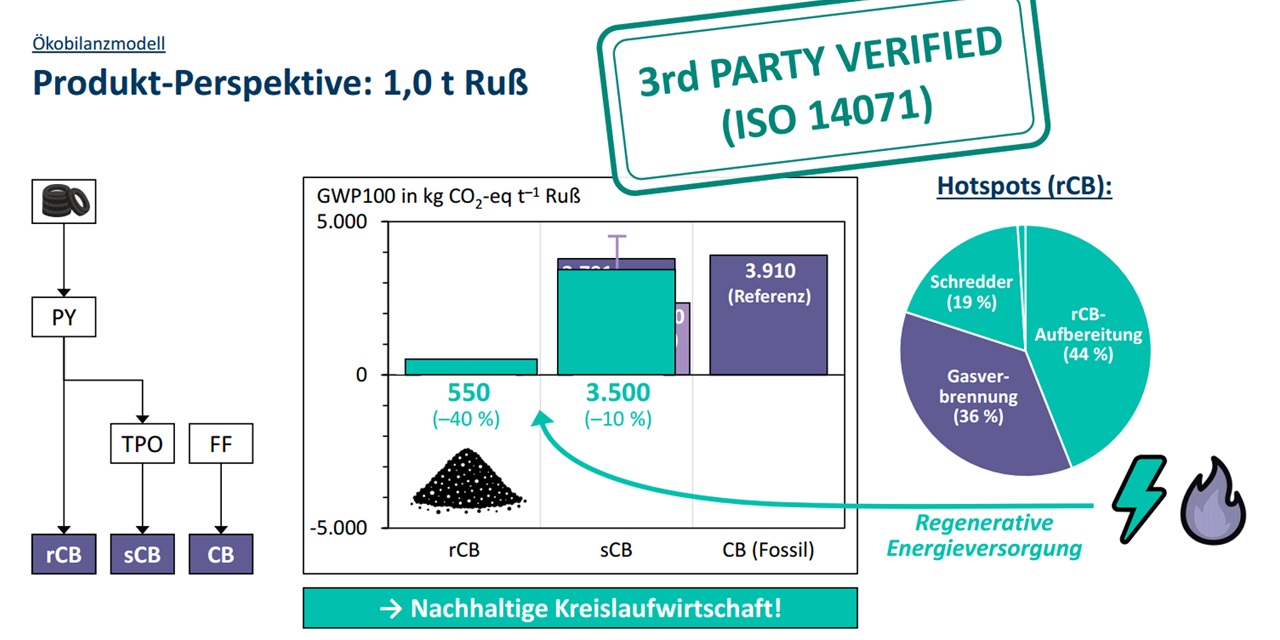
Image credit: Dr.-Ing. Sebastian Bogdahn
A central conclusion extends beyond pyrolysis itself. Raw materials, tyre manufacturing, the use phase and recovery pathways form an interconnected system spanning the entire tyre life cycle, closely linked to the carbon black, chemical, steel and energy sectors. Achieving circularity requires collaboration across systems and industries, along with greater methodological harmonisation and stronger integration of industrial value chains. The AZuR network’s work reflects this need, recognising that extended tyre use, repair, regrooving, retreading, mechanical recycling and appropriate chemical recycling must all function as interconnected elements of the value chain.
Tyres Europe Backs CARUSO Findings As EU Data Act Marks One Year
- By TT News
- October 15, 2026
Tyres Europe, as part of a coalition of 10 European associations representing consumers and automotive and mobility service providers, has issued a joint press release welcoming the latest CARUSO Connected Vehicle Field Test assessing the EU Data Act’s implementation across 29 major vehicle manufacturer groups. The findings confirm the legislation established important principles for accessing vehicle-generated data and encouraged some manufacturers to engage for the first time. One year on, however, the framework remains insufficient alone to enable a competitive, innovative connected mobility market.
Covering 15 automotive use cases across 28 vehicle manufacturer groups, the study concludes that while data access has improved, conditions for competitive, scalable, multi-brand services are still lacking. Access remains fragmented, inconsistent and often commercially or technically impractical across the car parc. Limited third-party access, differences in data scope, quality and coverage, and restrictive commercial terms continue to undermine the business case for innovative services. Genuine multi-brand development remains unattainable, preventing consumers and businesses from fully benefiting from connected mobility.
For many manufacturers, implementation has become a compliance exercise rather than a genuine effort to enable market access. Independent providers face limited datasets, restrictive terms, manual approvals, manufacturer-specific consent mechanisms and inconsistent technical solutions. Such approaches may satisfy the Data Act’s broadly defined obligations but are incompatible with the real-time, automated access modern digital services require.
Strong enforcement matters. Manufacturers respond faster where national authorities investigate complaints and apply enforcement mechanisms. Without consistent, harmonised, proactive enforcement across the European Union, Data Act rights risk remaining largely theoretical for a significant share of Europe’s vehicle fleet.
The coalition urges European Union institutions and Member States to enforce the Data Act consistently, issue clear guidance on fair, reasonable and cost-based compensation and use forthcoming reviews to reinforce rather than weaken it. Dedicated automotive legislation should establish common access conditions, interoperability requirements, initial technical and data delivery standards and safeguards against discrimination. Effective access must cover vehicle-generated data and the in-vehicle functions and resources needed to develop, scale and deliver digital mobility services, enabling fair competition, growth and investment.
According to the coalition, the Data Act was an important first step, but horizontal legislation alone cannot create a workable multi-brand market. Implementation varies widely: of 28 manufacturers, nine (32 percent) have barely implemented the Act; 18 (64 percent) lack adequate third-party pricing; 18 (64 percent) lack adequate data provision; and 19 (68 percent) lack an adequate API solution. Sixteen manufacturers (57 percent) enable none of the use cases, while only nine support the most feasible ones. Without stronger enforcement and dedicated automotive legislation, Europe will fall short of its innovation, consumer choice and fair competition ambitions.
CEAT Q2 FY27 Revenue Rises 26% to INR 47.62 Bln
- By TT News
- October 14, 2026
CEAT reported a 26 percent year-on-year increase in consolidated revenue to INR 47.62 billion in the second quarter of the 2026-27 financial year, while net profit stood at INR 1.12 billion as higher raw material costs continued to weigh on the tyre maker.
The company’s consolidated earnings before interest, tax, depreciation and amortisation (EBITDA) margin was 9.5 percent, according to its unaudited results for the quarter ended 30 September.
Arnab Banerjee, Managing Director and Chief Executive, said revenue growth was supported by premium segments across business units. He added that the conflict in West Asia had kept raw material costs high, prompting the company to tighten cost controls.
CEAT expects to deliver double-digit revenue growth in the second half of the financial year, alongside further price increases, Banerjee said.
On a standalone basis, revenue rose 23 percent year on year to INR 45.48 billion. EBITDA margin was 10.14 percent, while net profit reached INR 1.64 billion.
Kumar Subbiah, Chief Financial Officer, said commodity costs were expected to remain elevated in the third quarter. The company would continue to pursue measured price increases and improve its product mix to manage cost pressures.
Subbiah said debt increased during the quarter, largely because of capital expenditure of close to INR 4.9 billion to expand capacity in areas with high utilisation, as well as dividend payments.
He added that CEAT would maintain financial discipline while investing to meet demand and support profitable growth.
Michelin Expands Delhi Presence With Dwarka And Karol Bagh Outlets
- By TT News
- October 14, 2026
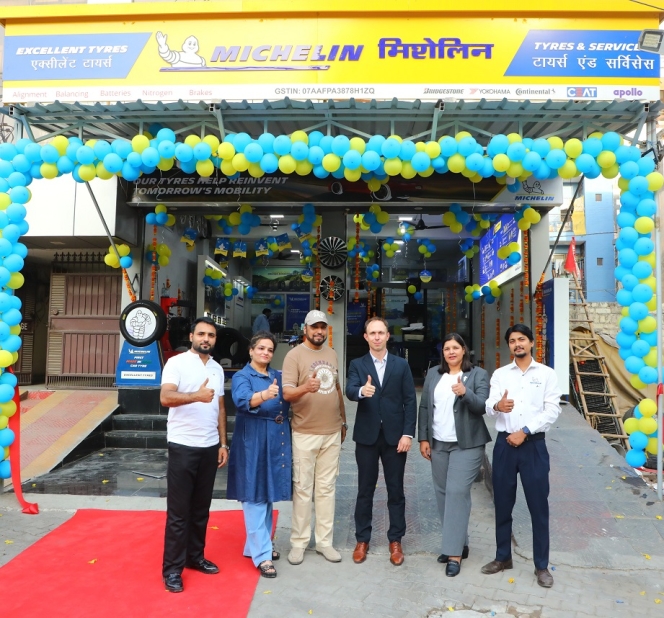
Michelin has strengthened its retail presence in India by launching two Michelin Tyres & Services outlets in Delhi, located in Dwarka and Karol Bagh. The openings make Michelin's premium tyre range, including the Made-in-India Primacy 5, accessible to customers in west and central Delhi, alongside professional fitment and tyre care. The Dwarka facility was inaugurated by Benjamin Coesnon, Marketing Director India.
The Dwarka outlet, operated with Excellent Tyres, covers 1,500 sft and caters to one of Delhi's largest planned residential sub-cities and its expanding south-west corridor. Excellent Tyres, established in 1994, brings over 30 years of experience in the capital's tyre trade. Meanwhile, the Karol Bagh store, run with Rana Tyres, spans 1,000 sft in a prominent automotive trade hub. Founded in 1977 and now led by its third generation, Rana Tyres contributes nearly five decades of technical knowledge and a loyal clientele.
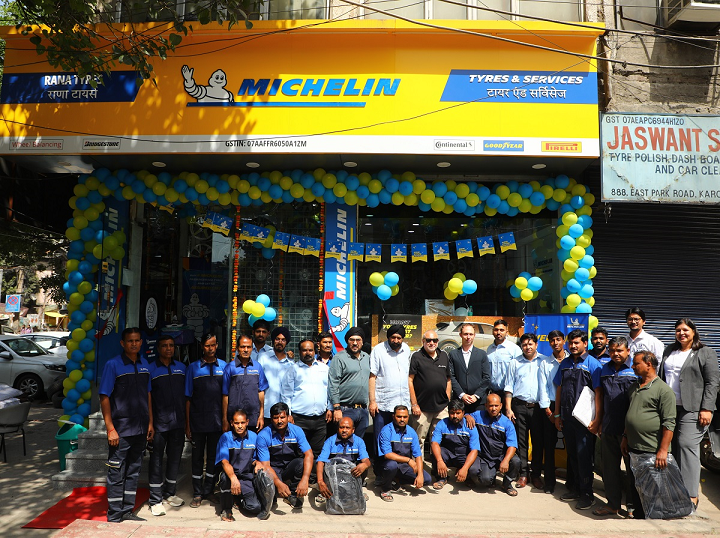
The expansion reflects Michelin's sustained commitment to India. Its distribution network now exceeds 800 points of sale, while over INR 28 billion has been invested in the Chennai manufacturing plant. A further INR 6.86 billion went into a passenger car tyre line that now produces the Primacy 5 for Indian buyers. The new stores aim to deliver safer, more durable and higher-performing mobility.
Shantanu Deshpande, Managing Director, Michelin India, said, " Delhi is one of the largest premium car markets in the country. Expanding our presence in Delhi will provide accessibility to today's customers and serve the next wave of premium car owners. With the Made-in-India Primacy 5 now available at these stores, customers in the capital can get Michelin's globally benchmarked safety and longevity, backed by expert service from trusted partners. India remains a key growth market for Michelin, and Delhi is central to how we continue to build our presence."
Comments (0)
ADD COMMENT