

Every five years is the main path of crisis in the tyre industry and it begins to change the following year, the third year in a row, in which the stage of another bottleneck is initiated! These trends prevailed during the periods 2013, 2008 and 2003. Global risks accelerated in 2018 as the United States and China fought harder for trade and the uncertainty surrounding Brexit reduced car sales in Europe, UK, India, China and parts of South America. The effects of the pandemic later hit the world during an ongoing crisis. All of them have led a multidimensional recession that will lower tyre sales. Few of the older Goodyear and Bridgestone factories closed during the last crisis years in 2013 and 2018. However, production facilities in Eastern Europe were very functional during those years.
In fact, every change in the global economy affects related industries, suppliers and third parties in chain reactions. What is the real spark that makes Eastern Europe the center of attention? Is it globalisation or tariffs and labeling that were introduced to prevent Far East companies attacking the European market? Both have shown effects in recent years. Game changes accelerated after the Trump administration. Many industries in China, including tyre manufacturers, have suffered the effects of trade struggles.
Tariffs and labeling that were introduced to prevent Far East companies attacking the European market are so far effective after years.
At the end of 2017, there were around 600 tyre factories in China. After a year, only 450 of them survived. Many more are expected to close by the end of 2020. Only 200 of them are expected to remain under a dozen parent brands, which means China's tyre factories are at the forefront of the competition in terms of price and quality. What if manufacturers of economical tyres in Eastern Europe did not exist today? The demand supply chain would potentially work for Chinese brands. The active period of closed factories would be postponed by a few years. But one day they might fail in the competition.
The European tyre production threatened by the destocking of distributors in 2012 and the big fives remain in a situation of closure of old and less profitable factories in 2013.
When we come to the 2010s, the nature of the tyre market in Eastern Europe began to differentiate from mainstream Europe. In year 2012, when the market size was around 300 million, 10% fewer tyres were sold in Europe compared to 2011. In contrast, the market share of cheaper import tyres reached 25 percent in those years. However, the tyre market in Poland and the Czech Republic grew, which was on the opposite side. The European tyre production threatened by the destocking of distributors, and the big fives remain in a situation of closure of old and less profitable factories in 2013. At the same time, high-efficiency factories in Romania, Hungary and Turkey had started to operate to produce cheap and high-value tyres.
Since the beginning of 2000, Eastern Europe has become attractive for foreign investment with the development of infrastructure and decisive administrative and legislative changes
Why is Eastern Europe becoming a hub for the tyre industry? The answer behind must be referenced both within mainland and eastern Europe and the global tyre market… We must respect the goodwill of Eastern European countries for national prosperity. Since the beginning of 2000, Eastern Europe has become attractive for foreign investment with the development of infrastructure and decisive administrative and legislative changes. They have become more transparent for large capitals.

Eastern Europe Annual sales of passengers and light vehicles cover 20% of the European market having a healthy growth of around 5% over the past 10 years. Eastern Europe has more construction activity related to the consumption of commercial tyres. Michelin and Bridgestone started early in Hungary. Nexen in Check Republic and Chinese tyre factory Linlong in Serbia started operations in 2019 and 2020. South Korean Hankook has opened a new factory in Check Republic. The positive development trend will continue in Eastern Europe.
The tyre market in Eastern Europe will potentially remain the hub of the European tyre industry, despite the various negative market effects.
The year 2020 has started with the pandemic effect. The rapid decline in demand for tyres reached 40% in various markets, as well as a 50% drop in new car registrations. Total sales are expected to remain under pressure until mid-2022. In the worst case, the industry will be restructured and the saturation time will cost more. For low efficiency systems, however, the life will not be easy. We can hear plant closures and startups from different countries. Among all these developments, the favorable environment existing in the tyre factories of Eastern Europe will remain the same.
On the other hand, the demand for cost-driven tyres from auto manufacturers will create an atmosphere for low-cost OEM brand manufacturers. New car registration will remain in higher figures in Eastern Europe compared to major European countries. All these effects give the tyre market in Eastern Europe a head start. Therefore, the tyre market in Eastern Europe will potentially remain the hub of the European tyre industry.
EU legislatives will be more deterministic for their further determination of direct foreign investments in Eastern Europe.
The European automotive tyre market generates sales of around $ 20 billion and is expected to grow at a CAGR of 4.5% during the 2019-2024 period before the pandemic. The expansion of the automotive industry so far is a major determinant of the European automotive tyre market which has worked well for Eastern Europe to be a developing region. One country after another has joined the EU in recent years. In addition, their growing expenditure per capita supports the high standard of living of consumers. Each entry shows us that they are more ready for further industrialization, including the tyre industry, and the decline of the tyre market remains limited in Eastern Europe.
Tyre manufacturers such as Trelleborg, Mitas and Apollo-Vredestein, which are already based in Eastern Europe and have facilities, have the potential to catch up with marketing and manufacturing volume opportunities in segments where the Big 5 has been in the past or does not want to participate directly. The impact of Chinese and Korean manufacturers on the tyre industry in Eastern Europe will continue for investments. However, EU legislatives will be more deterministic for their further existence.
Renaud Lapointe Named President Of Metso's Aggregates Division
- By TT News
- October 24, 2026
Metso has named Renaud Lapointe as President of its Aggregates business area and a member of the Metso Leadership Team, with the appointment taking effect on 15 November 2026. He takes over from Markku Simula, whose departure from the company was announced on 11 August 2026.
Lapointe has been with Metso since 2005 and has served as President of the Europe and Central Asia market area since December 2024. Before that, he led the Metso Products business line within the Aggregates business area from 2018 to 2024, and between 2014 and 2017 he was Vice President of the Crusher Systems business line in the same segment. Earlier in his tenure, from 2005 to 2014, he held several leadership positions at Metso in France. Lapointe holds a degree in mechanical engineering from ISTIL in Lyon, France.
Lapointe said, "I am excited to return to the Aggregates business and lead such a highly respected global organisation. With its strong customer relationships, industry-leading solutions and talented team, the business is well positioned for continued success and growth.”
Sami Takaluoma, President and CEO, Metso, said, “Renaud brings experience from both our Aggregates business and our market area organisation. This combination will support the continued development of our offering and close cooperation with customers. I look forward to welcoming him to the Metso Leadership Team.”
JK Tyre Eyes Double-Digit Growth Despite Cost Pressures Testing Margins
- By Nilesh Wadhwa
- October 23, 2026
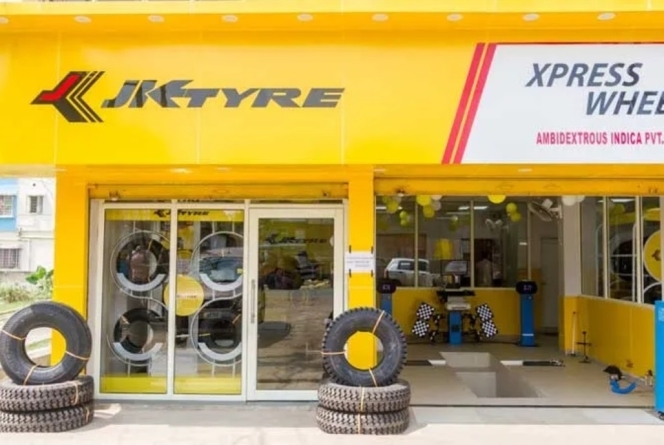
JK Tyre & Industries is targeting double-digit growth in FY2027, supported by healthy commercial vehicle demand, sustained OEM traction and a growing market for premium passenger car tyres. However, rising raw material costs and elevated freight rates continue to pressure margins, prompting the company to pursue further price increases and operational efficiencies.
Anshuman Singhania, Managing Director, JK Tyre & Industries, expects demand to remain stable through the second half of FY2027, with commercial vehicle tyre sales projected to record double-digit growth for the full year. While passenger vehicle demand could moderate slightly, healthy OEM order books and replacement market traction are expected to support the industry's growth momentum.
“We are very optimistic going ahead that demand would be quite stable,” Singhania said during the post-results media interaction, adding that the positive momentum was expected to continue through the third and fourth quarters.
Record Revenue in Q2 FY2027
JK Tyre reported its highest-ever consolidated quarterly revenue of INR 48.5 billion in Q2 FY2027, up 20 percent year-on-year (YoY). Consolidated EBITDA rose 28 percent sequentially to INR 3.43 billion, with an EBITDA margin of 7.1 percent. Profit after tax stood at INR 600 million.
Domestic sales grew 32 percent YoY, led by a 65 percent increase in OEM sales following the implementation of GST 2.0. Exports also gained momentum, rising 14 percent sequentially despite geopolitical uncertainties and challenging international market conditions.
Growth was broad-based across product segments. OEM volumes increased 76 percent in truck and bus radial (TBR) tyres and 35 percent in passenger car radial (PCR) tyres. The tubeless tyre portfolio grew 25 percent YoY, against estimated industry growth of 10 percent, while tipper tyre sales increased 20 percent compared with industry growth of 11–12 percent.
Sales in the two- and three-wheeler category rose approximately 85 percent YoY, driven primarily by scooters. Replacement sales increased 20 percent, reflecting continued traction across channels.
Despite the revenue growth, profitability remains under pressure as input and logistics costs rise faster than they can be recovered through pricing.
Raw Material Costs and Freight Weigh on Margins
JK Tyre's raw material basket increased approximately 9 percent sequentially in Q2, with the cumulative increase over the preceding six months estimated at around 30 percent. Singhania expects a further 4–5 percent increase in the basket during Q3.
Elevated container freight rates have added to the pressure, with increases across geographies affecting exports and shipments from India. Higher petrol and diesel prices have also contributed to rising logistics costs.
The company is seeking to offset these pressures through price increases, manufacturing efficiencies and a richer product mix. However, the timing of margin recovery will depend on the extent to which higher costs can be passed on in a price-sensitive market.
Further Price Hikes Planned
JK Tyre increased prices by approximately 4–5 percent in Q1 and a further 7 percent sequentially in Q2, taking the cumulative increase during the first half of FY2027 to around 11–12 percent. The company intends to implement another 4–5 percent increase in Q3, subject to market conditions.
“The raw material increase is putting a lot of pressure on margins. But we are steadily increasing our prices to pass through,” Singhania said.
OEM pricing is partly linked to input cost indices, allowing some increases to be recovered through contractual adjustments. In the replacement market, price increases have been implemented more gradually over the past two quarters, with further adjustments expected.
Singhania acknowledged that the industry typically experiences a lag between cost escalation and full price recovery. While the company expects margins to improve through better OEM mix, price indexation and operational efficiencies, it has not quantified the anticipated improvement.
Premium Tyres Gain Share
JK Tyre is increasing its focus on premium passenger car tyres, particularly those with rim sizes of 16 inches and above. The company said the share of these tyres in its passenger car OEM mix increased to approximately 40 percent in H1 FY2027, compared with 35 percent in FY2026. These sizes account for around 27 percent of its overall mix, including the aftermarket.
The shift towards larger rim sizes is being supported by new vehicle launches and wider adoption across passenger vehicle categories. JK Tyre has secured 10 OEM approvals during the year, eight of which involve models in the 16-inch-and-above category. These include the Maruti Suzuki Brezza, Mahindra Thar, Renault Duster and Tecton, and MG Tomahawk, as cited during the media interaction.
“The market is growing, but our market is growing at a faster rate,” Singhania said, highlighting the opportunity presented by new OEM programmes and rising demand for larger rim sizes.
The company expects this segment to support product realisation and improve its sales mix, with additional capacity helping it meet evolving OEM requirements.
Expansion Continues as Exports Offer Headroom
JK Tyre is proceeding with its INR 11.3 billion capacity expansion programme, which Singhania confirmed would not be deferred. The previously announced INR 50 billion capital expenditure programme is also progressing through its initial phase.
The investments are intended to support domestic demand and create capacity for export opportunities. JK Tyre reported encouraging demand from Latin America and Africa, while some markets in Asia and Europe softened amid geopolitical uncertainty.
The company plans to continue serving established markets across Latin America, the Middle East, Southeast Asia and Africa, alongside a limited presence in Europe, while prioritising domestic OEM and replacement requirements.
For the second half of FY2027, JK Tyre expects commercial vehicle demand to remain supportive and is targeting double-digit growth in the segment for the full year. Strong OEM order books, replacement demand and the increasing contribution of premium tyres are expected to underpin growth. The key challenge will be translating higher volumes into sustainable profitability as the company navigates raw material inflation, freight costs and the lag in price recovery.
ATD Names Michael Broderick Interim President As Ira Silver Departs
- By TT News
- October 23, 2026
American Tire Distributors (ATD), a leading independent supplier in the replacement tyre industry, has appointed Michael Broderick as Interim President, effective immediately. He takes over from Ira B Silver. ATD also announced that the company and Silver have parted ways.
Broderick, who currently sits on ATD's Board of Directors and brings extensive automotive aftermarket experience, will guide the leadership transition. Meanwhile, the Board is conducting a comprehensive search for a permanent Chief Executive Officer, evaluating both internal and external candidates.
ATD continues to hold a significant position in the North American tyre market, supported by a broad distribution network, longstanding customer relationships and a diverse portfolio of manufacturer and proprietary brands. During 2026, the company eliminated more than USD 170 million in structural costs, reinvesting a portion of the savings, while shareholders have backed further investment in the national distribution network to strengthen market position and operating performance.
Philippe Gilbert, Chairman of the Board of Directors of ATD, said, “ATD has made important progress sharpening our focus on our core tyre distribution business, improving operational efficiency and delivering outstanding service and value to our customers and partners. As we look to accelerate these efforts, we determined that now is the right time to initiate a leadership transition. Mike brings substantial experience leading complex automotive businesses, and we are pleased that he is stepping in as Interim President to help us during this transition period. He will be supported by the ATD management team, which has played a central role in the Company's operational transformation, providing continuity of leadership across its distribution operations and strategic initiatives. On behalf of the Board, I would like to thank Ira for his leadership and contributions to help move the Company forward during a critical time.”
Broderick said, “I’m excited to step in and work alongside ATD’s team of talented associates as we focus on enhancing our network to provide customers with high-quality products and unparalleled service. As a member of ATD’s Board and over a decade of working with ATD as a customer, I’ve witnessed firsthand the strength of the Company’s robust national distribution network, deep customer and manufacturer relationships and long-held commitment to exceptional service. I look forward to advancing our efforts to strengthen our core tyre distribution business and build a stronger, more efficient company.”
Charting A New Course
- By Nilesh Wadhwa
- October 22, 2026
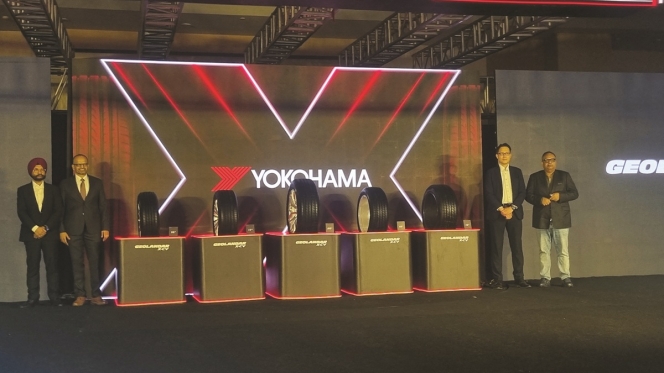
Yokohama India plans to enter the two-wheeler tyre market for the first time, with the first set of products due by the end of next year — making India the first country globally to get two-wheeler tyres from the Japanese tyremaker. The move, confirmed by Managing Director and CEO Harinder Singh, coincides with the launch of the GEOLANDAR X-CV range, extending Yokohama’s flagship SUV tyre technology to smaller wheel sizes for India’s booming crossover segment.
India’s premium tyre market continues to reward companies that combine global technology with local agility. Yokohama India, already one of the country’s fastest-growing premium players, looks to tap into India’s SUV and premiumisation push, bringing global products but in a customised avatar for the domestic market.
On the other hand, India is set to become the first country in the world for Yokohama, where it will introduce two-wheeler tyres.
In an interaction with Tyre Trends, Harinder Singh, Managing Director and CEO, Yokohama India, confirmed that the company is actively working towards entering the two-wheeler tyre segment, with the first products targeted for launch by the end of next year.
“The move will require fresh capital investment and will initially focus on the premium category before expanding into mass-market offerings, along with supporting the growing Yokohama Club Network,” revealed Singh.
This development sits alongside the recent unveiling of the GEOLANDAR X-CV range, a significant extension of Yokohama’s global flagship SUV technology into India’s rapidly expanding crossover and premium SUV segment.
TWO-WHEELER ENTRY SIGNALS BROADER AMBITION
Responding to a query on the company’s plans to address the whitespace in its portfolio, Singh said, “We are actively looking to support the two-wheeler business. By the end of next year, hopefully we should be having the two-wheeler tyres also.”
It is important to note that at present Yokohama India has zero presence in the two-wheeler space. The initial thought is to begin with tyres in the premium segment and then ‘take a trickle in’ towards mass-market products.
“This is primarily to service and support our all Yokohama club networks. And we plan to sell through them. That’s the objective,” said Singh.
The decision reflects both opportunity and necessity. India’s two-wheeler market remains vast and premium tyres are gaining share as riders seek better handling, durability and safety. By channelling the new products through its branded retail network, Yokohama intends to maintain the premium experience that has defined its passenger-car strategy.
GEOLANDAR X-CV BRINGS FLAGSHIP TECHNOLOGY TO A WIDER AUDIENCE
The immediate focus, however, remains the passenger-car radial business and the newly launched GEOLANDAR X-CV. Originally engineered for luxury SUVs with wheel sizes above 18 inches, the technology has been extended downwards to 16 inches, creating what the company describes as India’s most extensive dedicated tyre range for crossover and premium SUVs. Yokohama India has planned around multiple variations spanning 16 to 20 inches.
The tyre incorporates Micro Silica technology for enhanced wet-road grip and reduced rolling resistance, an optimised asymmetric tread design with specialised inner and outer shoulder blocks, four wide circumferential grooves for water evacuation, proprietary 2D–3D Combination Sipes for improved wet traction and even wear and 5-Pitch Variation Technology to minimise pattern noise.
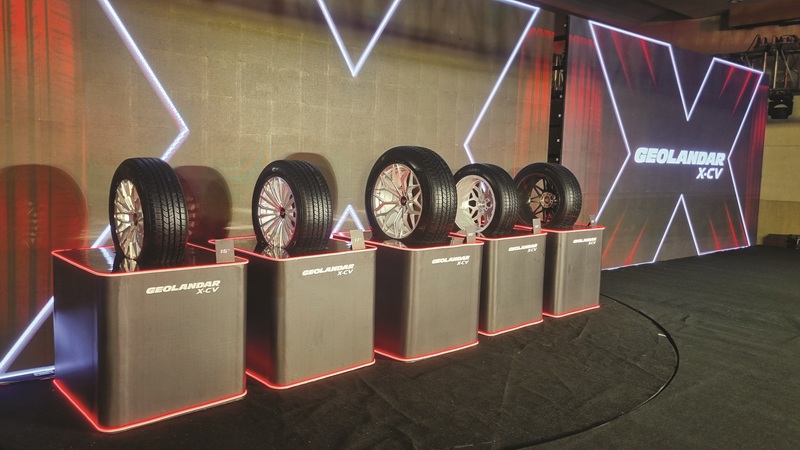
It uses reinforced two-ply sidewall construction and a full nylon cover to deliver durability and high-speed stability required for Indian conditions. Critically, the range is EV-compatible, engineered to handle higher vehicle weights and the instant torque characteristics of electric vehicles while remaining equally effective on internal-combustion and hybrid platforms.
Nitin Mantri, Member of the Board and Senior Managing Officer & Co-COO of Yokohama Rubber Co and Chairman of Yokohama India, framed the launch in strategic terms: “India continues to be one of Yokohama’s most strategic markets globally. Our continued investments in manufacturing, technology and premium product development reflects our confidence in the country’s long-term growth. The launch of GEOLANDAR X-CV reinforces our commitment to bringing globally proven innovations closer to Indian customers while strengthening Yokohama India’s position as one of the country’s leading premium tyre manufacturers.”
Singh added: “The crossover SUV segment is growing rapidly and the road infrastructure improving, now motorists are seeking a balance of safety, comfort, quietness and long-lasting performance. With the GEOLANDAR X-CV, we’re bringing flagship premium tyre technology to delight a wider base of crossover SUV owners.”
CAPACITY RUNNING NEAR FULL, EXPANSION ALREADY MAPPED
Yokohama India’s current installed capacity stands at approximately 4.5 million units a year. The capacity utilisation is already high. “We are almost full,” Singh noted.
Of the 4.5 million, roughly four million tyres serve the domestic aftermarket, with the modest surplus supporting European export requirements of the parent company. The Vizag plant has been designed with further phases in mind. “The plant is ready to be going for the next phase also. So as and when the requirement is, we will expand it,” averred Singh without giving out exact details.
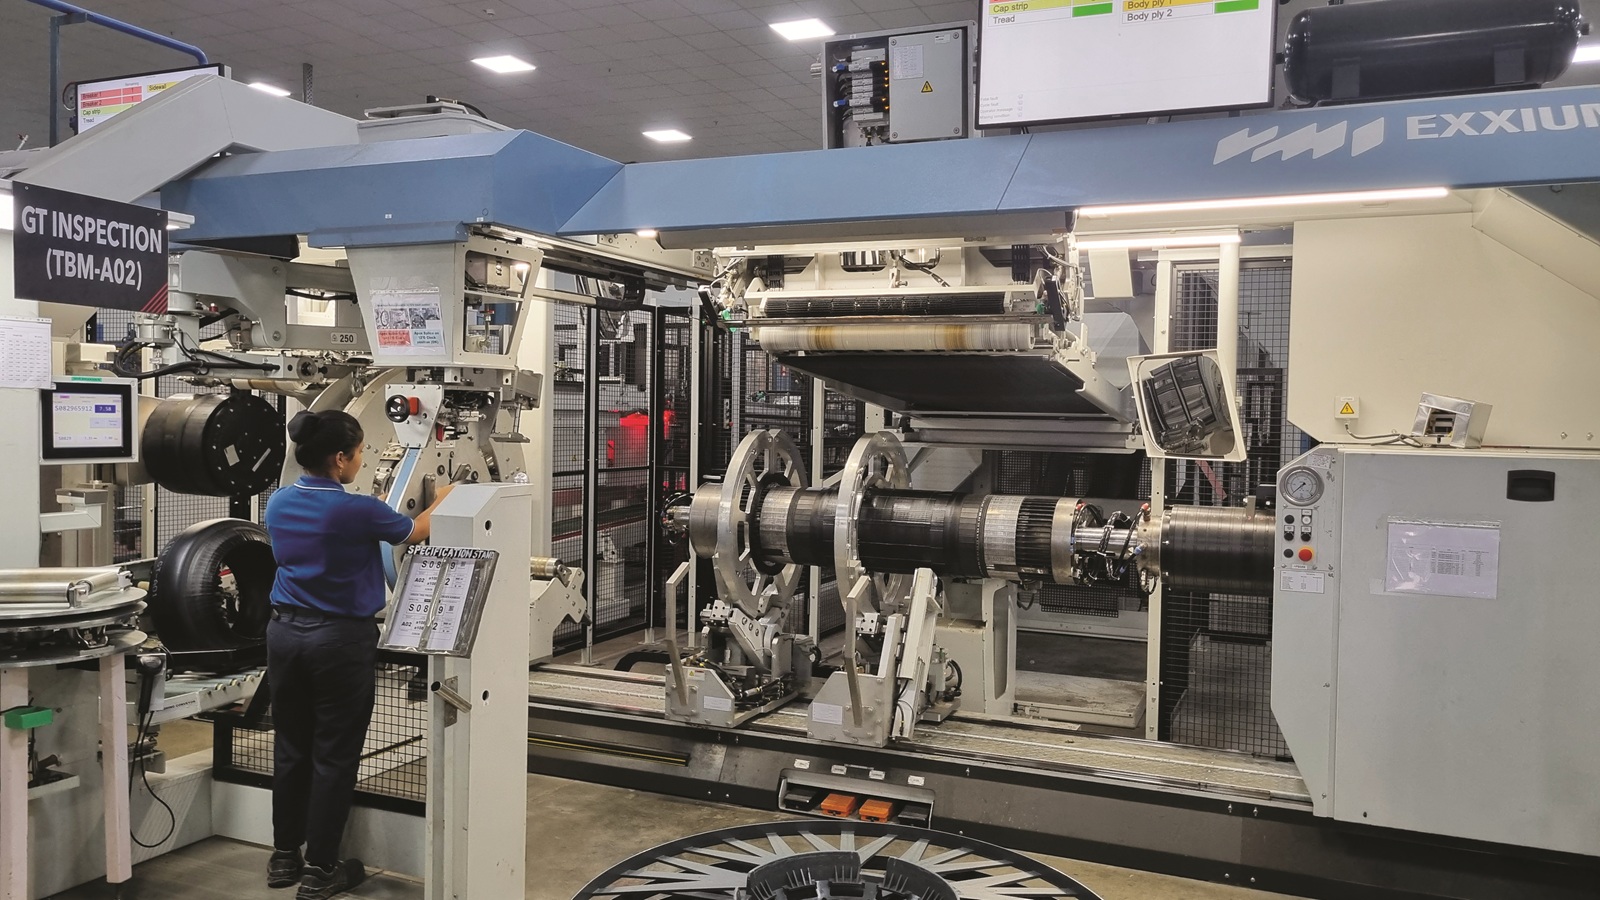 Mantri elaborated on the flexible manufacturing philosophy. Buildings and long-lead equipment are already in place; additional machines will be added incrementally as demand thresholds are crossed.
The existing footprint can take capacity from 4.5 million to 6.3 million units. Beyond that, the parent company has demonstrated consistent willingness to invest. Cumulative investment in India across the Yokohama Group is already substantial, with the Vizag facility alone accounting for more than INR 30 billion in recent years and overall group investment estimated in the range of USD 700–800 million. An Odisha plant focused on off-the-road tyres is also under construction.
AFTERMARKET REMAINS THE CORE, BUT OEM SHARE IS SET TO RISE
For Yokohama India, aftermarket sales in the passenger vehicle segment still account for around 95 percent of its revenue. The company has roughly 3,000 channel partners and aims to reach 4,500 within three to four years, with particular emphasis on Tier-3 and Tier-4 towns.
A key pillar is the Yokohama Club Network of branded retail stores that deliver a premium customer experience, including a five-year worry-free warranty. “In tyre industry, you know, 80–85 percent of the customers sale happens with the influence of the channel partner. When a customer walks into those stores, he gets that premium experience,” noted Singh.
At present, for Yokohama India, the passenger vehicle OEM business contributes only about two percent, limited largely to Maruti Suzuki India. The roadmap is to raise this to 10 percent within five years, and potentially towards 10–20 percent over a longer horizon. “Indian OEMs are going to be an important part in our OE strategy,” Singh confirmed.
Adding to that, Mantri said that OEM development cycles are lengthy, typically three to four years, but multiple proposals are already under discussion. “Working hand in hand with OEMs allows us to be kind of even more successful than we are as we go forward,” he said.
LOCAL OWNERSHIP MEETS GLOBAL STANDARDS
One of Yokohama India’s distinctive features is the degree of local management autonomy. “India was the first place where Yokohama gave complete ownership to the local management. There was no Japanese chairman,” Mantri explained.
The experiment, begun in 2020, has married Japanese technology and quality culture with ‘Indian Jugaad, Indian innovation, Indian kind of hunger for growth’. The result, he said, has been ‘a wonderful recipe’.
Product strategy follows a similar hybrid logic. The Earth-1 range was designed specifically for India. Newer products such as the GEOLANDAR X-CV start from global platforms but are tuned in compound and construction for Indian roads and driving conditions.
Replying on the company’s localisation levels, Mantri said that “sourcing remains pragmatic. Yokohama seeks the highest quality at the best price, whether from India or Southeast Asia, rather than pursuing localisation for its own sake.”
Growth over the past five years has averaged 18 percent CAGR, a momentum the leadership is determined to sustain. Market share in the premium passenger-car radial segment is estimated at around 10 percent. The company continues to prioritise 16-inch and larger sizes while systematically filling remaining white spaces in the portfolio.
LOOKING BEYOND THE IMMEDIATE HORIZON
It is no secret that when it comes to digitalisation, consumers in India are exposed and are amongst the fastest adopters of the latest trends, be it product-as-a-service, online purchase or service on hire.
Many quick commerce platforms and tyre makers have taken the online route to directly engage and sell their products to the end-consumer, but for Yokohama India, online tyre sale holds little appeal.
“We are not into online business. That’s a no from our side,” Singh clarified. The preference remains for customers to experience the product and fitting process in a branded store. Marketing support is deliberately hyperlocal and digital rather than big-ticket sporting sponsorships.
As road infrastructure improves and motorists undertake longer journeys, demand is shifting towards on-road focused tyres, a trend the GEOLANDAR X-CV is positioned to capture. All-terrain products will continue for genuine off-road use, but the volume opportunity lies in the growing crossover segment. Continuous upgrades across the rest of the portfolio, including further evolution of the Earth-1 range, are already planned.
For Yokohama India, the strategy is clear – offer the best experience to Indian consumers, by introducing its globally proven products to the market without compromises, but yet in an Indian avatar. On the other hand, the company is also gearing up to enter new segment to further cater to customers in the premium two-wheeler space.
QUALITY OVER FORCED LOCALISATION
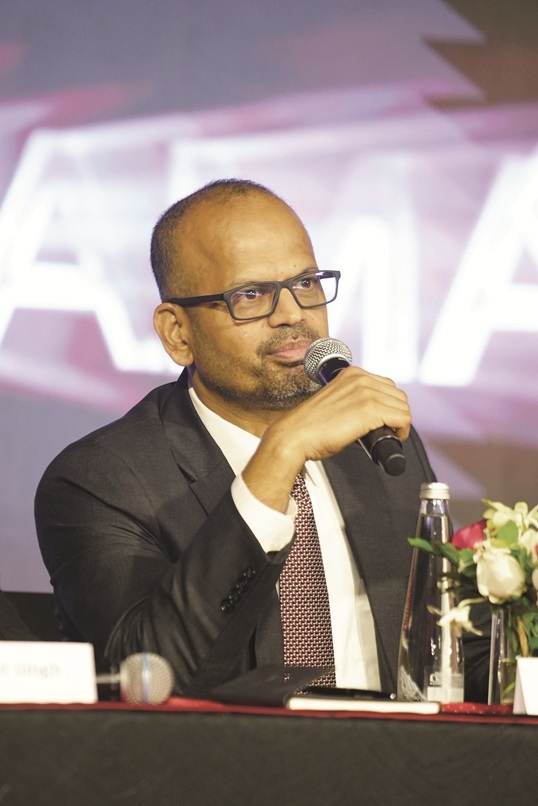
Nitin Mantri, Member of the Board And Senior Managing Officer & Co-COO, Yokohama Rubber Co and Chairman, Yokohama India, shares his thoughts on the company’s future plans, production capacity, localisation and network expansion.
How significant is India within Yokohama’s global strategy?
India is one of our most strategic markets. It was the first place where we gave complete ownership to local management with no Japanese chairman. Combining Japanese technology and quality culture with Indian innovation and growth hunger has created a powerful combination.
India is already your fourth-largest market. Can it climb higher?
Passenger-car penetration remains much lower than in US, Japan or China. That gives us runway, but catching the very largest markets will still be challenging given the vehicles-per-person difference.
Why has OEM share stayed so low?
We were simply short of capacity. Aftermarket demand absorbed almost everything we could make. With new capacity coming on stream, we are deliberately changing that mix. We aim for 10–20 percent OEM over time. Development cycles with OEMs take three to four years, so results will appear gradually.
How do you approach product development for India?
Some products, such as Earth-1, were designed purely for India. For others, we take global platforms and carefully retune the compound and construction for Indian roads and conditions. The goal is global technology that feels native here.
What is the philosophy behind capacity expansion?
We design factories for flexibility and minimal waste. Long-lead buildings and equipment are installed first. Additional machines are added only when demand thresholds are crossed. Our current footprint can take us from 4.5 million to 6.3 million units. Beyond that, the parent company has consistently shown willingness to invest.
How do you view localisation of raw materials?
We source for the best quality and value, whether from India or elsewhere. Our specifications remain identical regardless of origin. We do not force localisation if it compromises quality or cost.
Are your tyres ready for the rise of electric vehicles?
Yes. Features such as specialised silica compounds that deliver low rolling resistance, higher load capacity and reduced noise work equally well on battery-electric, hybrid and conventional vehicles. That flexibility is deliberate.
What keeps you focused on the aftermarket network?
Channel partners still influence 80–85 percent of tyre purchases. Expanding from 3,000 to 4,500 partners, with particular attention to Tier-3 & Tier-4 towns, and strengthening the Yokohama Club branded stores remain central to our growth. n
Comments (0)
ADD COMMENT