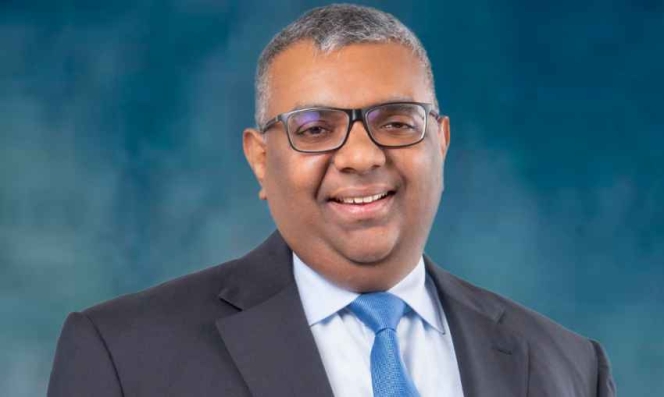
As local consumption is limited, the export business plays a vital role in Sri Lanka’s economic growth. However, it is high time for the country to look beyond their traditional products and markets and push industry-friendly policies, infrastructure development and attract foreign investors, and a larger stake is dependent on vision and implementations of strategic plans by Sri Lanka Export Development Board (EBD). Prabhash Subasinghe, Chairman of the Board, said EDB will focus on support existing exporters to bolster their exports, bring new products in the export baskets, look into new export markets, increase capacity building and attracts foreign investment through industry-friendly policies and incentives. Excerpts from an interview
How important is export business for Sri Lanka's overall economy?
The Export business is an important segment for the sustainable growth of the economy of Sri Lanka and creates many employment opportunities. The export market of Sri Lanka is vast where the traditional exports of tea, rubber and coconut still play a significant role in bringing in export revenue to the country not forgetting the other major exports- apparel, spices and gemstones. Even though Sri Lanka does not produce in abundance the essential items, the country needs but does it in a smaller scale yet going towards few quantities of imports too, which involves outward remittance in foreign currency. Also, the size of the population limits the capacity of firms to achieve economies of large-scale production by solely catering to the local market thereby, export business is very vital for Sri Lanka's overall economy.
What are the country's strengths in the export business?
‘Made in Sri Lanka’ is synonymous worldwide with the values of high quality, reliability, social and environmental accountability. Sri Lankan brands that are increasingly associated with high quality and ethical manufacturing practices have opened up new avenues in the global arena. Ethical brands Sri Lanka apparel goes hand in hand, and this focus on sustainability has proven a worthy investment in the future of the industry. Apparel is one of the world's leading proponents of 'Ethical Business and Manufacturing Practices' for the Global Fashion and Apparel Sourcing Business. It earns its distinction of being among the very few industry bodies that have brought about a transformation in the way businesses are run, with responsibility, conscience and care.
Value addition and building Sri Lankan brands in the tea industry require a high level of investment and a commitment to quality in product and process. Sri Lanka was also the first to achieve the "Ozone Friendly Tea." World-renowned Sri Lankan tea brands are intensely involved in emphasising sustainable development to become a valuable partner in developing a social, corporate and environmentally responsible product to its consumers.
Young, educated & productive, talented and highly trainable workforce in Sri Lanka proves to be one of the best in the region. Availability of human resources with proficiency in English and ICT knowledge to meet the needs of the present industry demand is a strength of the country.
Exports of services such as ICT, wellness tourism, financial services, construction & other professional services have grown significantly in the last decade. These sectors have proven their ability to diversify their export market destinations.
The availability of natural raw materials in industries such as rubber, spices, especially cinnamon and pepper, coconut, Gems etc play a vital role in the national economy with more significant value addition to the necessary products.
Why should foreign companies invest in Sri Lanka?
Sri Lanka is situated strategically at the crossroads of major shipping routes to South Asia, the Far East and the continents of Europe and America, making the country a convenient port of call for shipping lines and airfreight services. Further, Sri Lanka's proximity to the Indian sub-continent positions the country as a gateway to a market of 1.3 billion people. These factors have combined to generate keen interest in the country's logistics sector, as well as from manufacturers looking for opportunities in the South Asian region.
Further, Sri Lanka has entered into 28 Bilateral Investment Promotion and Protection Treaties (BITs) so far, protecting foreign investments within the country. There is a wide range of incentives offered to attract investments which includes; enhanced capital allowances, concessionary corporate income tax across many sectors including SMEs, tax concession for R & D activities, CESS exemptions for the importation of Capital Goods, importation of raw materials & for tourism projects, VAT Exemptions/Deferments & Custom Duty Exemptions for export-related activities and exemptions also offered under Hub Regulation. Besides, as per Strategic Development Projects Act No. 14 of BOI, exemptions are granted for projects which is in the national interest and which is likely to bring economic and social benefit to the country and which is also expected to change the landscape of the country primarily.
Furthermore, the availability of quality natural raw materials, relative ease of doing business, and talented highly trainable workforce in Sri Lanka also play a vital role in attracting the interest of investors to invest in the country.
How do you evaluate the impact of Covid19 on the country's economy, and especially on exports? How are you coping with it?
Global economy is forecasted to contract by 3 % in 2020 sharply, and there is no accurate prediction as to when the effects will reduce. Sri Lanka is no exception to the impact of the pandemic and exports both merchandise and services which stood at US$ 16.14 billion in 2019. In May, Sri Lanka's merchandise exports decreased by 37% to USD 602.4 Mn. In the first 5 months, exports earnings fell by 28.7 % to USD 3456 Mn from the corresponding period of last year. Considering the unprecedented disruption to the global economy and trade due to the COVID-19 pandemic, the Sri Lanka Export Development Board has reduced its 2020 exports forecast from US $ 18.5 billion to US$10.75 billion by about 42%. As per the revised target, EDB forecasts $ 7.53 billion in merchandise exports and $ 3.21 billion from service exports in 2020.
Despite the gloomy global situation, we are confident that the export sector will be the first to recover, whilst other foreign exchange inflows such as tourism and worker remittances will take time to bounce back in the economic revival post COVID -19.
The EDB officers have been working tirelessly to help the exporters by setting up a helpline to facilitate to assist in the present situation, publishing updates on the EDB website with the government directives through circulars/letters/guidelines etc., liaising and intervening on behalf of the exporters with all the higher authorities , connecting exporters with the foreign missions and ambassadors to find new opportunities, facilitating with curfew passes abiding with health guidelines issued and implemented by the government and communicating news to all Sri Lankans and overseas markets by taking initiatives in publishing various news articles pertaining to export-related services to continue their businesses.
During the early stages of the pandemic, our apparel sector was affected badly. However, we now experience a reasonably positive trend, especially with the manufacturing of PPE, where the sector has now attracted a considerable amount of orders. Therefore, we believe that the decline expected for apparel exports at the beginning of the year may be less than that as the sector is going to experience a strong revival with orders in hand for PPEs and EDB is constantly on the lookout for such specific opportunities that Sri Lanka could maximise on.
We firmly believe that there is a great opportunity to establish strong FTAs with China etc., to engage in new export opportunities taking the crisis situation into consideration.
Do you think now EDB needs to re-strategies its business plans to boost exports?
The National Policy Framework "Vistas of Prosperity and Splendour" underlines the key points of achieving economic growth of 6.5 percent or higher, per capita income exceeding USD 6,500 and maintaining the rate of unemployment at less than 4 percent. Exports are very important to achieve this goal.
The Export Development Board (EDB), the country's apex Trade Promotion Organization (TPO), has revised its strategic plan with a focus on addressing what the EDB should do during and the post Covid–19 period and how it should operate to fulfill its mandated role having aligned with the National Policy Framework and National Export Strategy. Accordingly, EDB will adopt and implement 5 Strategic Pillars in the immediate, medium and long term. This includes;
-
Support existing exporters to bolster their exports – This strategy aims to create a business enabling environment for exporters to be competitive in the international market
-
Promote new exports from Sri Lanka to transform the current Sri Lanka export basket - This objective focuses on diversifying current export basket by introducing value addition, innovation and invention
-
Diversify into new markets - This objective supports to diversify current export markets by reducing over dependency on few export markets and reduce the dependency of fewer sourcing destinations
-
Enhance capacity building - This aims to enhance exporter capacities in developing their industries
-
Generate export-led foreign investment into the country - This objective aims to attract export-led FDIs that will ultimately increase production, productivity and new technology adaptation.
For each of the five strategic pillars, immediate, medium and long-term strategies are identified. Based on that, EDB is in the process of finalising its action plan for the year 2020 and 2021. Implementation of the new actions is expected to help revitalise the export industry that's been hit by the pandemic.
Do you think there is a need to diversify export baskets and markets?
Currently Sri Lanka export engines rely on a blend of traditional industries and growing service sector. It is vital to empower the emergence of champions beyond the traditional export industries of apparel, tea, gems & jewellery and rubber.
Sri Lanka has been over depending on few markets and has been catering to these markets over the past decades. Around 60% of the Sri Lankan exports have been concentrated in the European Union and North American regions showing lower markets
Diversification over Asia, CIS, Africa, Latin America and Oceania regions. We must now pursue other markets as well.
Connecting Asia to Europe and Africa, Sri Lanka is well-positioned to participate fully in the global production networks and export to billions of consumers, both regionally and beyond.
Sri Lankan companies that are facing difficulties should be willing to diversify to new markets, and it is high time to make that change happening. Further, companies should also look for new sourcing destinations in future to continue our production lines uninterrupted.
EDB has been focusing on identifying various measures to diversify our export revenue streams. Various discussion and dialogues were conducted internally and with the multiple stakeholders, and this information are being disseminated with the relevant parties. We encourage exporters to re-visit their product portfolio and to identify new potential products in the short, medium and long term. As a developing nation, we always encourage new investments with a focus on emerging potential areas in agriculture, industrial and service segments. EDB is leading this effort along with all Sri Lankan Missions Overseas.
Further, EDB and BOI work in collaboration to attract and increase investments with a focus on emerging potential areas in agriculture, industrial and service segments targeting key products to enhance the export basket, namely; automotive parts (seals, gaskets, hoses, wiper blades, belts, Conveyor belts), apparel (technical apparel & PPEs), electrical & electronic components (semiconductors, Transformers PCB, panel boards' Insulated wires & cable, Switches, plugs & sockets etc), ICT (Software design & development), Mineral-based products (Graphene and related products) and Food Processing sectors.
To create an export hub and attract investors, a country needs good infrastructure, skilled workers, smooth supply chain and industry-friendly policies. How do you see these factors, and what are your efforts to improve them?
Good infrastructure, trainable workforce and business-friendly ecosystem are very vital components in making Sri Lanka, an export hub.
Sri Lanka's geographical location, dynamic business environment, dependable logistics and resilient human resources have become invaluable assets. Realising this, our government is committed to creating an enabling environment to strengthen the competitiveness, which is a key driver to achieve inclusive and sustainable growth of Sri Lankan exports.
Further, EDB provides its fullest support to exporters to move up in the value chain. Some of them include; Review the supply chains and go for shorter regional supply chain, Establish linkages with cross-functional institutions (ICTA/SLINTEC/Universities), Trade support to assist new exporters in selling their products in the e-marketplace, Identify opportunities in major Global value chains and encourage exporters to diversify into component manufacturing, SMEs development aiming at the Export Market, Assistance for value addition, innovation and inventions and expansion of existing exporter capacity, Facilitate to upgrade the quality of exports through advanced technology (certifications/ standards) in identified new products etc.
In addition, Young, educated & productive, talented and highly trainable workforce in Sri Lanka proves to be one of the best in the region. EDB implement various capacity-building programmes to enhance the know-how of the export community.
For the long term, what is your vision?
To develop stronger Sri Lankan businesses to access global opportunities enhancing foreign exchange earnings while creating employment for our people.
As a surviving member of the ‘baby boomer’ generation that commenced with the rapid economic growth following the World War II, I think we are, in a broad sense, privileged to have witnessed and experienced the happenings and consequences of about 50 years in the 20th Century and about 30 years in the 21st Century. When contemplating on the term literacy and its traditional meaning of being able to read and write from an educational perspective, I feel it fitting to cite a few real-life cases, from way back, which make me to wonder whether the above interpretation of literacy is all encompassing.
a) My maternal grandmother, who was born in 1900, did not know reading or writing, a typical feature about the female folk in that era, especially in the remote villages. Despite this apparent handicap, she successfully managed the day-to-day administration of the paddy fields and the rubber plantation, including finances, and raised three children to become worthy human beings.
b) Then there were these three young people who had migrated to Colombo with minimal formal education and started their business in humble ways to become well recognised icons of international fame in the healthcare, confectionary and rubber footwear and tyres, respectively, the latter being related to my own core field, the rubber industry.
c) Last but not the least, the late Martin Wickremasinghe, born in the late 19th century, who attended school only up to the 7th standard, wrote hundreds of books on diverse subjects such as history, anthropology, sociology, religion and literature and several novels (some of which were translated to several languages), which rightfully recognised him as a well-respected scholar and the greatest writer in Sri Lanka.
While it may be futile to compare apples with oranges, I feel that literacy has a utilitarian perspective, which can change with the social context and the circumstances. With my manufacturing background, I see a close parallel of literacy and quality. Out of the hundreds of definitions available of the latter, ‘fitness for use and the level to which requirements are fulfilled’ is applicable to literacy as well.
When going through the available information on the subject, it is noted that ‘literate’ can be traced back to the early 15th century from the Latin word literatus, meaning learned, educated and lettered. Initially, literate meant someone who was well educated, learned and acquainted with literature, and over time, as basic schooling became more widespread, the word was adapted to describe the foundational skill of reading and writing. The Oxford Advanced Learner’s Dictionary defines literacy primarily as ‘the ability to read and write’. Two core definitions for the term are identified as Basic Literacy, the fundamental ability to read and write, and Specialised Literacy, the competence, knowledge or skill in a specific subject area in which common modern applications include:
a) Computer literacy: The ability to use computers effectively.
b) Financial literacy: Understanding and effectively managing personal finances.
c) Health literacy: The capacity to obtain, process and understand basic health information and services.
It could be inferred that we, the ‘baby boomers’, currently at an advanced stage in life, cannot do without the above basic literacies, and as a minimum, the routine health check such as blood sugar, blood pressure, LDL and HDL etc. to survive and lead active lives.
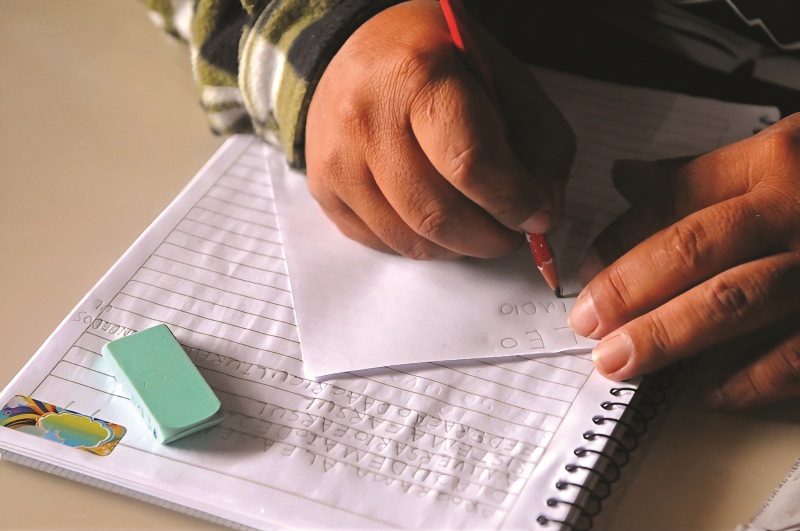
It is said that writing originated primarily out of economic necessity as the early agricultural societies grew and needed to track goods, taxes and trade. The evolution of writing from rudimentary clay tokens in to the world’s first independent writing systems in Mesopotamia, Egypt, China and Mesoamerica around 3200 BC to 3000 BC is a story that requires a deeper elucidation at a different forum.
Literacy is considered as one of the most important foundations of civilisation and has played a crucial role in human survival and existence both evolutionary and historically. However, instead of going into a deliberation of these foundational perspectives, I intend to offer some of my personal insights and recollections on this important subject over the past 60-plus years. I can recollect how at preschool stage, we were initiated into the basics of reading and writing using slates and slate pencils (made out of a silicious material) and the ‘black boards’ in the class room where chalk was used for writing. Literacy mainly meant the ability to read and write and, in later classes, in performing basic arithmetic. In schools and workplace, literacy was closely connected to formal education and subject knowledge. A literate person was one who could understand written communications, reads books and newspapers, write letters and maintain records and perform effectively in society. It was directly connected to social respectability and economic progress.
Literacy in English was considered as a rare virtue in countries which were under the British colonial rule. It was confined only to a few ‘high level’ schools in Colombo and in some major towns. Hailing from a rural background and having attended a small primary school in a remote town, I have first-hand experience of the panic and inferiority when I started secondary education in Colombo. This was especially true when we started studying for the Government (Ordinary Level Exams) in the science stream which was all in English. It was a struggle to get adapted and face the challenge, which I would say, I managed fairly well.
In those days, literacy was essentially confined to formal education and subject knowledge. Students were expected to memorise facts, understand texts and reproduce the information during the examinations. Books and libraries were the main sources of knowledge. Teachers were well recognised and respected as the primary sources of knowledge. And learning was generally a disciplined and structured process. And information, though limited, was relatively organised. I do not consider this as a deficiency or a weakness at all, because it fitted well with the societal and business expectations of those days.
I can well remember the day of my first interview seeking a job, which happened to be in the rubber industry. Instead of asking about isoprene or how the RSS (Ribbed Smoked Sheet) is made, although I managed to cram some information about the latter, I was asked about Ohm’s Law and how steel is made from iron ore. I was lucky because in our Advanced Level class, we had studied the above, and this paved way for a lifelong career in the rubber industry.
Literacy seems to be directly proportional to the rate of percolation or trickling down of the technologies to countries in our part of the world, and this was a rather slow process until the early eighties. However, mankind is evolutionary geared for ‘adaptive radiation’, which in modern jargon can be interpreted as how quickly we learn and get used to the new situations and contingencies as we meet new frontiers. According to the modern theories of cognitive learning, we acquire new knowledge through assimilation of new concepts (schemas) or by accommodation of incoming concepts into our existing knowledge. As an example, I can relate with my personal experience how my literacy in rubber technology evolved, starting as young trainee with very little knowledge on rubber. With the rapid development of science, technology and globalisation and artificial intelligence, the meaning of literacy has expanded beyond the traditional horizons.
In contrast to the scenario of over 50 years ago, today’s literacy has grown to include cultural awareness, ethical understanding, workplace competence, computer literacy, digital communication and the ability to manage continually increasing volumes of information; some of them are very often recurring and sometimes redundant. Some key diversions are shown as follows:
a) Educational and subject literacy: While mathematical and scientific literacy, language proficiency and analytical thinking is essential, they go beyond memorising facts to effective application of the knowledge.
b) Cultural literacy: This has become increasingly important in this era of extending globalisation for respectful understanding and effective communications. This also includes awareness of history, religion, social values and traditions, which lamentably is declining amongst the younger generations.
c) Ethical literacy: This simply means the ability to distinguish the right and the wrong, social responsibility and taking morally sound decisions. Ethical failures can cause serious and disastrous consequences at the work place or the society.
d) Workplace literacy: Today’s workplace literacy includes communication skills, teamwork, time management, leadership, and most importantly, emotional intelligence and empathy.
Cognitive overload is another major challenge in this era of information wilderness where virtually every perceivable member of the community is inundated with vast volumes of information every moment, which often creates confusion. The human mind has limited capacity for attention and memory. Continuous digital distractions can weaken concertation, reduce reflective thinking and may affect mental wellbeing.
While the meaning of literacy has undergone a remarkable transformation over the past 60 years or so, the digital age has created opportunities as well as unpresented challenges. Modern literacy requires not only access to information but also the wisdom to evaluate, analyse and apply it effectively. Books, reading habits, reflective thinking and reliable sources of knowledge remain essential even in the era of artificial intelligence.
For many years, literacy and competency have been considered as different subjects. However, in the modern world, the demarcation between the two have been gradually getting blurred. Literacy does not simply mean how much one knows but more on how the knowledge is applied for value creation. This convergence is evident in all walks of life. Employers are increasingly seeking persons who can demonstrate competence rather than merely possessing qualifications. Competency-based education has entered the curricula of many private and governmental institutions in Sri Lanka. Conventionally, Sri Lanka is said to possess one of the highest literacy rates in the region. However, the progress achieved in many aspects of socio-economic, ethical and cultural fronts do not seem to have a matching congruence with competency.
As the American writer, futurist and businessman Alvin Tofler (1928-2016) once quoted,
“The illiterate of the 21st century will not be those who cannot read and write, but those who cannot learn, unlearn, and relearn.”
The meaning centres on the shift from static knowledge to the critical need for constant adaptability in a rapidly evolving world.
The author is a Management Counsellor from Sri Lanka.
- Mexico
- Bridgestone
- Michelin
- Goodyear
- Pirelli
- Yokohama
- Sailun
- Zhongce Rubber (ZC Rubber)
- JK Tyre & Industries
Mexico, A Hub For Tyre Manufacturing
- By Ertugrul Bahan
- September 03, 2026
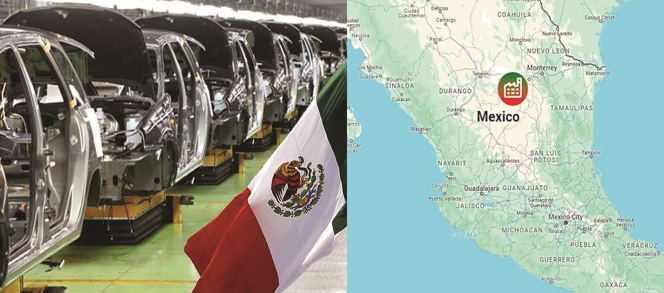
Mexico is attracting industrial investment thanks to the development of local production in the areas of high-tech manufacturing, automotive industry, logistics and energy; it is also a major exporter of tyres to North America.
Thanks to its significant export opportunities, Mexico is one of the world’s leading tyre production locations. As a North American country and a member of the USMCA (the free trade agreement between the USA, Mexico and Canada), Mexico benefits from duty-free exports to United States, making it an ideal choice for companies seeking to minimise the risks associated with tariffs.
Furthermore, international trade barriers and geopolitical risks are the main drivers of this industrial restructuring. Starting 3 May 2025, United States imposed a 25 percent tariff on imports of automotive tyres from Europe and Brazil, which will have an immediate impact on the traditional supply chains of multinational tyre manufacturers.
Mexico is attracting industrial investment, driven by the development of local production in high-tech manufacturing, automotive, logistics and energy. Significant investments in states such as Querétaro, Nuevo León, Guanajuato, Hidalgo and Coahulla demonstrate growing confidence in Mexico’s role as a manufacturing hub for North America.
Mexico is a major tyre exporter. In 2025, exports totalled USD 2.1 billion, with 87 percent going to the US. Despite its export strength, the Mexican tyre market is under pressure from imports from the Far East, particularly from China. Tyres from Chinese brands account for 45 percent of the passenger car segment and 80 percent of the truck segment.
In response to market manipulation, the Mexican government imposed permanent tariffs of between 5.18 percent and 32.24 percent on these imports. This measure is intended to protect the domestic industry from dumping caused by the influx of cheap Chinese tyres. The policy has already begun to reshape the market. Bridgestone forecasts a 30 percent increase in sales of premium truck tyres by 2025.
Bridgestone, Michelin, Goodyear, Pirelli, Yokohama, Sailun, Zhongce Rubber (ZC Rubber) and JK Tyre are represented in Mexico with production capacities for tyres for passenger cars and light commercial vehicles.
The relocation of production facilities is a significant trend as global companies seek to shorten their supply chains for the North American market. Recent investments include Yokohama’s USD 380 million plant with an annual capacity of five million tyres. Zhongce Rubber has invested USD 500 million in its production facilities. Sailun owns a USD 240 million plant in Irapuato. Pirelli is investing heavily in expanding its Mexican production facilities with very modern and productive manufacturing facilities.
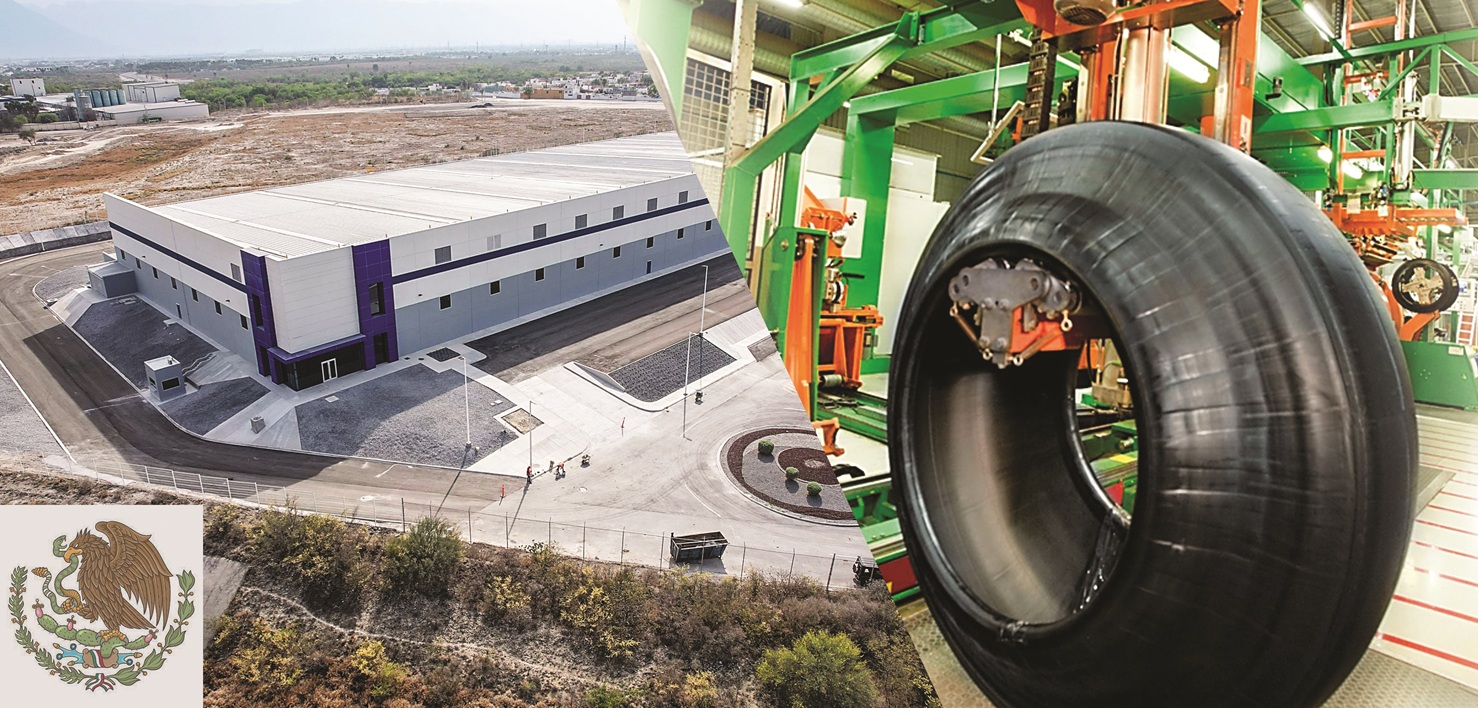
Bridgestone, Michelin, Goodyear, Pirelli, Yokohama, Sailun, Zhongce Rubber (ZC Rubber) and JK Tyre operate tyre plants in Mexico, some even two. This growth in Mexico has improved the efficiency and responsiveness of the North American tyre supply chain. Delivery times to US have been reduced from 45 to 7 days, significantly increasing the stability of this supply chain. Mexico’s annual production capacity for passenger car and light commercial vehicle tyres currently exceeds 65 million units, while the capacity for truck and bus tyres ranges between one and two million units.
Foreign companies in Mexico benefit from several crucial advantages. The most important and attractive is the competitive labour cost. This offers a significant cost advantage compared to US and Canada. Total production costs, including bonuses and benefits, range between USD six and USD eight per hour. This wage gap can be as high as 80 percent compared to US, even when considering the numerous social benefits enjoyed by Mexican workers.
Secondly, the country has a large and young population with approximately 42 million people under the age of 19. This represents a significant and steadily growing labour pool for industry. This pool of young talent is a valuable asset for companies focused on long-term growth.
The industry is increasingly recognising that competitiveness requires far more than just low wages for strategic innovation. Investors and industry associations are fully aware of this and emphasise that competitiveness inevitably involves creating added value, and that this can only be achieved through investment in talent. Companies are seeking employees with skills in innovation, critical thinking, teamwork and leadership.
Although some disadvantages make Mexico a risky investment location, they do not deter investors. Government stabilisation is contributing to a significantly more favourable investment climate over time and offers numerous advantages for expanding into the country.
However, Mexico presents several persistent disadvantages, risks and challenges for investors. Intense competition from cheap imports continues to strain the domestic market. This creates significant downward pressure, and even simple price adjustments can erode the profit margins of manufacturers of high-quality products. Infrastructure and logistics deficiencies hinder business operations. Mexican logistics infrastructure is considered outdated, particularly regarding intermodal connections, and customs procedures have become less efficient. These factors can increase operating costs and complicate supply chains.
An acute shortage of qualified personnel persists. Despite a young population, the high-tech manufacturing sector suffers from a critical lack of qualified staff, primarily due to high employee turnover and a lack of skilled workers in areas such as welding and maintenance.
Investors face complex challenges, including a tight labour market with rising wages, unreliable energy and water supplies in some areas and ongoing social conflicts that hinder the achievement of business goals. Mexican exports are primarily driven by a shift in trade away from China, rather than by a massive and widespread transfer of foreign capital.
Extortion and kidnapping are observed, particularly in border regions, with significant negative consequences for businesses and foreign investment. In response, the Mexican government has passed a new, comprehensive anti-extortion law, the implementation of which is being closely monitored by business associations.
Mexico offers a stable macroeconomic environment that surpasses that of many emerging markets. Numerous opportunities make Mexico an attractive manufacturing location for many industries…
Players in the Mexican tyre market are adjusting their strategies and focusing more on the domestic market or Brazil and Latin America due to the uncertainty persisting in Mexico regarding deliveries to US because of frequent changes in tariffs imposed by the Trump administration, regularly leading to delays or postponements of delivery dates.
The Mexican tyre industry faces several challenges, but its future will depend on its ability to develop innovative and high-quality products (such as tyres for electric vehicles), adapt its workforce to new requirements and succeed in the complex context of trade policies and global competition to ensure a sustainable and socially responsible future.
Despite some negative economic and social impacts, Mexico offers a stable macroeconomic environment with moderate inflation and rising wages. This has in a way a positive effect on public welfare state and as well as on the automotive and tyre industries. Therefore, rising vehicle sales and increasing disposable incomes are driving tyre demand. Mexico’s position as a hub for tyre production and exports is strengthening. Infrastructure development and growth in the automotive sector including tyre manufacturers are generating additional demand.
A positive aspect of the work ethic of many Mexicans lies in their exceptional productivity and their willingness to work long hours to complete their tasks. In modern industrial environments, employees are characterised by a high degree of professionalism and commitment. The Mexican tyre industry, for example, exemplifies a rapidly modernising work culture. It promotes a strong female presence and employs a very young workforce, with 75 percent of employees being under 35 years old. n
Mexico 2026: A Manufacturing Powerhouse Still Seeking To Revitalise Retreading
- By Daniel Rojas Enos
- August 21, 2026
While the tyre and rubber industries are experiencing one of their most dynamic periods thanks to North American integration, the retreading sector continues to face economic, cultural and market challenges in its efforts to regain momentum.
Few Latin American economies currently occupy as strategic a position within the global tyre industry as Mexico. The combination of manufacturing capacity, geographic proximity to United States and the advantages provided by the United States-Mexico-Canada Agreement (USMCA) has consolidated the country as one of the leading tyre and rubber manufacturing hubs in the region.
In recent years, US trade policies directed at producers located outside North America have further strengthened this position. Investment relocation, nearshoring strategies and the need to secure regional supply chains have created particularly favourable conditions for Mexican industry.
The effects are visible throughout the value chain. Tyre manufacturers, rubber compound producers and raw material suppliers are operating at high activity levels, largely driven by demand from the US market. Industry stakeholders consistently point out that the current challenge is not finding customers but maintaining sufficient capacity to meet North American demand.
The rubber compound industry is perhaps one of the clearest examples of this trend. Benefiting from the regional trade environment, many companies are operating close to full capacity, supplying tyre manufacturers as well as other rubber-related industries. A similar situation can be observed among several retreading material suppliers, whose primary concern is not local demand but their ability to meet growing requirements from United States.
Yet, while manufacturing is experiencing a period of expansion, the retreading sector faces a very different reality.
The paradox is striking. In a country that markets more than 40 million tyres annually and possesses one of Latin America’s strongest industrial platforms, retreading has not been able to regain a sustained growth trajectory.
During his presentation at the Latin Tyre & Auto Parts Expo Panama 2025, Juan Carlos Hernández, then Commercial Manager of Hules Banda, presented figures that help illustrate the scale of the challenge. According to the data presented, Mexico marketed more than 40 million tyres during 2024, with an estimated potential of over five million tyres suitable for retreading. However, only around 960,000 units were actually retreaded, representing a retreading rate of approximately 18 percent.
The figures become even more revealing when analysing installed capacity utilisation. While tyre factories report average idle capacity levels close to 14 percent, retreading plants operate with approximately 70 percent idle capacity. Furthermore, during the first months of 2025, retread production showed a decline of nearly 9 percent compared to the previous year.
The reasons behind this situation appear to be less related to technical capabilities and more connected to the economic incentives currently shaping the market.
The growing presence of low-cost imported tyres has significantly transformed purchasing decisions across many fleets. According to Hernández’s presentation, nearly 40 percent of the radial truck tyre market consists of Asian products sold for less than USD 150 per unit. As a result, the economic gap between purchasing a low-cost new tyre and investing in a retread has narrowed considerably for many operators.
In this context, measures such as tariffs on selected imported products have so far failed to generate significant structural changes in market behaviour or retreading activity levels.
However, attributing the situation solely to pricing would be an oversimplification.
One of the most interesting observations highlighted by Hules Banda points to a less visible but potentially more significant long-term issue: the gradual loss of tyre management culture.
For decades, retreading formed part of a comprehensive asset management strategy, where tyres were managed throughout multiple life cycles in order to maximise cost per kilometre performance. Today, in many segments of the transport industry, that approach has increasingly been replaced by purchasing decisions focused primarily on immediate acquisition costs.
The result has been lower casing utilisation, fewer maintenance and monitoring programmes and increasing difficulty in demonstrating the long-term economic benefits that have historically supported the retreading business model.
Paradoxically, those segments that continue to manage tyres as strategic assets still demonstrate the relevance of retreading. Fleets operating premium and medium-tier tyres remain highly dependent on retreading to optimise operating costs, improve profitability and maximise asset utilisation.
CIRCULAR ECONOMY BEYOND END-OF-LIFE TYRES
Another issue deserving attention is the way the circular economy debate is currently evolving within Mexico’s tyre sector.
Much of the public and regulatory discussion focuses on end-of-life tyres (ELTs), collection systems, reverse logistics and recycling or recovery solutions once the product reaches the end of its useful life. By contrast, strategies aimed at extending product life through reuse often receive considerably less attention.
This is particularly relevant given that internationally recognised circular economy principles establish a hierarchy in which extending product life generally delivers greater environmental value than interventions applied after a product becomes waste.
From this perspective, retreading represents one of the most tangible examples of circularity within the tyre industry, as it preserves the economic, material and energy value embedded in the original casing for a longer period.
Mexico will undoubtedly remain one of the leading players in the North American tyre industry. The strength of its manufacturing sector appears well supported by regional integration, industrial investment and strong demand from United States.
The question that remains is whether the retreading sector will be able to become fully integrated into this growth story.
The industrial capacity exists. The technology is available. Premium market segments continue to require strategies focused on maximising cost per kilometre performance. The challenge appears to lie elsewhere: rebuilding tyre management culture and repositioning retreading as a strategic tool for competitiveness, efficiency and circular economy performance.
At a time when much of the discussion focuses on managing tyres at the end of their life, perhaps the more important question is how to ensure that life lasts longer in the first place.
I can still vividly remember a journey I made in 1995 with my young Kenyan MD (who is no longer living) in a hired car from the Delhi Airport to some town close to Ludhiana to meet a tyre moulding machinery supplier. The travel was through vast expanses of paddy fields extending to miles, and in between, we could see large industrial sites far away. A clear sign of industry and agriculture co-existing synergistically. When passing the area called Kurukshetra, the driver mentioned that there was a war at this area a long time ago. He was obviously referring to the great war of the epic Mahabharata, a subject which still generates ample curiosity in me even at this advanced age. With growing years of maturity, I am more convinced that the great war symbolically and semantically depicts the inner conflicts going on in our own minds, while these are conventionally polarized as ‘black and white’ under the ‘all- or- nothing’ principle, and Kurukshetra represents our own hearts and intellect, commonly called the emotional brain and intellectual brain in today’s jargon. Equipped with my industry experience acquired for nearly six decades, I am tempted to make a rather feeble effort to understand what has changed in the managerial mind map over the past 50 odd years. It would be similar to finding parallels between the Vietnam War in the late sixties and current war going on in the Middle East, despite the common factor, US.
Quite in contrast to machinery and materials, the man component of the traditional 4Ms is the most confusing area despite the vast research that has been carried out over the years. It is said that the adult human brain consists of about 86 billion neurons, an astronomically high figure compared to memory capacity of the modern computers. Over the past few decades, the modern managerial mindset has undergone profound transformations. Managers today, particularly in the age group of 35 to 50 ( Gen X), operate in an astonishingly different scenario compared their counterparts 50 years ago. The two eras are fundamentally different and attempting to compare them is largely futile. The rapid changes, technologically, culturally, socially and psychologically, are so vast that today’s managers are shaped by globalisation, digitalisation and fierce competition, which has significantly altered their cognition, thinking patterns, values and behavioural approaches.
While most living managers of the older generation adopt a stance of lamenting about the ‘’good old times’, I think it would be more prudent to understand the realities of change. Management philosophies have undergone profound change, evolving from Taylor’s scientific management and Fayol’s top-down framework based on five key managerial functions to the humanistic approaches advanced by Carl Rogers and Maslow. This is the universal feature of impermanence of all conditioned phenomena (cause-effect related), discovered more than 2,600 years ago by Lord Buddha and some Greek and other Eastern philosophers. Endeavoring to maintain stability, in an ever-changing world scenario, has been the driver for the emergence of management concepts and theories, including the latest approaches seen in the contemporary modern world. Comparing modern managers with those from 50 years ago is unrealistic because of the complete change in the context. Earlier managers operated in stable and localised economies, while modern managers operate in a dynamic globalised environment. It is sometimes said that ‘when the President of the United Sates sneezes, the Eastern leaders catch a cold’, a fact amply demonstrated by the recent events.
Decision-making in the past was slow and experience-based, while today it is data driven, rapid and technologically assisted. Traditional management emphasised relationships, loyalty and progressive and gradual growth, while modern systems emphasise on performance metrics and quick results, like the instant coffee.
The growing corporate trends due to industrialisation over the past 30 years especially has witnessed increased focus on productivity, efficiency and outputs along with standardisation, which has made workers and managers becoming a part of a mechanised system. Modern corporate managerial thinking is also been heavily influenced by globalisation, due to exposure to international competition and the need to adapt to diverse cultures and markets and the pressures to meet global benchmarks and standards. The constrains and the stresses imposed on countries such as Sri Lanka is tough in these areas. A good example is the EUDR requirements, which initially was a nightmare to the rubber product manufacturing companies. A far more serious non-technical consequence is that the concept of a ‘global village’ is eroding values of the strong cultural and ethical foundation, leading to identity dilution among managers
During my association with the industry, particularly over the past 20 years, I have personally witnessed decline of the traditional values in the modern managerial mindset. This is also seen in some professional associations in which I have been a member for a long time. Some of the key trends noted are as follows:
a) Limited understanding and low priority given for religion, history and cultural heritage.
b) Reduced emphasis on ethics, empathy and social responsibility despite the fact that this has become a ‘catch word’ in most corporate circles.
c) Over reliance on technical knowledge and digital skills.
d) Decline in the respect for elders and their experience (crystallised knowledge)
e) Over confidence due to access to information, which brings forth a ‘know it all ‘stance.
f) Diminished openness to learn from others.
g) Difficulty in accepting criticism and feedback
While these tendencies directly affect workplace relationships, team cohesion and leadership effectives, the hidden or latent consequences have more deeper implications on personal and social wellbeing.
The Buddha in one of the discourses has observed that a person can victoriously face a battle against an army of elephants, horses, chariots and infantry by having the necessary resources, but it will be more difficult to win the war within due to mental conflicts.
Most business environments are characterised by aggressive target setting, continuous performance evaluations and competitive organisational cultures, which has caught the managers in a perpetual rat-race where success is narrowly defined by targets and profits while there is hardly any time for reflection or personal growth. This creates a certain emptiness and dissatisfaction even among the high achievers.
I find it interesting at this juncture to refer to the historic concept of Sigmond Freud (considered as the founder of Psychoanalysis), the structural components of the mind, namely Id (pleasure principle or gratification), Ego (reality principle) and the Super Ego (ethical and moral conscience). In order to minimise the negative impacts of the conflicts between them, the Ego resorts to defence mechanisms, or temporary coping solutions. Some of these are denial of the problem, repression of the feelings, projection of the blame to somewhere else and rationalisation or giving logical but false explanations. While these are useful in the short term, over reliance can interfere with mental functioning and emotional growth. All of us are unconsciously resorting to one or several of these in times of emotional turmoil.
The pressures of modern management have led to an exponential growth in mental health challenges in recent years, which include common mental disorders such as stress, anxiety, burnout, depression and features associated with Borderline Personality traits (emotional instability and impulsivity), which result in work-life imbalance and chronic dissatisfaction.
Due to the high psychological demands, there is a growing need for career and workplace counselling. Counselling is a relatively new term that came into prominence around the mid-20th century, before which guidance and support was traditionally provided by the religious institutions, parents, teachers and the elders in the society. Over the recent years, counselling has evolved as a unique profession. Many organisations, especially the larger ones due to the seriousness and gravity of the problems they experience, have established counselling as a regular activity performed in-house or outsourced. Counselling helps managers to cope up with stress and expectations, supporting emotional regulation and resilience and enhancing self-awareness and interpersonal skills, which results in reconnecting purpose and meaning and balancing professional and personal life to develop a healthier mind set. The modern managers must endeavour to have a balanced mind set which is an integrated mix of technical competence, human values, cultural awareness and emotional intelligence and wellbeing. Only then they can move beyond being mere ‘cogs in a wheel’ and become holistic, effective and ethical leaders in the modern world
It is somewhat ironic that Human Resource Sustainability is not named as a single standalone goal in the United Nations Sustainable Development Goals (SDGs) but covered under several headings such as Good Health and Wellbeing, Quality Education, Gender Equality, Decent Work, Economic Growth and Reduced Inequalities.
While I do not have firsthand information on how human resource counselling is caried out in other countries, my observations and experience in Sri Lanka is that it is done more in a fire fighting or reactive mode, where corrective and remedial measures are taken only in cases of psychological deviances. It is somewhat surprising because Sri Lanka is famous for its preventative public health care in pre and postnatal maternity health and school dental health. Industry safety and health is fairly well addressed in most large, medium and some small enterprises, although these are mainly covering the operational levels. Currently, several standard stress, anxiety and depression measuring scales, both qualitative and quantitative, are available, but they do not seem to be used proactively to detect the cinders underneath the ash. People in emotional distress invariably need to vent their thought and emotions, which causes several cognitive distortions and mental disorders. Active and empathetic listening plays the major role in a therapeutic counselling relationship
Coming back to the Mahabharata, the classic instance of counselling for a person in deep emotional conflict and inner war is the Bhagwat Gita, and all of us will need Lord Krishnas in different disguises at some stages in our lifetimes.
It is interesting how Buddha has adopted an integrative approach to the four aspects or components of wellbeing for human progress as:
- Physical wellbeing
- Mental wellbeing
- Social wellbeing
- Spiritual wellbeing
The author is a Management Counsellor from Sri Lanka.
Comments (0)
ADD COMMENT