The Gulf Crisis Leading To A Profound Change In The Tyre Industry
- By Ertugrul Bahan
- June 15, 2026
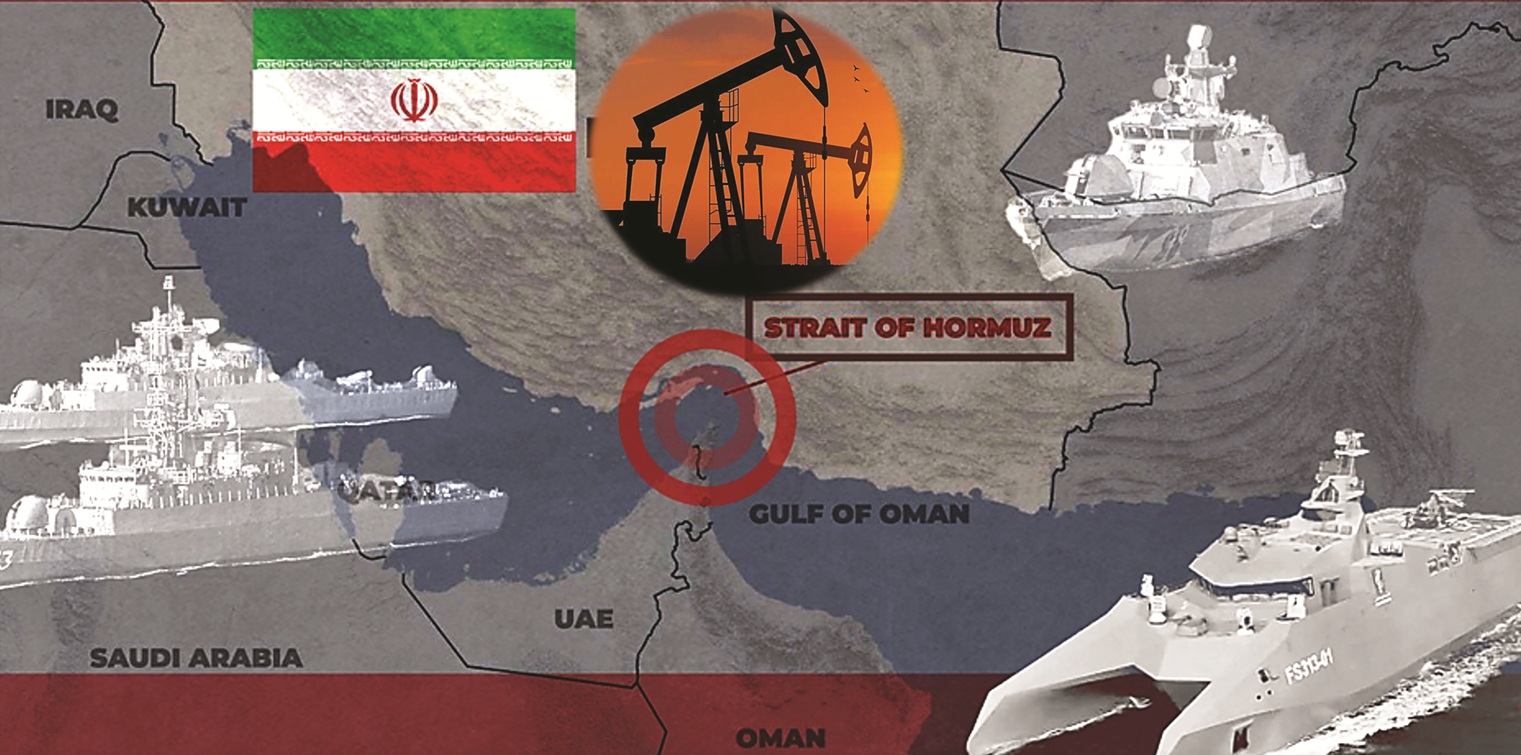
The effects of the Strait of Hormuz closure will become particularly evident in 2026 and undoubtedly represent a strategic bottleneck for global energy and petrochemical trade. The Gulf War disrupted raw material supplies, crippled logistics and destabilised key export markets.
While the war represents a financial catastrophe, it also presents new opportunities. It has driven up raw material costs, while the logistics crisis has impacted export markets. The financial consequences include shrinking margins and reduced demand. However, long-term strategic shifts are expected, and these trends are likely to accelerate by 2040.
The closure of the Strait of Hormuz and the disruptions in the Red Sea have brought maritime traffic to the Middle East and Europe to a near standstill. The war has caused logistical chaos, and exports face immediate difficulties. China alone was expected to export more than seven million tyres to the Middle East by 2025, but this vital trade route is now blocked by skyrocketing freight rates and insurance premiums.
The profitability of the sector, whose gross margins are expected to fall to slightly more than four times their pre-war levels, is likely to be impacted by market consolidation and rising demand for high-tech tyres, particularly for electric vehicles. In the short to long term, the costs of raw materials such as synthetic rubber, carbon black and logistics are expected to rise significantly. Furthermore, this crisis could spur massive investments in bio-based and recycled materials to reduce dependence on petroleum. To address supply bottlenecks, the sharp decline in exports from the Middle East, coupled with significantly increased transportation costs, should be offset by regionalised production, for example, in India and Southeast Asia. With regard to product development, the short-term priority of cost control should lead to an acceleration of research and development into sustainable rubber compounds and sensorless smart tyres.
The end of the Gulf War is likely to usher in a period of weak economic growth and high inflation. The tyre industry is already facing a profound restructuring process. In the post-war era, the focus is not only on repairing the damage but, above all, on accelerating the long-term transition to regionalised supply chains, a circular economy and value creation through technology.
The most immediate consequence of war is a drastic increase in raw material costs,
which can account for almost 70 percent of tyre production costs. Around 45 percent of the raw materials used in the tyre industry are petroleum-based, and another 45 percent are natural rubber. In the case of synthetic rubber (NBR/SBR), the direct rise in oil prices leads to a price increase for butadiene, a key raw material. In the US, NBR prices rose by 7.4 percent at the beginning of March 2026; in China, butadiene prices jumped by 25 percent within a week.
Analysts estimate that this conflict could reduce global natural rubber production by 36 to 45 kilotonnes in the first half of 2026. How can this be explained, given that the effects on natural rubber are indirect? Diesel shortages prevent trucks from collecting rubber from plantations, thus reducing supply on the market. This shortage is contributing to the energy crisis in Southeast Asia. Prices for carbon black and chemicals derived from oil and gas are also rising in line with increasing energy costs. The supply of speciality chemicals (such as bromine from Israel) is also at risk.
Bio-based materials, particularly long-term ESG pilot projects, represent an immediate strategic necessity. The market for bio-based materials is projected to reach USD 337 million by 2032, with a compound annual growth rate (CAGR) of 101 percent, thus replacing volatile petrochemical feedstocks. Similarly, it is becoming increasingly clear that tyre pressure monitoring systems (TPMS) and sensorless, AI-powered systems like Michelin SmartWear can reduce costs and enhance safety.
Rising energy prices and crumbling infrastructure will weigh on consumption and investment. Inflation is high and is expected to remain high (around four percent for the G20 in 2026). Even after the war, energy costs and the rebuilding of supply chains will keep prices high. Consequently, the post-war economic recovery is expected to be slow and uneven, without a V-shaped rebound. The war has left lasting scars on global supply chains and public finances. Global GDP growth is weaker and below the pre-pandemic average.
In the field of carbon black recycling, carbon black is developing into a strategic raw material. Recycled carbon black (rCB) and tyre pyrolysis oil are becoming strategic raw materials intended to replace unstable fossil fuels. Massive investments, such as in Lummus-InnoVent, a continuous pyrolysis technology, will increase rCB production and reach a market of USD 15.6 billion by 2034.
Sustainable and bio-based materials are of great strategic importance, and significant investments are already being made to increase their production. Rising oil prices are making bio-based alternatives economically viable and essential for security of supply. Therefore, the transition to sustainable materials is no longer just an ESG goal but a necessity for the entire supply chain.
 The Gulf War acted as a powerful catalyst, transforming promising future trends into immediate and essential investments. Bio-based silanes, for example, are now being used more and more frequently. Momentive’s NXT P97, a next-generation silane for electric vehicle tyres with 79 percent bio-based carbon, reduces reliance on fossil fuels while improving rolling resistance and durability. This technology, a prime example, is currently being deployed on a large scale.
Tyre prices will remain high. The recovery will therefore be characterised more by rapid strategic development than by a simple return to pre-war levels. It is not so much the fluctuating demand from car manufacturers, but rather the replacement tyre market, which alone accounts for 70 percent of the volume, that is likely to continue to strongly support the consumer goods and logistics sectors during the economic recovery.
Increasing uncertainty is becoming the new normal. Geopolitical risks remain a key concern, forcing companies to prioritise resilience over efficiency. This situation is creating unequal competitive conditions for tyre manufacturers and their core markets. The difficulties faced by energy-importing countries in Europe and Asia will be further exacerbated in this climate of uncertainty.
This crisis will be one of the main reasons for the relocation of production to key markets, forcing the tyre industry to make unavoidable investments. It will be compelled to implement the technologies necessary for a more resilient, sustainable and technologically advanced future. New production centres will be established to circumvent geopolitical obstacles. This new dynamic is characterised by a clear strategic realignment of production and supply chains, accelerating ‘out-of-China’ models and leading to regionalisation. This conflict is not merely a disruption but a form of brutality for economically weaker countries, even if it represents a highly effective response to the relocation of production areas.
This war teaches us that excessive dependence on unstable regions like the Middle East must be balanced by the need for market diversification. Exporters like China and India will increasingly focus on Africa, Latin America and Southeast Asia. Margins will remain under pressure in the short term. High raw material and energy costs will not fall immediately. Large global companies will gain market share by leveraging their size and technology, as well as through increased regionalisation. Conversely, smaller, less diversified companies risk being acquired or exiting the market. Companies with strong pricing power and high operational efficiency will recover faster than those that rely solely on low prices.
The tyre industry is facing profound change. The tyre market is being restructured, and local, sales-oriented production is being intensified to circumvent geopolitical barriers and tariffs. In the short term, demand is expected to recover, but profit margins will be severely impacted by persistently high costs. In the long term, the sector will become more regionally focused, evolve towards a circular economy and rely more heavily on technology. In short, the end of the war will not restore the pre-conflict status quo. The crisis has forced a difficult but necessary transition to sustainable and resilient business models that will shape the key trends through 2040.
As a surviving member of the ‘baby boomer’ generation that commenced with the rapid economic growth following the World War II, I think we are, in a broad sense, privileged to have witnessed and experienced the happenings and consequences of about 50 years in the 20th Century and about 30 years in the 21st Century. When contemplating on the term literacy and its traditional meaning of being able to read and write from an educational perspective, I feel it fitting to cite a few real-life cases, from way back, which make me to wonder whether the above interpretation of literacy is all encompassing.
a) My maternal grandmother, who was born in 1900, did not know reading or writing, a typical feature about the female folk in that era, especially in the remote villages. Despite this apparent handicap, she successfully managed the day-to-day administration of the paddy fields and the rubber plantation, including finances, and raised three children to become worthy human beings.
b) Then there were these three young people who had migrated to Colombo with minimal formal education and started their business in humble ways to become well recognised icons of international fame in the healthcare, confectionary and rubber footwear and tyres, respectively, the latter being related to my own core field, the rubber industry.
c) Last but not the least, the late Martin Wickremasinghe, born in the late 19th century, who attended school only up to the 7th standard, wrote hundreds of books on diverse subjects such as history, anthropology, sociology, religion and literature and several novels (some of which were translated to several languages), which rightfully recognised him as a well-respected scholar and the greatest writer in Sri Lanka.
While it may be futile to compare apples with oranges, I feel that literacy has a utilitarian perspective, which can change with the social context and the circumstances. With my manufacturing background, I see a close parallel of literacy and quality. Out of the hundreds of definitions available of the latter, ‘fitness for use and the level to which requirements are fulfilled’ is applicable to literacy as well.
When going through the available information on the subject, it is noted that ‘literate’ can be traced back to the early 15th century from the Latin word literatus, meaning learned, educated and lettered. Initially, literate meant someone who was well educated, learned and acquainted with literature, and over time, as basic schooling became more widespread, the word was adapted to describe the foundational skill of reading and writing. The Oxford Advanced Learner’s Dictionary defines literacy primarily as ‘the ability to read and write’. Two core definitions for the term are identified as Basic Literacy, the fundamental ability to read and write, and Specialised Literacy, the competence, knowledge or skill in a specific subject area in which common modern applications include:
a) Computer literacy: The ability to use computers effectively.
b) Financial literacy: Understanding and effectively managing personal finances.
c) Health literacy: The capacity to obtain, process and understand basic health information and services.
It could be inferred that we, the ‘baby boomers’, currently at an advanced stage in life, cannot do without the above basic literacies, and as a minimum, the routine health check such as blood sugar, blood pressure, LDL and HDL etc. to survive and lead active lives.
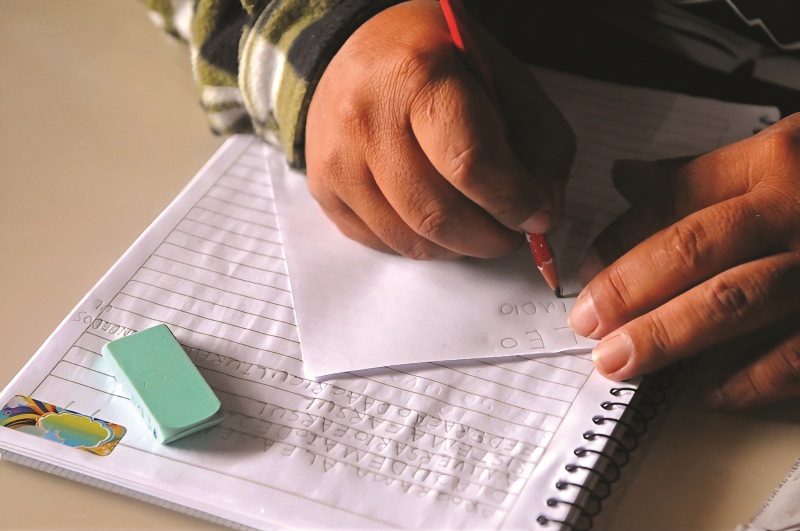
It is said that writing originated primarily out of economic necessity as the early agricultural societies grew and needed to track goods, taxes and trade. The evolution of writing from rudimentary clay tokens in to the world’s first independent writing systems in Mesopotamia, Egypt, China and Mesoamerica around 3200 BC to 3000 BC is a story that requires a deeper elucidation at a different forum.
Literacy is considered as one of the most important foundations of civilisation and has played a crucial role in human survival and existence both evolutionary and historically. However, instead of going into a deliberation of these foundational perspectives, I intend to offer some of my personal insights and recollections on this important subject over the past 60-plus years. I can recollect how at preschool stage, we were initiated into the basics of reading and writing using slates and slate pencils (made out of a silicious material) and the ‘black boards’ in the class room where chalk was used for writing. Literacy mainly meant the ability to read and write and, in later classes, in performing basic arithmetic. In schools and workplace, literacy was closely connected to formal education and subject knowledge. A literate person was one who could understand written communications, reads books and newspapers, write letters and maintain records and perform effectively in society. It was directly connected to social respectability and economic progress.
Literacy in English was considered as a rare virtue in countries which were under the British colonial rule. It was confined only to a few ‘high level’ schools in Colombo and in some major towns. Hailing from a rural background and having attended a small primary school in a remote town, I have first-hand experience of the panic and inferiority when I started secondary education in Colombo. This was especially true when we started studying for the Government (Ordinary Level Exams) in the science stream which was all in English. It was a struggle to get adapted and face the challenge, which I would say, I managed fairly well.
In those days, literacy was essentially confined to formal education and subject knowledge. Students were expected to memorise facts, understand texts and reproduce the information during the examinations. Books and libraries were the main sources of knowledge. Teachers were well recognised and respected as the primary sources of knowledge. And learning was generally a disciplined and structured process. And information, though limited, was relatively organised. I do not consider this as a deficiency or a weakness at all, because it fitted well with the societal and business expectations of those days.
I can well remember the day of my first interview seeking a job, which happened to be in the rubber industry. Instead of asking about isoprene or how the RSS (Ribbed Smoked Sheet) is made, although I managed to cram some information about the latter, I was asked about Ohm’s Law and how steel is made from iron ore. I was lucky because in our Advanced Level class, we had studied the above, and this paved way for a lifelong career in the rubber industry.
Literacy seems to be directly proportional to the rate of percolation or trickling down of the technologies to countries in our part of the world, and this was a rather slow process until the early eighties. However, mankind is evolutionary geared for ‘adaptive radiation’, which in modern jargon can be interpreted as how quickly we learn and get used to the new situations and contingencies as we meet new frontiers. According to the modern theories of cognitive learning, we acquire new knowledge through assimilation of new concepts (schemas) or by accommodation of incoming concepts into our existing knowledge. As an example, I can relate with my personal experience how my literacy in rubber technology evolved, starting as young trainee with very little knowledge on rubber. With the rapid development of science, technology and globalisation and artificial intelligence, the meaning of literacy has expanded beyond the traditional horizons.
In contrast to the scenario of over 50 years ago, today’s literacy has grown to include cultural awareness, ethical understanding, workplace competence, computer literacy, digital communication and the ability to manage continually increasing volumes of information; some of them are very often recurring and sometimes redundant. Some key diversions are shown as follows:
a) Educational and subject literacy: While mathematical and scientific literacy, language proficiency and analytical thinking is essential, they go beyond memorising facts to effective application of the knowledge.
b) Cultural literacy: This has become increasingly important in this era of extending globalisation for respectful understanding and effective communications. This also includes awareness of history, religion, social values and traditions, which lamentably is declining amongst the younger generations.
c) Ethical literacy: This simply means the ability to distinguish the right and the wrong, social responsibility and taking morally sound decisions. Ethical failures can cause serious and disastrous consequences at the work place or the society.
d) Workplace literacy: Today’s workplace literacy includes communication skills, teamwork, time management, leadership, and most importantly, emotional intelligence and empathy.
Cognitive overload is another major challenge in this era of information wilderness where virtually every perceivable member of the community is inundated with vast volumes of information every moment, which often creates confusion. The human mind has limited capacity for attention and memory. Continuous digital distractions can weaken concertation, reduce reflective thinking and may affect mental wellbeing.
While the meaning of literacy has undergone a remarkable transformation over the past 60 years or so, the digital age has created opportunities as well as unpresented challenges. Modern literacy requires not only access to information but also the wisdom to evaluate, analyse and apply it effectively. Books, reading habits, reflective thinking and reliable sources of knowledge remain essential even in the era of artificial intelligence.
For many years, literacy and competency have been considered as different subjects. However, in the modern world, the demarcation between the two have been gradually getting blurred. Literacy does not simply mean how much one knows but more on how the knowledge is applied for value creation. This convergence is evident in all walks of life. Employers are increasingly seeking persons who can demonstrate competence rather than merely possessing qualifications. Competency-based education has entered the curricula of many private and governmental institutions in Sri Lanka. Conventionally, Sri Lanka is said to possess one of the highest literacy rates in the region. However, the progress achieved in many aspects of socio-economic, ethical and cultural fronts do not seem to have a matching congruence with competency.
As the American writer, futurist and businessman Alvin Tofler (1928-2016) once quoted,
“The illiterate of the 21st century will not be those who cannot read and write, but those who cannot learn, unlearn, and relearn.”
The meaning centres on the shift from static knowledge to the critical need for constant adaptability in a rapidly evolving world.
The author is a Management Counsellor from Sri Lanka.
- Mexico
- Bridgestone
- Michelin
- Goodyear
- Pirelli
- Yokohama
- Sailun
- Zhongce Rubber (ZC Rubber)
- JK Tyre & Industries
Mexico, A Hub For Tyre Manufacturing
- By Ertugrul Bahan
- September 03, 2026
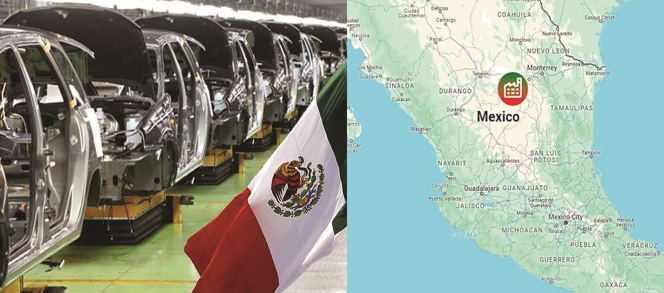
Mexico is attracting industrial investment thanks to the development of local production in the areas of high-tech manufacturing, automotive industry, logistics and energy; it is also a major exporter of tyres to North America.
Thanks to its significant export opportunities, Mexico is one of the world’s leading tyre production locations. As a North American country and a member of the USMCA (the free trade agreement between the USA, Mexico and Canada), Mexico benefits from duty-free exports to United States, making it an ideal choice for companies seeking to minimise the risks associated with tariffs.
Furthermore, international trade barriers and geopolitical risks are the main drivers of this industrial restructuring. Starting 3 May 2025, United States imposed a 25 percent tariff on imports of automotive tyres from Europe and Brazil, which will have an immediate impact on the traditional supply chains of multinational tyre manufacturers.
Mexico is attracting industrial investment, driven by the development of local production in high-tech manufacturing, automotive, logistics and energy. Significant investments in states such as Querétaro, Nuevo León, Guanajuato, Hidalgo and Coahulla demonstrate growing confidence in Mexico’s role as a manufacturing hub for North America.
Mexico is a major tyre exporter. In 2025, exports totalled USD 2.1 billion, with 87 percent going to the US. Despite its export strength, the Mexican tyre market is under pressure from imports from the Far East, particularly from China. Tyres from Chinese brands account for 45 percent of the passenger car segment and 80 percent of the truck segment.
In response to market manipulation, the Mexican government imposed permanent tariffs of between 5.18 percent and 32.24 percent on these imports. This measure is intended to protect the domestic industry from dumping caused by the influx of cheap Chinese tyres. The policy has already begun to reshape the market. Bridgestone forecasts a 30 percent increase in sales of premium truck tyres by 2025.
Bridgestone, Michelin, Goodyear, Pirelli, Yokohama, Sailun, Zhongce Rubber (ZC Rubber) and JK Tyre are represented in Mexico with production capacities for tyres for passenger cars and light commercial vehicles.
The relocation of production facilities is a significant trend as global companies seek to shorten their supply chains for the North American market. Recent investments include Yokohama’s USD 380 million plant with an annual capacity of five million tyres. Zhongce Rubber has invested USD 500 million in its production facilities. Sailun owns a USD 240 million plant in Irapuato. Pirelli is investing heavily in expanding its Mexican production facilities with very modern and productive manufacturing facilities.
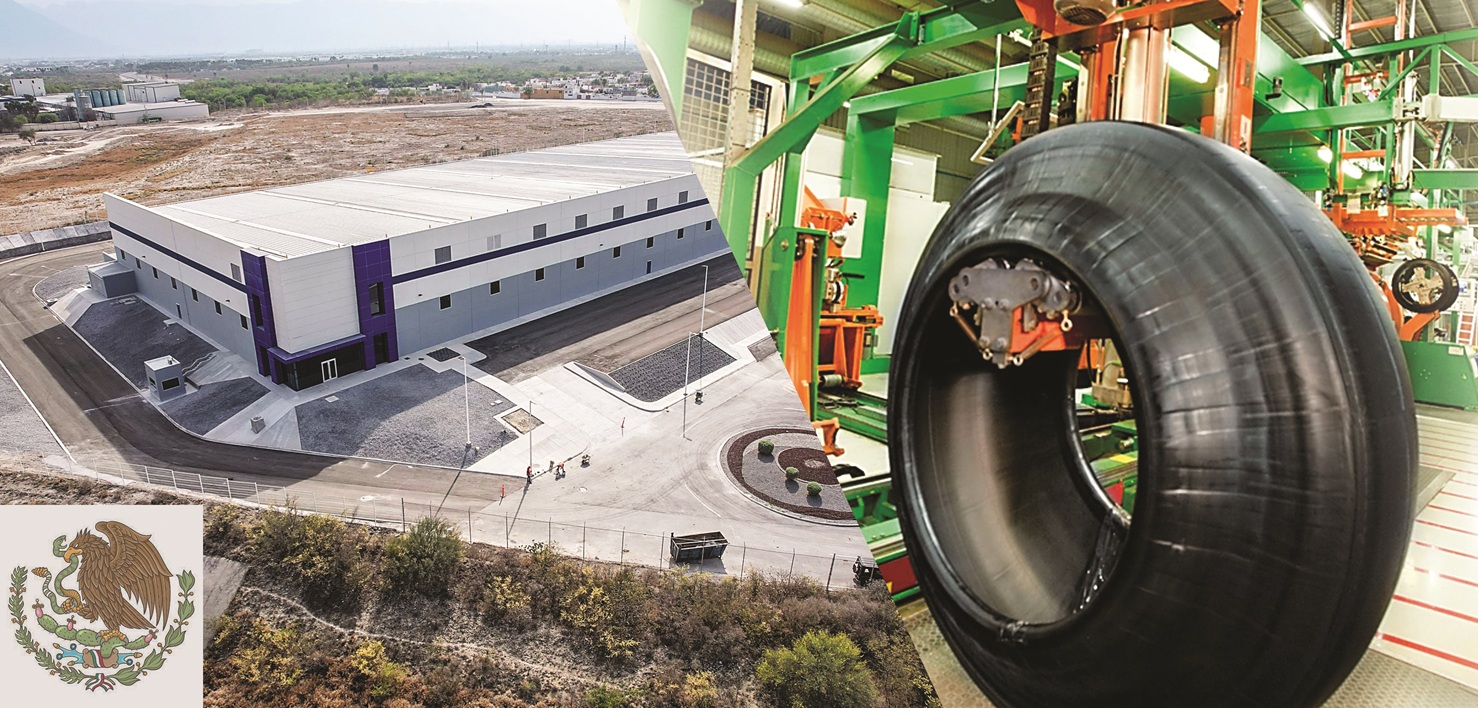
Bridgestone, Michelin, Goodyear, Pirelli, Yokohama, Sailun, Zhongce Rubber (ZC Rubber) and JK Tyre operate tyre plants in Mexico, some even two. This growth in Mexico has improved the efficiency and responsiveness of the North American tyre supply chain. Delivery times to US have been reduced from 45 to 7 days, significantly increasing the stability of this supply chain. Mexico’s annual production capacity for passenger car and light commercial vehicle tyres currently exceeds 65 million units, while the capacity for truck and bus tyres ranges between one and two million units.
Foreign companies in Mexico benefit from several crucial advantages. The most important and attractive is the competitive labour cost. This offers a significant cost advantage compared to US and Canada. Total production costs, including bonuses and benefits, range between USD six and USD eight per hour. This wage gap can be as high as 80 percent compared to US, even when considering the numerous social benefits enjoyed by Mexican workers.
Secondly, the country has a large and young population with approximately 42 million people under the age of 19. This represents a significant and steadily growing labour pool for industry. This pool of young talent is a valuable asset for companies focused on long-term growth.
The industry is increasingly recognising that competitiveness requires far more than just low wages for strategic innovation. Investors and industry associations are fully aware of this and emphasise that competitiveness inevitably involves creating added value, and that this can only be achieved through investment in talent. Companies are seeking employees with skills in innovation, critical thinking, teamwork and leadership.
Although some disadvantages make Mexico a risky investment location, they do not deter investors. Government stabilisation is contributing to a significantly more favourable investment climate over time and offers numerous advantages for expanding into the country.
However, Mexico presents several persistent disadvantages, risks and challenges for investors. Intense competition from cheap imports continues to strain the domestic market. This creates significant downward pressure, and even simple price adjustments can erode the profit margins of manufacturers of high-quality products. Infrastructure and logistics deficiencies hinder business operations. Mexican logistics infrastructure is considered outdated, particularly regarding intermodal connections, and customs procedures have become less efficient. These factors can increase operating costs and complicate supply chains.
An acute shortage of qualified personnel persists. Despite a young population, the high-tech manufacturing sector suffers from a critical lack of qualified staff, primarily due to high employee turnover and a lack of skilled workers in areas such as welding and maintenance.
Investors face complex challenges, including a tight labour market with rising wages, unreliable energy and water supplies in some areas and ongoing social conflicts that hinder the achievement of business goals. Mexican exports are primarily driven by a shift in trade away from China, rather than by a massive and widespread transfer of foreign capital.
Extortion and kidnapping are observed, particularly in border regions, with significant negative consequences for businesses and foreign investment. In response, the Mexican government has passed a new, comprehensive anti-extortion law, the implementation of which is being closely monitored by business associations.
Mexico offers a stable macroeconomic environment that surpasses that of many emerging markets. Numerous opportunities make Mexico an attractive manufacturing location for many industries…
Players in the Mexican tyre market are adjusting their strategies and focusing more on the domestic market or Brazil and Latin America due to the uncertainty persisting in Mexico regarding deliveries to US because of frequent changes in tariffs imposed by the Trump administration, regularly leading to delays or postponements of delivery dates.
The Mexican tyre industry faces several challenges, but its future will depend on its ability to develop innovative and high-quality products (such as tyres for electric vehicles), adapt its workforce to new requirements and succeed in the complex context of trade policies and global competition to ensure a sustainable and socially responsible future.
Despite some negative economic and social impacts, Mexico offers a stable macroeconomic environment with moderate inflation and rising wages. This has in a way a positive effect on public welfare state and as well as on the automotive and tyre industries. Therefore, rising vehicle sales and increasing disposable incomes are driving tyre demand. Mexico’s position as a hub for tyre production and exports is strengthening. Infrastructure development and growth in the automotive sector including tyre manufacturers are generating additional demand.
A positive aspect of the work ethic of many Mexicans lies in their exceptional productivity and their willingness to work long hours to complete their tasks. In modern industrial environments, employees are characterised by a high degree of professionalism and commitment. The Mexican tyre industry, for example, exemplifies a rapidly modernising work culture. It promotes a strong female presence and employs a very young workforce, with 75 percent of employees being under 35 years old. n
Mexico 2026: A Manufacturing Powerhouse Still Seeking To Revitalise Retreading
- By Daniel Rojas Enos
- August 21, 2026
While the tyre and rubber industries are experiencing one of their most dynamic periods thanks to North American integration, the retreading sector continues to face economic, cultural and market challenges in its efforts to regain momentum.
Few Latin American economies currently occupy as strategic a position within the global tyre industry as Mexico. The combination of manufacturing capacity, geographic proximity to United States and the advantages provided by the United States-Mexico-Canada Agreement (USMCA) has consolidated the country as one of the leading tyre and rubber manufacturing hubs in the region.
In recent years, US trade policies directed at producers located outside North America have further strengthened this position. Investment relocation, nearshoring strategies and the need to secure regional supply chains have created particularly favourable conditions for Mexican industry.
The effects are visible throughout the value chain. Tyre manufacturers, rubber compound producers and raw material suppliers are operating at high activity levels, largely driven by demand from the US market. Industry stakeholders consistently point out that the current challenge is not finding customers but maintaining sufficient capacity to meet North American demand.
The rubber compound industry is perhaps one of the clearest examples of this trend. Benefiting from the regional trade environment, many companies are operating close to full capacity, supplying tyre manufacturers as well as other rubber-related industries. A similar situation can be observed among several retreading material suppliers, whose primary concern is not local demand but their ability to meet growing requirements from United States.
Yet, while manufacturing is experiencing a period of expansion, the retreading sector faces a very different reality.
The paradox is striking. In a country that markets more than 40 million tyres annually and possesses one of Latin America’s strongest industrial platforms, retreading has not been able to regain a sustained growth trajectory.
During his presentation at the Latin Tyre & Auto Parts Expo Panama 2025, Juan Carlos Hernández, then Commercial Manager of Hules Banda, presented figures that help illustrate the scale of the challenge. According to the data presented, Mexico marketed more than 40 million tyres during 2024, with an estimated potential of over five million tyres suitable for retreading. However, only around 960,000 units were actually retreaded, representing a retreading rate of approximately 18 percent.
The figures become even more revealing when analysing installed capacity utilisation. While tyre factories report average idle capacity levels close to 14 percent, retreading plants operate with approximately 70 percent idle capacity. Furthermore, during the first months of 2025, retread production showed a decline of nearly 9 percent compared to the previous year.
The reasons behind this situation appear to be less related to technical capabilities and more connected to the economic incentives currently shaping the market.
The growing presence of low-cost imported tyres has significantly transformed purchasing decisions across many fleets. According to Hernández’s presentation, nearly 40 percent of the radial truck tyre market consists of Asian products sold for less than USD 150 per unit. As a result, the economic gap between purchasing a low-cost new tyre and investing in a retread has narrowed considerably for many operators.
In this context, measures such as tariffs on selected imported products have so far failed to generate significant structural changes in market behaviour or retreading activity levels.
However, attributing the situation solely to pricing would be an oversimplification.
One of the most interesting observations highlighted by Hules Banda points to a less visible but potentially more significant long-term issue: the gradual loss of tyre management culture.
For decades, retreading formed part of a comprehensive asset management strategy, where tyres were managed throughout multiple life cycles in order to maximise cost per kilometre performance. Today, in many segments of the transport industry, that approach has increasingly been replaced by purchasing decisions focused primarily on immediate acquisition costs.
The result has been lower casing utilisation, fewer maintenance and monitoring programmes and increasing difficulty in demonstrating the long-term economic benefits that have historically supported the retreading business model.
Paradoxically, those segments that continue to manage tyres as strategic assets still demonstrate the relevance of retreading. Fleets operating premium and medium-tier tyres remain highly dependent on retreading to optimise operating costs, improve profitability and maximise asset utilisation.
CIRCULAR ECONOMY BEYOND END-OF-LIFE TYRES
Another issue deserving attention is the way the circular economy debate is currently evolving within Mexico’s tyre sector.
Much of the public and regulatory discussion focuses on end-of-life tyres (ELTs), collection systems, reverse logistics and recycling or recovery solutions once the product reaches the end of its useful life. By contrast, strategies aimed at extending product life through reuse often receive considerably less attention.
This is particularly relevant given that internationally recognised circular economy principles establish a hierarchy in which extending product life generally delivers greater environmental value than interventions applied after a product becomes waste.
From this perspective, retreading represents one of the most tangible examples of circularity within the tyre industry, as it preserves the economic, material and energy value embedded in the original casing for a longer period.
Mexico will undoubtedly remain one of the leading players in the North American tyre industry. The strength of its manufacturing sector appears well supported by regional integration, industrial investment and strong demand from United States.
The question that remains is whether the retreading sector will be able to become fully integrated into this growth story.
The industrial capacity exists. The technology is available. Premium market segments continue to require strategies focused on maximising cost per kilometre performance. The challenge appears to lie elsewhere: rebuilding tyre management culture and repositioning retreading as a strategic tool for competitiveness, efficiency and circular economy performance.
At a time when much of the discussion focuses on managing tyres at the end of their life, perhaps the more important question is how to ensure that life lasts longer in the first place.
I can still vividly remember a journey I made in 1995 with my young Kenyan MD (who is no longer living) in a hired car from the Delhi Airport to some town close to Ludhiana to meet a tyre moulding machinery supplier. The travel was through vast expanses of paddy fields extending to miles, and in between, we could see large industrial sites far away. A clear sign of industry and agriculture co-existing synergistically. When passing the area called Kurukshetra, the driver mentioned that there was a war at this area a long time ago. He was obviously referring to the great war of the epic Mahabharata, a subject which still generates ample curiosity in me even at this advanced age. With growing years of maturity, I am more convinced that the great war symbolically and semantically depicts the inner conflicts going on in our own minds, while these are conventionally polarized as ‘black and white’ under the ‘all- or- nothing’ principle, and Kurukshetra represents our own hearts and intellect, commonly called the emotional brain and intellectual brain in today’s jargon. Equipped with my industry experience acquired for nearly six decades, I am tempted to make a rather feeble effort to understand what has changed in the managerial mind map over the past 50 odd years. It would be similar to finding parallels between the Vietnam War in the late sixties and current war going on in the Middle East, despite the common factor, US.
Quite in contrast to machinery and materials, the man component of the traditional 4Ms is the most confusing area despite the vast research that has been carried out over the years. It is said that the adult human brain consists of about 86 billion neurons, an astronomically high figure compared to memory capacity of the modern computers. Over the past few decades, the modern managerial mindset has undergone profound transformations. Managers today, particularly in the age group of 35 to 50 ( Gen X), operate in an astonishingly different scenario compared their counterparts 50 years ago. The two eras are fundamentally different and attempting to compare them is largely futile. The rapid changes, technologically, culturally, socially and psychologically, are so vast that today’s managers are shaped by globalisation, digitalisation and fierce competition, which has significantly altered their cognition, thinking patterns, values and behavioural approaches.
While most living managers of the older generation adopt a stance of lamenting about the ‘’good old times’, I think it would be more prudent to understand the realities of change. Management philosophies have undergone profound change, evolving from Taylor’s scientific management and Fayol’s top-down framework based on five key managerial functions to the humanistic approaches advanced by Carl Rogers and Maslow. This is the universal feature of impermanence of all conditioned phenomena (cause-effect related), discovered more than 2,600 years ago by Lord Buddha and some Greek and other Eastern philosophers. Endeavoring to maintain stability, in an ever-changing world scenario, has been the driver for the emergence of management concepts and theories, including the latest approaches seen in the contemporary modern world. Comparing modern managers with those from 50 years ago is unrealistic because of the complete change in the context. Earlier managers operated in stable and localised economies, while modern managers operate in a dynamic globalised environment. It is sometimes said that ‘when the President of the United Sates sneezes, the Eastern leaders catch a cold’, a fact amply demonstrated by the recent events.
Decision-making in the past was slow and experience-based, while today it is data driven, rapid and technologically assisted. Traditional management emphasised relationships, loyalty and progressive and gradual growth, while modern systems emphasise on performance metrics and quick results, like the instant coffee.
The growing corporate trends due to industrialisation over the past 30 years especially has witnessed increased focus on productivity, efficiency and outputs along with standardisation, which has made workers and managers becoming a part of a mechanised system. Modern corporate managerial thinking is also been heavily influenced by globalisation, due to exposure to international competition and the need to adapt to diverse cultures and markets and the pressures to meet global benchmarks and standards. The constrains and the stresses imposed on countries such as Sri Lanka is tough in these areas. A good example is the EUDR requirements, which initially was a nightmare to the rubber product manufacturing companies. A far more serious non-technical consequence is that the concept of a ‘global village’ is eroding values of the strong cultural and ethical foundation, leading to identity dilution among managers
During my association with the industry, particularly over the past 20 years, I have personally witnessed decline of the traditional values in the modern managerial mindset. This is also seen in some professional associations in which I have been a member for a long time. Some of the key trends noted are as follows:
a) Limited understanding and low priority given for religion, history and cultural heritage.
b) Reduced emphasis on ethics, empathy and social responsibility despite the fact that this has become a ‘catch word’ in most corporate circles.
c) Over reliance on technical knowledge and digital skills.
d) Decline in the respect for elders and their experience (crystallised knowledge)
e) Over confidence due to access to information, which brings forth a ‘know it all ‘stance.
f) Diminished openness to learn from others.
g) Difficulty in accepting criticism and feedback
While these tendencies directly affect workplace relationships, team cohesion and leadership effectives, the hidden or latent consequences have more deeper implications on personal and social wellbeing.
The Buddha in one of the discourses has observed that a person can victoriously face a battle against an army of elephants, horses, chariots and infantry by having the necessary resources, but it will be more difficult to win the war within due to mental conflicts.
Most business environments are characterised by aggressive target setting, continuous performance evaluations and competitive organisational cultures, which has caught the managers in a perpetual rat-race where success is narrowly defined by targets and profits while there is hardly any time for reflection or personal growth. This creates a certain emptiness and dissatisfaction even among the high achievers.
I find it interesting at this juncture to refer to the historic concept of Sigmond Freud (considered as the founder of Psychoanalysis), the structural components of the mind, namely Id (pleasure principle or gratification), Ego (reality principle) and the Super Ego (ethical and moral conscience). In order to minimise the negative impacts of the conflicts between them, the Ego resorts to defence mechanisms, or temporary coping solutions. Some of these are denial of the problem, repression of the feelings, projection of the blame to somewhere else and rationalisation or giving logical but false explanations. While these are useful in the short term, over reliance can interfere with mental functioning and emotional growth. All of us are unconsciously resorting to one or several of these in times of emotional turmoil.
The pressures of modern management have led to an exponential growth in mental health challenges in recent years, which include common mental disorders such as stress, anxiety, burnout, depression and features associated with Borderline Personality traits (emotional instability and impulsivity), which result in work-life imbalance and chronic dissatisfaction.
Due to the high psychological demands, there is a growing need for career and workplace counselling. Counselling is a relatively new term that came into prominence around the mid-20th century, before which guidance and support was traditionally provided by the religious institutions, parents, teachers and the elders in the society. Over the recent years, counselling has evolved as a unique profession. Many organisations, especially the larger ones due to the seriousness and gravity of the problems they experience, have established counselling as a regular activity performed in-house or outsourced. Counselling helps managers to cope up with stress and expectations, supporting emotional regulation and resilience and enhancing self-awareness and interpersonal skills, which results in reconnecting purpose and meaning and balancing professional and personal life to develop a healthier mind set. The modern managers must endeavour to have a balanced mind set which is an integrated mix of technical competence, human values, cultural awareness and emotional intelligence and wellbeing. Only then they can move beyond being mere ‘cogs in a wheel’ and become holistic, effective and ethical leaders in the modern world
It is somewhat ironic that Human Resource Sustainability is not named as a single standalone goal in the United Nations Sustainable Development Goals (SDGs) but covered under several headings such as Good Health and Wellbeing, Quality Education, Gender Equality, Decent Work, Economic Growth and Reduced Inequalities.
While I do not have firsthand information on how human resource counselling is caried out in other countries, my observations and experience in Sri Lanka is that it is done more in a fire fighting or reactive mode, where corrective and remedial measures are taken only in cases of psychological deviances. It is somewhat surprising because Sri Lanka is famous for its preventative public health care in pre and postnatal maternity health and school dental health. Industry safety and health is fairly well addressed in most large, medium and some small enterprises, although these are mainly covering the operational levels. Currently, several standard stress, anxiety and depression measuring scales, both qualitative and quantitative, are available, but they do not seem to be used proactively to detect the cinders underneath the ash. People in emotional distress invariably need to vent their thought and emotions, which causes several cognitive distortions and mental disorders. Active and empathetic listening plays the major role in a therapeutic counselling relationship
Coming back to the Mahabharata, the classic instance of counselling for a person in deep emotional conflict and inner war is the Bhagwat Gita, and all of us will need Lord Krishnas in different disguises at some stages in our lifetimes.
It is interesting how Buddha has adopted an integrative approach to the four aspects or components of wellbeing for human progress as:
- Physical wellbeing
- Mental wellbeing
- Social wellbeing
- Spiritual wellbeing
The author is a Management Counsellor from Sri Lanka.
Comments (0)
ADD COMMENT