Azur’s Blueprint For A Circular Tyre Industry
- By Gaurav Nandi
- September 11, 2026

Europe’s tyre industry stands at a crossroads as mounting regulatory pressure, resource constraints and circular economy targets reshape the end-of-life tyre landscape. Despite Germany achieving one of the world’s highest recycling rates, an estimated 100,000 tonnes of used tyres continue to leave the country annually, undermining domestic recovery efforts. In conversation with Tyre Trends, AZuR Network Coordinator Anna-Maria Guth outlines the policy reforms, recycling technologies, retreading opportunities and cross-border collaboration needed to keep valuable raw materials in circulation and build a fully circular European tyre ecosystem.
What gaps in the traditional tyre value chain led to the establishment of the AZuR network?
In Germany, we have a very high recycling rate for end-of-life tyres. However, following a merger of certified tyre disposal companies that collect and sort tyres, it became clear that we needed to bring all stakeholders together to really make progress. The excellent response to the AZuR network shows that this is the right approach.
The European tyre industry is under increasing pressure regarding emissions, waste management and the circular economy. What policy measures are still needed to accelerate the widespread adoption of tyre recycling?
Couple of policy implementations must be achieved in order to reach this goal. The first is a strict ban on the export of ELTs and rigorous enforcement of this regulation. Secondly, clear, predictable and statutory regulations regarding the use of ELT granulate. Lastly, consistent implementation of circular economy strategies.
 What role can recovered carbon black (rCB) play in reducing Europe’s dependence on primary fossil raw materials?
The pyrolysis companies in the AZuR network are making great strides in improving the quality of rCB. We are optimistic that in the foreseeable future, we will be able to produce a grade that allows the material to be incorporated into new tyres in larger quantities. That would be a major breakthrough and would create real added value as it would keep the raw materials within the circular economy.
How does AZuR distinguish between mechanical recycling, devulcanisation and pyrolysis in terms of sustainability and scalability?
Within the network, we adhere to the European waste hierarchy viz-a-viz prevention, reuse, recycle including mechanical and chemical and, finally, thermal recycling.
We are open to all technologies when it comes to processes. However, it is clear that in the interests of the circular economy, we want to minimise thermal recovery. And this also applies to pyrolysis oil provided it is not used for the production of new products but as a secondary fuel.
How close is the tyre industry to establishing tyres made with recycled materials without compromising on performance?
Some manufacturers are already field-testing tyres containing over 70 percent recycled and bio-based raw materials. The industry is very active in this area. However, we would like to see a more nuanced approach to recycled materials and bio-based materials.
Bio-based materials cannot be the solution in the medium term and the EUDR is already restricting the use of bio-based materials in Europe. Our focus must be more on recycled materials and their qualities so that raw materials can be kept in the cycle.
More than 500,000 tonnes of end-of-life tyres are generated in Germany every year. What are currently the biggest bottlenecks in the infrastructure for collection, sorting and processing?
At present, the SME sector in Germany is structured in such a way that all tyres generated can be collected, sorted and processed. Our biggest challenge is that the material is currently being exported rather than ending up with responsible companies in the circular economy. We estimate that around 100,000 tonnes are exported annually without proper regulation.
How will the network influence future EU regulations on the circular economy?
We are delighted to be engaging in growing dialogue with EU bodies, which enables us to raise the profile of the circular economy, which is dominated by small and medium-sized enterprises. Our aim is to set the right course at European level as quickly as possible so that companies can work successfully with the materials and keep as many raw materials as possible in the cycle.
Which groundbreaking technologies or business models are currently attracting the most attention?
There are quite a few, and to name just a few, we have companies in the network working on AI-driven solutions for tyre sorting as well as start-ups producing devulcanised materials for the new tyre industry or AI-assisted machines for the professional regrooving of truck tyres.
How important is cross-border cooperation in establishing a sustainable circular economy for tyres across Europe, rather than in isolated national markets?
AZuR started as a German network, but we can now safely say that we have become a European network. We have partners from Italy, the Netherlands, Austria, Ukraine, Estonia and Poland. All these countries face similar challenges as the relevant legislation is often decided at European level and we can achieve very little at national level. We can only take the big steps together in Europe.
How difficult is it to reconcile economic interests within such a diverse ecosystem?
All AZuR partners are united by a shared vision of 100 percent recycling of end-of-life tyres generated in Europe. We know that this is economically viable. However, we also know that we can only tackle the hurdles that are currently preventing us from reaching our goal by working together.
Our target of 100 percent recycling of end-of-life tyres is very realistic and, in our view, can be achieved in the short term with the right measures.
How do you respond to the market’s ongoing concerns regarding the safety, quality and performance of retreaded tyres?
The retreaders currently operating in Germany are industrial retreaders whose quality standards are in no way inferior to those of new tyre manufacturers. Real-world use shows that there are no quality limitations with retreaded tyres. When retreaded, the casings from premium manufacturers offer a quality comparable to that of the original new tyre.
Incidentally, the safety of the technology is demonstrated by retreaders of aircraft tyres as such tyres are retreaded 12 to 14 times and are highly relevant to safety. And retreading is the ideal solution for recycling as it allows the tyre to be used a second and third time as a tyre.
Why has retreading uptake in the passenger car sector remained relatively limited compared to that in the commercial vehicle sector?
One of the major challenges facing retreading in the passenger car sector is the vast variety of sizes, which makes retreading economically unviable. We are constantly seeking dialogue with vehicle manufacturers on this issue.
Furthermore, passenger car tyres are often in use for longer because they are driven less frequently, meaning fewer casings are available for retreading. However, we believe in passenger car tyre retreading, particularly given the growing share of electric vehicles, and are delighted that a retreader in Germany will be relaunching operations in this segment this year.
How important will AI, predictive analytics and sensor-based tyre management become over the next decade?
Smart tyre management is both an economic factor for haulage companies and an environmental one. We know that how a tyre is used has a significant impact on its service life. And at the top of the waste hierarchy is waste prevention. Here, both the new tyre industry and users are called upon to make optimal use of tyres so that they can remain in service for as long as possible.
What would success look like for AZuR in the next five years?
We would have reason to celebrate if we were to achieve the following key objectives in the coming years. The objectives include 40 percent market share for retreaded lorry tyres in Europe, 10 percent market share for retreaded passenger car tyres in Europe, 100 percent recycling of end-of-life tyres in Europe and clear legal regulations governing the use of recycled ELTs.
- Association of Natural Rubber Producing Countries
- ANRPC
- Monthly NR Statistical Report
- Natural Rubber
ANRPC Publishes Monthly NR Statistical Report For August 2026
- By TT News
- October 02, 2026
The Association of Natural Rubber Producing Countries (ANRPC) published its Monthly Natural Rubber Statistical Report for August 2026, noting firmer prices in several markets. Supply constraints, stable downstream demand and persistent geopolitical and macroeconomic uncertainty shaped the month. Renewed conflict and disruptions to major shipping routes added further pressure.
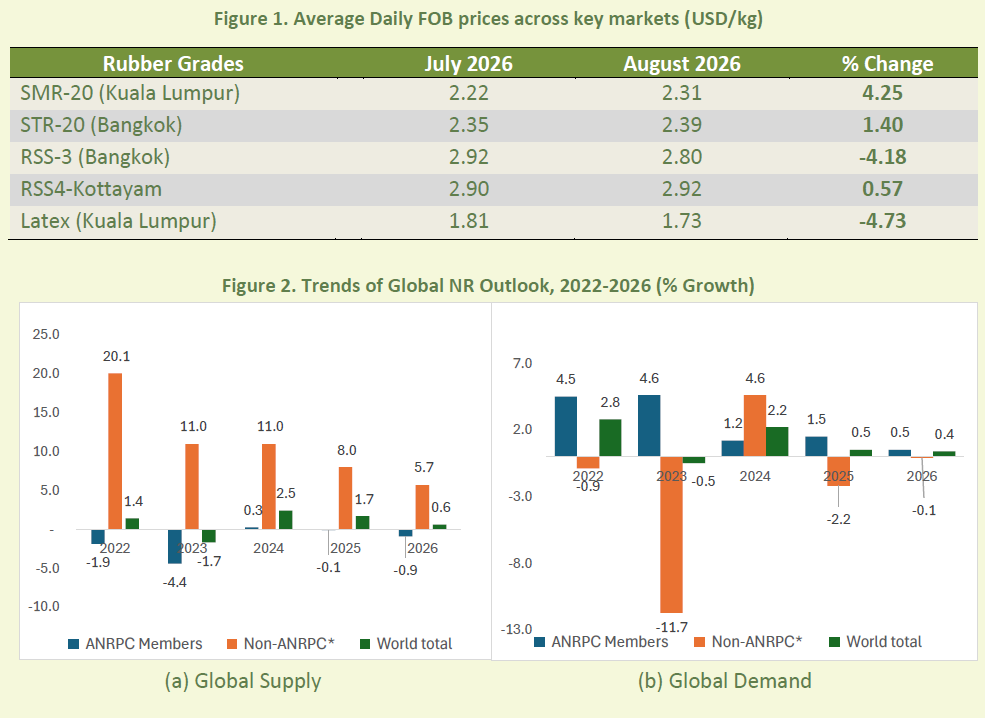
Physical prices for major grades moved in different directions. SMR-20 in Kuala Lumpur averaged USD 2.31 per kg, up 4.25 percent from July, while STR-20 in Bangkok rose 1.40 percent to USD 2.39 per kg. RSS-3 dropped 4.18 percent to USD 2.80 per kg, but RSS-4 in Kottayam gained 0.57 percent to USD 2.92 per kg. Latex-in-bulk fell 4.73 percent to USD 1.73 per kg. Brent crude averaged USD 91.08 per barrel, driven by concerns over possible restrictions on oil shipments through the Strait of Hormuz and wider Middle East instability, which raised energy supply risks and strengthened the oil market risk premium.
On trade, China's imports climbed 3.39 percent month-on-month, while India fell 10.18 percent and Malaysia dropped 8.24 percent; Viet Nam rose 5.08 percent. Exports advanced 5.63 percent in Viet Nam but declined in Thailand (-5.24 percent), Indonesia (-5.36 percent), Malaysia (-1.48 percent) and Cambodia (-1.88 percent).
Global production is projected to rise 0.6 percent to 15.039 million tons in 2026 from 14.952 million tonnes in 2025, after revisions to Thailand's 2025 output and updated 2026 estimates for Thailand, Malaysia and Indonesia. Weather, including erratic rainfall and drier Southeast Asian conditions, affected output. August 2026 production was estimated at 1.396 million tonnes, down 4.51 percent from 1.462 million tonnes a year earlier. Demand is forecast to grow 0.4 percent to 15.356 million tonnes in 2026 from 15.301 million tonnes, with the largest consumption gains expected in China, Malaysia and Cambodia. Prospects depend on vehicle sales, tyre production, shipping conditions and weather-related supply disruptions, while steady EV-linked demand supported modest growth led by China and India. The ringgit traded between RM4.02 per USD and RM4.09 per USD, and the baht between 32.68 and 33.34. The SHFE January 2027 contract averaged 18,109 CNY per tonne, up 7.78 percent month-on-month, while the SGX November 2026 contract averaged USD 2.24 per kg, up 4.32 percent.
HS HYOSUNG To Expand Mexico Investments From 2027 Under New State Agreement
- By TT News
- September 30, 2026
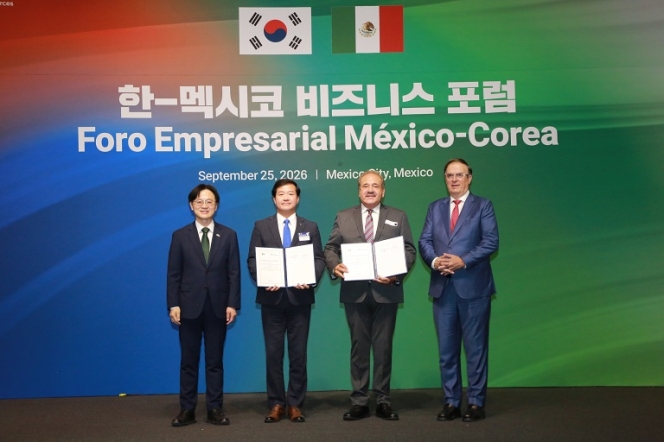
HS HYOSUNG has formalised a memorandum of understanding (MoU) with the State Government of San Luis Potosí, with the signing taking place at the World Trade Center Mexico City. The event formed part of the Korea-Mexico Business Forum, held alongside the Korean economic delegation's visit to Mexico.
Attending officials included Marcelo Ebrard, Mexico's Secretary of Economy, and Mario García Valdez, Secretary of Economic Development of San Luis Potosí. The two sides confirmed their shared resolve to back the company's local investment and regional growth. Separately, HS HYOSUNG's leadership met bilaterally with Secretary Ebrard to elaborate on its strategic vision and investment plans.
The agreement sets out a phased expansion of HS HYOSUNG's investments in San Luis Potosí beginning in 2027, with the goal of creating a major advanced materials production hub that bolsters supply for North American and wider global markets. The company's advanced materials span tyre cord, a flagship world-leading product, along with mobility, energy, aerospace and defence applications. Its North American operations, spanning Mexico and the United States, turn out tyre cord, airbag materials and mobility interior components for global leaders such as General Motors and Goodyear, underpinned by a highly dependable global supply chain.
Nak-yang Sung, CEO, HS HYOSUNG ADVANCED MATERIALS, said, “This investment goes beyond establishing a simple manufacturing base – it reflects our strategy to turn Mexico into a pivotal hub connecting North America with global supply networks. We are also committed to strengthening local supply chains and creating high-quality jobs to contribute directly to the region's industrial ecosystem.”
Kumho Petrochemical Group Shifts Focus To R&D and Speciality Materials
- By TT News
- September 25, 2026
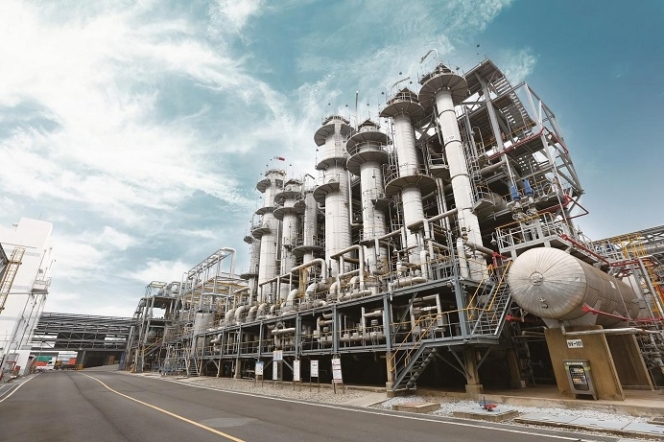
Kumho Petrochemical Group is steering its business towards research-driven, higher-value outputs as oversupply and soft demand continue to weigh on the worldwide petrochemical sector. The Seoul-based group outlined plans to boost spending on speciality chemicals, sustainable materials and novel production methods, a push intended to lift profits while building a foundation for future expansion.
Underlying the move is a deliberate evolution in the group's identity, from a bulk materials vendor to a provider of technology-backed solutions that address shifting customer requirements and stricter environmental rules. A central element of that effort involves widening the speciality lineup, exemplified by added capacity for solution styrene butadiene rubber, a synthetic rubber that enhances durability, rolling resistance and tread wear in high-performance electric vehicle tyres.
Environmental initiatives form another pillar. Facilities built by the company can trap approximately 76,000 metric tonnes of carbon dioxide each year, while separately developed technology turns recycled acrylonitrile butadiene styrene sourced from scrapped household appliances into automotive-grade interior components that satisfy performance standards and generate fewer emissions than conventional methods. The group has also joined forces with POSCO Future M and BEI on anode-free lithium-metal battery development.
Parallel technology-focused programmes are underway at affiliated units. Kumho P&B Chemicals is formulating water-based epoxy resins that curb volatile organic compound releases while incorporating more bio-based inputs to reduce carbon intensity. Kumho Mitsui Chemicals is advancing bio-based polyurethane systems and electric vehicle materials, alongside debottlenecking work to add 100,000 tonnes of annual methylene diphenyl diisocyanate capacity. Kumho Polychem, meanwhile, is targeting ethylene propylene diene monomer through low-temperature polymerisation paired with energy-efficiency improvements.
Birla Carbon Announces Asia-Wide Speciality Materials Price Hike Of Up To 15%
- By TT News
- September 22, 2026
Birla Carbon has confirmed a price increase of up to 15 percent for its Speciality Materials products across Asia, scheduled to take effect on 1 October 2026. The company pointed to significant and sustained rises in feedstock costs, driven partly by ongoing geopolitical instability and disruptions in global feedstock markets, as the reason behind the adjustment.
Although Birla Carbon pursued operational efficiencies, supply chain optimisation and disciplined cost management to soften the impact, the scale and persistence of the cost escalation left a price adjustment unavoidable. The company's sales teams will engage customers directly to explain the details and help them navigate the transition.
Comments (0)
ADD COMMENT