
Business travel represents a substantial force in the global economy. Just before the Covid-19 pandemic hit, it contributed to more than USD 1.2 trillion, about 25 percent of the travel and tourism sector’s overall economic impact, to the global GDP. Businesses had resumed spending on travel after substantial declines in 2008 and 2009.
A research by Global Business Travel Association Foundation had found that for every one percent change in business travel spending, the US economy typically gains or loses 74,000 jobs, USD 5.5 billion in GDP, USD 3.3 billion in wages and USD 1.3 billion in taxes. The report also stated that personal vehicle (35 percent) was the most popular mode of transportation among US business travellers in 2016, followed by airplane (28 percent) and rental cars (13 percent).
Internal travel encompasses trips taken for intracompany purposes, where employees participate in activities such as training, team building or inspection of field operations. External travel, on the other hand, refers to travel done by employees for engagements outside the company, including in-person meetings with clients and suppliers, trade conferences and customer sales calls.
"Obstacles to business travel, such as cumbersome visa protocols and long flight connections, constrain access to knowhow and limit growth opportunities, especially in developing countries," said Frank Neffke, research director at Harvard Kennedy School’s Growth Lab.
Benefits Of Business Travel
In the past, companies have experienced that, on average, 40 percent of customers would eventually be lost without in-person meetings and support.
Detailed statistical modelling over 18 years and 14 industries indicates that for every dollar invested in business travel, US companies make a USD 9.50 return in terms of revenue. The modelling also found that US business travel has yielded USD 2.90 in profits for every dollar spent.
There is a small segment of employees for whom travel is deemed essential for conducting business. This category accounted for around 15 percent of all corporate travel expenses in 2019 and includes decision makers in manufacturing companies with a wide distribution of factories and plants, and field-operation workers. For some corporate travellers, it is possible to move oversight responsibility to local personnel and/or utilise digital medium. This segment will see their business travel decline. A large segment of business travel is done to cultivate new or important client relationships. This segment will bounce back as soon as Covid-related restrictions are lifted.
A tiny portion of business travel comes from the public sector, professional associations and nonprofits. During the pandemic, many professional associations were able to hold virtual events to replace in-person conferences and will likely be more cautious in their return to travel.
Business Travel Catches The Virus!
Business travel has taken a big hit during the Covid-19 pandemic and its future is still up-in-the-air, waiting for the end of the pandemic and firming up the ‘New Normal’. In 2020, total global business travel expenses contracted by 52 percent, while managed corporate-travel spending in the United States alone plummeted by USD 94 billion (71 percent).
The World Travel and Tourism Council’s (WTTC) latest annual research shows that the global travel and tourism sector suffered a loss of almost USD 4.5 trillion to reach USD 4.7 trillion in 2020, with its contribution to GDP dropping by a staggering 49.1 percent compared to 2019. In 2020, sixty-two million jobs were lost, representing a drop of 18.5 percent, leaving just 272 million employed across this sector globally, compared to 334 million in 2019. The threat of job losses persists as many jobs are currently supported by government retention schemes and reduced hours, which could be lost without a full recovery of the travel and tourism sector.
Some business travellers expect to take at least as many business trips in 2022 as they had in the year before the Covid-19 pandemic was declared. While teleconferencing will reduce the need for some business travel, many survey respondents cited the need to meet in-person to rekindle relationships with customers, suppliers and business partners. Another frequent reason cited for the need to travel for business was a job change.
The countries most eager to travel for business once Covid-19 travel restrictions are lifted seem to be China, US and Australia. Of course, the potential increase in Covid cases from the Delta and future variants of the virus may still cause further backsliding on rising confidence levels for resumption of business travel. (TT)
Sun Auto Network Taps Interstate Batteries As Primary Battery Supplier
- By TT News
- October 15, 2026
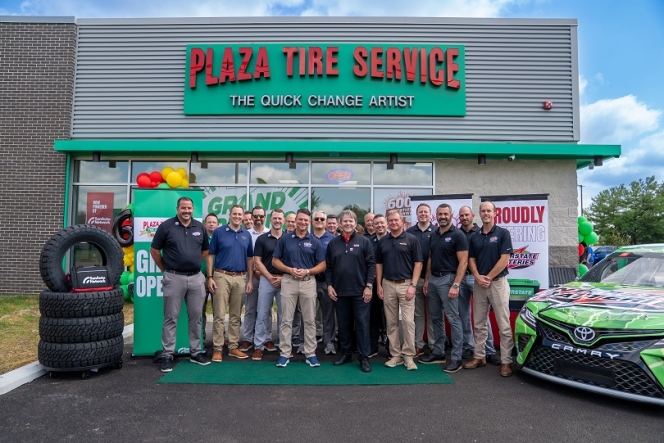
Sun Auto Tire & Service has entered a strategic partnership with Interstate Batteries, designating the company as the primary battery provider for the Sun Auto Network. The announcement marks a significant development for one of United States’ largest independent automotive service providers.
Operating over 600 locations across 27 states, the Sun Auto Network encompasses more than 70 local and regional automotive service brands. This partnership represents another step in Sun Auto's ongoing efforts to strengthen operations and enhance customer experience through leading category partners.
Interstate Batteries, a battery specialist with national scale and strong consumer awareness, brings dedicated category expertise, marketing resources and nationwide support to the network. The company's products are now available at Sun Auto locations nationwide, combining Sun Auto's growing service footprint with Interstate's specialised expertise and distribution capabilities to create greater consistency in product availability, promotions and warranty support.
With over 70 years of industry presence, Interstate Batteries is recognised as one of North America's most trusted consumer battery brands. Sun Auto locations will support Interstate's warranty coverage, offering customers convenient access to warranty service across the network. The partnership advances Sun Auto's broader strategy of leveraging national network strength to improve products, resources and support for its local brands.
Tony Puckett, Chief Executive Officer, Sun Auto Network, said, "As we grow the Sun Auto Network, we're continually looking for ways to use our scale to make our local brands stronger and deliver more value to our customers. That means aligning with partners who bring deep expertise in their category and can support us consistently across the country. Interstate Batteries brings a trusted brand, specialised battery expertise and nationwide capabilities that make them a strong fit for our network and the customers we serve."
Lain Hancock, President and Chief Executive Officer, Interstate Batteries, said, "Interstate Batteries is proud to partner with Sun Auto Network and serve one of the nation's largest automotive service networks. Sun Auto's scale, customer-first approach and commitment to excellence make them an ideal partner. This agreement creates an exciting opportunity to support more than 600 locations operating under trusted local brands while ensuring drivers have access to dependable battery solutions wherever they travel."
Lassa Launches Snoways 5 And Competus Winter 3 Tyres For 2026 Winter Season
- By TT News
- October 15, 2026
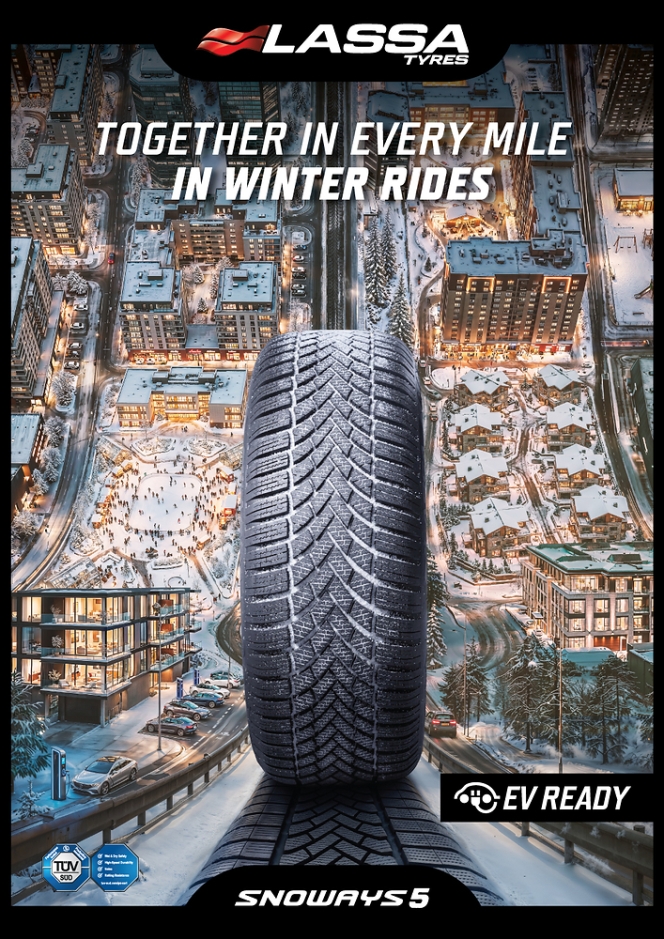
Lassa Tyres has launched its new Snoways 5 and Competus Winter 3 winter tyres to address shifting demands across passenger car and SUV markets. Both products carry the company's EV Ready designation, confirming their compatibility with electric, hybrid and conventional vehicles. The Snoways 5 has additionally secured the TÜV Performance Mark, recognising its strength in key winter and wet handling criteria.
Designed for improved control on snowy and wet surfaces with enduring performance, the Snoways 5 surpasses its predecessor in snow, wet and wear results, as verified by independent TÜV testing. It also improves its rolling resistance label by one grade, cutting energy loss for more efficient driving. TÜV SÜD testing found measurable gains over the competitor average in snow acceleration, snow braking, lateral snow grip, aquaplaning, wet braking and lateral wet grip, alongside lower rolling resistance. Notable improvements include roughly 4 percent better aquaplaning and 3 percent gains in both snow acceleration and lateral snow grip.
The Competus Winter 3 brings this winter design to SUVs, tailoring the Snoways 5 pattern and technologies for larger, heavier vehicles. It offers assured braking and controlled handling on snow and wet roads, with next-generation winter technology delivering stronger snow and wet performance plus greater fuel efficiency. Its EV-Ready construction suits electric and hybrid SUVs while keeping drivers confident throughout winter.
Lassa has expanded its winter range in response to growing demand for larger rim sizes. Snoways 5 comes in 46 sizes spanning 15 to 21 inches, while Competus Winter 3 offers 42 sizes from 16 to 21 inches. This brings European passenger car and SUV winter fitment coverage to 84 percent, with 18-inch and larger fitments reaching 75 percent. Both tyres will launch across Lassa markets for the 2026 winter season.
- AZuR Chemical Recycling Project Group
- AZuR Network
- End-Of-Life Tyres
- Tyre Pyrolysis
- Recovered Carbon Black
- Tyre Pyrolysis Oil
- Pyrolysis Gas
New Research Quantifies Environmental Benefits Of End-Of-Life Tyre Pyrolysis
- By TT News
- October 15, 2026
New research findings from a doctoral dissertation by Dr.-Ing. Sebastian Bogdahn examine how end-of-life tyres can yield high-quality recovered carbon black (rCB) through pyrolysis while delivering substantial environmental benefits. The work, titled ‘Production and Environmental Assessment of High-Quality Carbonaceous Materials from End-of-Life Tyre Pyrolysis’, was presented in condensed form at an AZuR Chemical Recycling Project Group meeting in Dillingen/Saar on 1 October 2026.
The dissertation tackles how end-of-life tyres can be recovered and recycled to maximise their value. Pyrolysis is identified as a complementary technology that helps close recycling gaps in the circular economy and offers an alternative to fossil-based carbon black, a material that plays a crucial role in determining tyre properties.
In the pyrolysis process, rubber granules from processed tyres undergo thermal decomposition without oxygen, producing three main streams: solid rCB, tyre pyrolysis oil and pyrolysis gas. Previous evaluations of such technologies often separated technical and environmental perspectives, relied on secondary data and lacked standardised methodologies, making findings difficult to compare.
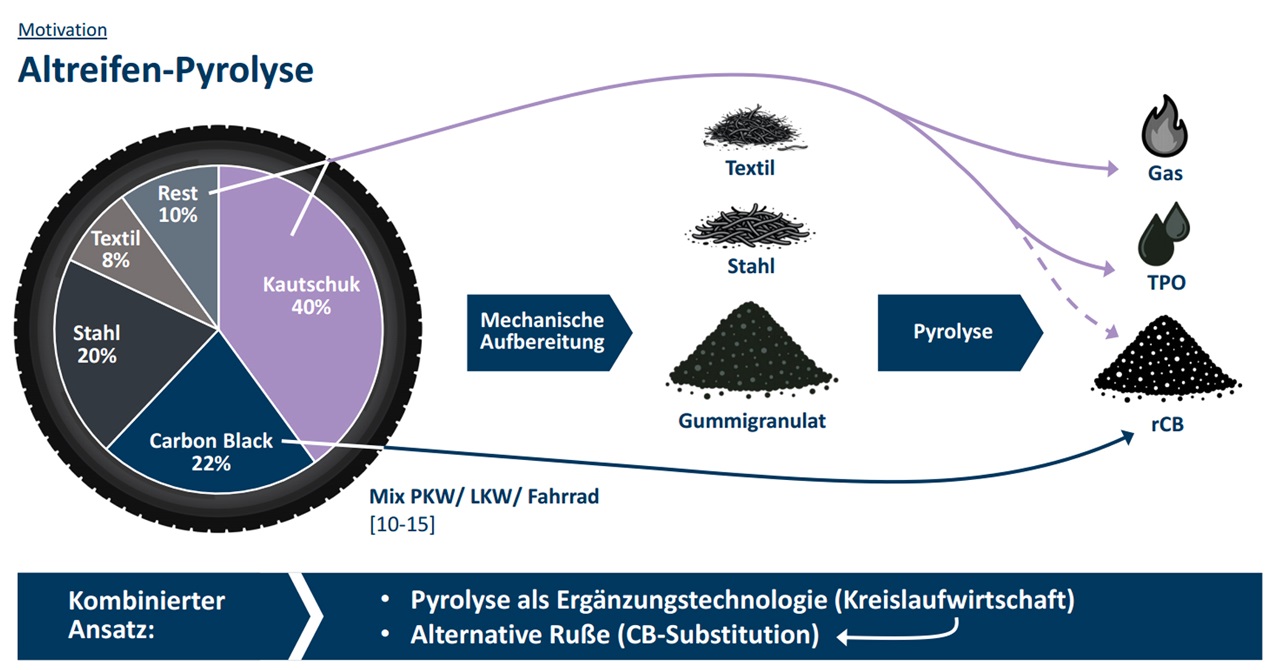
Image credit: Dr.-Ing. Sebastian Bogdahn
Bogdahn overcomes these limitations by integrating a technology-specific process model with a detailed life cycle assessment model. This combination enables a scientifically robust environmental evaluation of pyrolysis and its secondary raw materials using reliable primary data. A central component is a process model that mathematically describes material conversion by combining reaction kinetics, reactor behaviour and mass and energy balances.
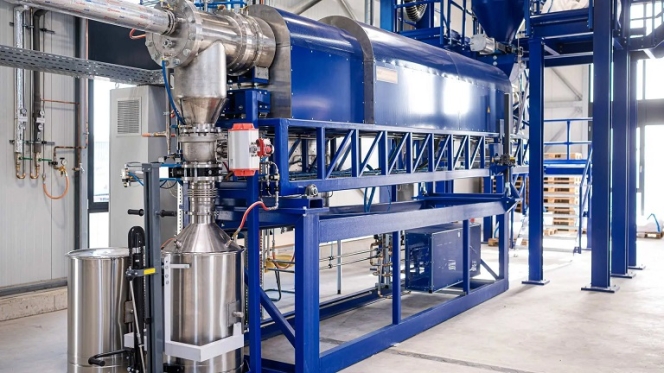
Starting with laboratory-scale experiments, the model was scaled up and validated using a pilot-scale rotary kiln at the Institute of TH Köln. Comprehensive laboratory analyses of feedstocks and products supported development and validation. Optimal conditions for the investigated system were found at 650 degrees Celsius with a residence time of about one hour, achieving complete material conversion and high-quality recovered carbon black. Product distribution was roughly 40 percent rCB, 37 percent TPO and 23 percent pyrolysis gas by weight.
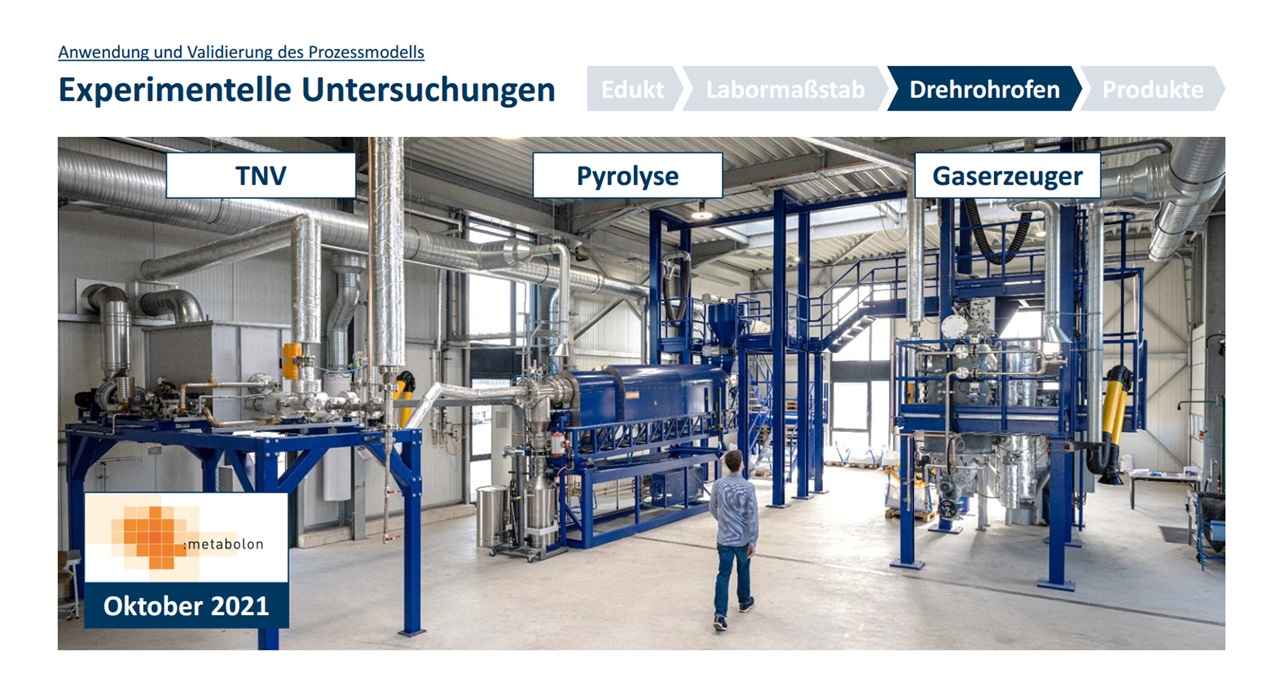
Image credit: Dr.-Ing. Sebastian Bogdahn
Using validated primary data, Bogdahn conducted a comprehensive environmental assessment and developed a methodological matrix covering relevant standards and guidelines to address inconsistent approaches. In the rotary kiln baseline scenario, one metric tonne of recovered carbon black results in a global warming potential over 100 years of about 918 kilogrammes of carbon dioxide equivalents, compared with the International Carbon Black Association’s global industry average of 3,910 kilogrammes for conventional fossil-based carbon black, a reduction of approximately 77 percent. Even after a quality adjustment for lower carbon content, the reduction remains about 70 percent. The study followed ISO 14067 and underwent independent external critical review under ISO 14071, also covering TPO and sustainable carbon black.
Further improvements remain possible. Emissions mainly stem from electricity consumption and gas combustion, with rCB processing accounting for about 44 percent, pyrolysis gas cleaning and combustion about 36 percent and tyre shredding about 19 percent. Sensitivity analysis confirms that renewable electricity offers substantial additional greenhouse gas reductions, reinforcing that a circular economy achieves genuine sustainability only when powered by renewable energy. Enhancing material quality through demineralisation and activation could enable higher substitution rates for fossil-based carbon black.
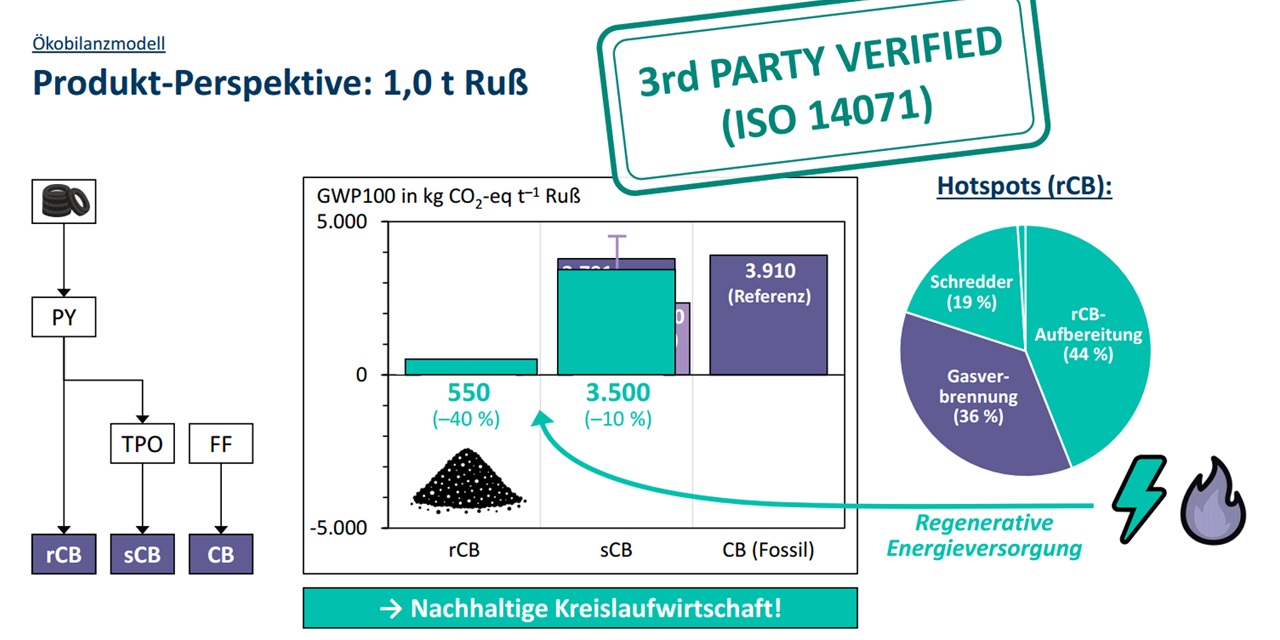
Image credit: Dr.-Ing. Sebastian Bogdahn
A central conclusion extends beyond pyrolysis itself. Raw materials, tyre manufacturing, the use phase and recovery pathways form an interconnected system spanning the entire tyre life cycle, closely linked to the carbon black, chemical, steel and energy sectors. Achieving circularity requires collaboration across systems and industries, along with greater methodological harmonisation and stronger integration of industrial value chains. The AZuR network’s work reflects this need, recognising that extended tyre use, repair, regrooving, retreading, mechanical recycling and appropriate chemical recycling must all function as interconnected elements of the value chain.
Tyres Europe Backs CARUSO Findings As EU Data Act Marks One Year
- By TT News
- October 15, 2026
Tyres Europe, as part of a coalition of 10 European associations representing consumers and automotive and mobility service providers, has issued a joint press release welcoming the latest CARUSO Connected Vehicle Field Test assessing the EU Data Act’s implementation across 29 major vehicle manufacturer groups. The findings confirm the legislation established important principles for accessing vehicle-generated data and encouraged some manufacturers to engage for the first time. One year on, however, the framework remains insufficient alone to enable a competitive, innovative connected mobility market.
Covering 15 automotive use cases across 28 vehicle manufacturer groups, the study concludes that while data access has improved, conditions for competitive, scalable, multi-brand services are still lacking. Access remains fragmented, inconsistent and often commercially or technically impractical across the car parc. Limited third-party access, differences in data scope, quality and coverage, and restrictive commercial terms continue to undermine the business case for innovative services. Genuine multi-brand development remains unattainable, preventing consumers and businesses from fully benefiting from connected mobility.
For many manufacturers, implementation has become a compliance exercise rather than a genuine effort to enable market access. Independent providers face limited datasets, restrictive terms, manual approvals, manufacturer-specific consent mechanisms and inconsistent technical solutions. Such approaches may satisfy the Data Act’s broadly defined obligations but are incompatible with the real-time, automated access modern digital services require.
Strong enforcement matters. Manufacturers respond faster where national authorities investigate complaints and apply enforcement mechanisms. Without consistent, harmonised, proactive enforcement across the European Union, Data Act rights risk remaining largely theoretical for a significant share of Europe’s vehicle fleet.
The coalition urges European Union institutions and Member States to enforce the Data Act consistently, issue clear guidance on fair, reasonable and cost-based compensation and use forthcoming reviews to reinforce rather than weaken it. Dedicated automotive legislation should establish common access conditions, interoperability requirements, initial technical and data delivery standards and safeguards against discrimination. Effective access must cover vehicle-generated data and the in-vehicle functions and resources needed to develop, scale and deliver digital mobility services, enabling fair competition, growth and investment.
According to the coalition, the Data Act was an important first step, but horizontal legislation alone cannot create a workable multi-brand market. Implementation varies widely: of 28 manufacturers, nine (32 percent) have barely implemented the Act; 18 (64 percent) lack adequate third-party pricing; 18 (64 percent) lack adequate data provision; and 19 (68 percent) lack an adequate API solution. Sixteen manufacturers (57 percent) enable none of the use cases, while only nine support the most feasible ones. Without stronger enforcement and dedicated automotive legislation, Europe will fall short of its innovation, consumer choice and fair competition ambitions.
Comments (0)
ADD COMMENT