Challenge Of Change And Business Strategy: Thinking Wide
- By PP Perera
- October 13, 2021
Change and impermanency is the common denominator of all phenomena and processes in nature, which include human activities as well. Heraclitus, the 5th Century BC Greek philosopher, has said that no man can step into the same river twice. This statement from Heraclitus means that the world constantly changes and that no two situations are exactly the same. Just as water flows in a river, one cannot touch the exact same water twice when one steps into a river. This view has been affirmed by Lord Buddha around the same period.
In fact, the challenge of change can be considered as the key driver in all the human endeavours across history and the main motivating factor of business strategies that have evolved through the four industrial revolutions spanning form the mid-18th century to the present day of mass digitalisation. The four principles of change management at any level – be it personal, family, workplace, company or a country – are:
- Understand the change
- Plan the change
- Implement the change
- Communicate the change
Some of the significant contributors to the management of change which resulted in the emergence of new approaches and working models that became popular during the past 50 years can be enumerated as:
- Lewin’s Change Management Model
- McKinsey 7S Model.
- Kotler’s Change Management Theory
- Nudge Theory
- ADKAR Theory
- Bridge’s Transition Model
- Kubler-Ross Five Stage Model
There are many schools of thought around managing organisational change, but there's one thing that's clear. Change managers need to structure their organisational changes and need to avoid 'ad hoc' change management. They need to look at organisational change from a programmatic perspective, leverage subject matter experts around the impacts of change and look at the ‘change beyond the change’.
Corporate change has always been associated with leadership, and Jack Welch, the master of transformational leadership, has once quoted that “good business leaders create a vision, articulate the vision, passionately own the vision and relentlessly drive it to completion.”
Notwithstanding the tremendous utility value of these approaches, I have witnessed the beginning, growth, decline and final exit of some great business empires in Sri Lanka, which could not survive up to the third generation. Similarly, there are exemplary business organisations, the roots of which can be traced back in history to a single person who started with a few rupees and later developed in to corporate giants that are thriving through the third generation. It is therefore apparent that there are no hard and fast norms or standard ground rules, but an emerging factor is the importance of the people at all levels, despite the benefits of automation and digitalisation. Success and failure episodes are abundant throughout the world and corporate graveyards are cluttered with casualties.
Change and business strategy are always closely interlinked without clear boundaries. The ‘Art of War’ – which is attributed to the ancient Chinese military strategist Sun Tzu (around 5th century BC) – remains the most influential strategy text in East Asian warfare and has influenced both Eastern and Western military thinking, business tactics, legal strategy, lifestyles and beyond.
The Covid-19 outbreak, which started around two years ago and developed in to a devastating pandemic, has brought about years of change in the way companies in all sectors and regions do business. The entire world scenario which we currently witness is reminiscent of the opening paragraph of ‘A Tale of Two Cities’, an 1859 historical novel by Charles Dickens.
“It was the best of times, it was the worst of times, it was the age of wisdom, it was the age of foolishness, it was the epoch of belief, it was the epoch of incredulity, it was the season of Light, it was the season of Darkness, it was the spring of hope, it was the winter of despair, we had everything before us, we had nothing before us, we were all going direct to Heaven, we were all going direct the other way – in short, the period was so far like the present period, that some of its noisiest authorities insisted on its being received, for good or for evil, in the superlative degree of comparison only.”
The Coronavirus has rapidly made ‘business as usual’ a phrase from the distant past. There is no ‘usual’ in this uncertain time. But organisations that outmanoeuvre uncertainty create a resilience they can count on, irrespective of the changes that come
. We’ve all changed the way we operate during the Covid-19 crisis. Some changes were forced on us, while others represent the height of innovation in a crisis. There’s been a reset of the workforce and work itself, a reset of the employer/employee relationship and a reset of the business ecosystem. For most of them, the business impact of the pandemic has been negative; for some, positive.
The pandemic may have wiped our strategy slate clean (or at least it feels that way), but we have also garnered invaluable experience. Now it’s time to bring together our executive team and use those lessons to reconfigure the business and operating models for a new reality. It appears that in addition to the conventional 3Rs (reduce, reuse and recycle), with respect to resource consumption and sustainability, a set of new 3Rs, namely respond, recover and renew, has emerged during the Covid-19 crisis.
As we shift from response to recovery, the key for senior leaders is to make strategic decisions that will lead them to a renewed future state, however paralysing the uncertain outlook may seem. We can borrow a leaf from the strategy and tactics of the Covid-19 virus itself in learning how to adapt for survival by adopting new paradigms, namely producing more virulent strains such as the Delta variety.
In the absence of a 100 percent effective vaccine or cure for Covid-19, any rebound in business activity could easily be followed by another round of response, recover, renew; so the imperative is to absorb lessons learned quickly and build sustainable changes into business and operating models.
But first, we need to determine exactly where and how the crisis has stretched and broken our existing models, and where the risks and opportunities lie as a result. When talking about risks and opportunities, I cannot help going back to the basics of ISO 9001:2015 Quality Management System (QMS) requirements which expect a company to evaluate the external and internal issues (Clause 4.1), expectations of interested parties (4.2), determining the risks and opportunities (6.1) and planning for change (6.2). In some of the companies that I happen to audit, the priority given to these is at a minimum or no priority given at all apart from stagnant records which do not show any objective evidence of monitoring and review.
However, one important factor we have to consider is that everyone – irrespective of whether it is an individual, family unit, organisation or a country – is on various stages of their unique learning curves, and the strategic horizons have drastically become shorter. Business and strategy planning is no longer an elite task shrouded with mystery and confined to the corporate managers only in their air conditioned rooms but a task to be accomplished in consultation with those who are finally going to implement the strategies and plans. While the Japanese Genba (the actual place) approach is more than 50 years old, it is mostly confined to operational levels, which is rather unfortunate. This crisis has created an opportunity to reset some of our goals and ambitions; it’s time to ask: “As we recover from this crisis, do we want to be different, and if so, how?”
One can see that many companies are in the recovery mode at the moment and trying to do damage control based on profit motive, which is understandable. The entire social, cultural and ethical models and paradigms have changed drastically, and the entrepreneurs need to realise that they are no longer operating in the pre-Covid era. Drastic changes have occurred in the entire supply and value chains with changing customer preferences.
The following quote attributed to many, including Eleanor Roosevelt, a former First Lady of United States, is appropriate to be cited here:
“There are people who make things happen, there are people who watch things happen, and there are people who wonder what happened.”
Change and impermanency is a fact of life, more so today, and if we do not change, change will change us. After all, it was the mathematical genius of the 20th Century, Albert Einstein, who once observed that:
“Insanity is doing the same thing over and over again and expecting different results.”
We can’t keep doing the same thing every day and expect different results. In other words, we can’t keep doing the same workout routine and expect to look differently. In order for our life to change, we must change – to the degree that we change our actions and our thinking, to the degree that our life will change.
The author a Management Counselor from Sri Lanka
- AZuR Chemical Recycling Project Group
- AZuR Network
- End-Of-Life Tyres
- Tyre Pyrolysis
- Recovered Carbon Black
- Tyre Pyrolysis Oil
- Pyrolysis Gas
New Research Quantifies Environmental Benefits Of End-Of-Life Tyre Pyrolysis
- By TT News
- October 15, 2026
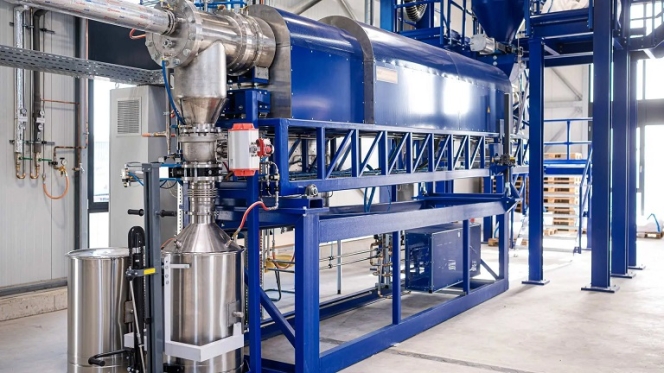
New research findings from a doctoral dissertation by Dr.-Ing. Sebastian Bogdahn examine how end-of-life tyres can yield high-quality recovered carbon black (rCB) through pyrolysis while delivering substantial environmental benefits. The work, titled ‘Production and Environmental Assessment of High-Quality Carbonaceous Materials from End-of-Life Tyre Pyrolysis’, was presented in condensed form at an AZuR Chemical Recycling Project Group meeting in Dillingen/Saar on 1 October 2026.
The dissertation tackles how end-of-life tyres can be recovered and recycled to maximise their value. Pyrolysis is identified as a complementary technology that helps close recycling gaps in the circular economy and offers an alternative to fossil-based carbon black, a material that plays a crucial role in determining tyre properties.
In the pyrolysis process, rubber granules from processed tyres undergo thermal decomposition without oxygen, producing three main streams: solid rCB, tyre pyrolysis oil and pyrolysis gas. Previous evaluations of such technologies often separated technical and environmental perspectives, relied on secondary data and lacked standardised methodologies, making findings difficult to compare.
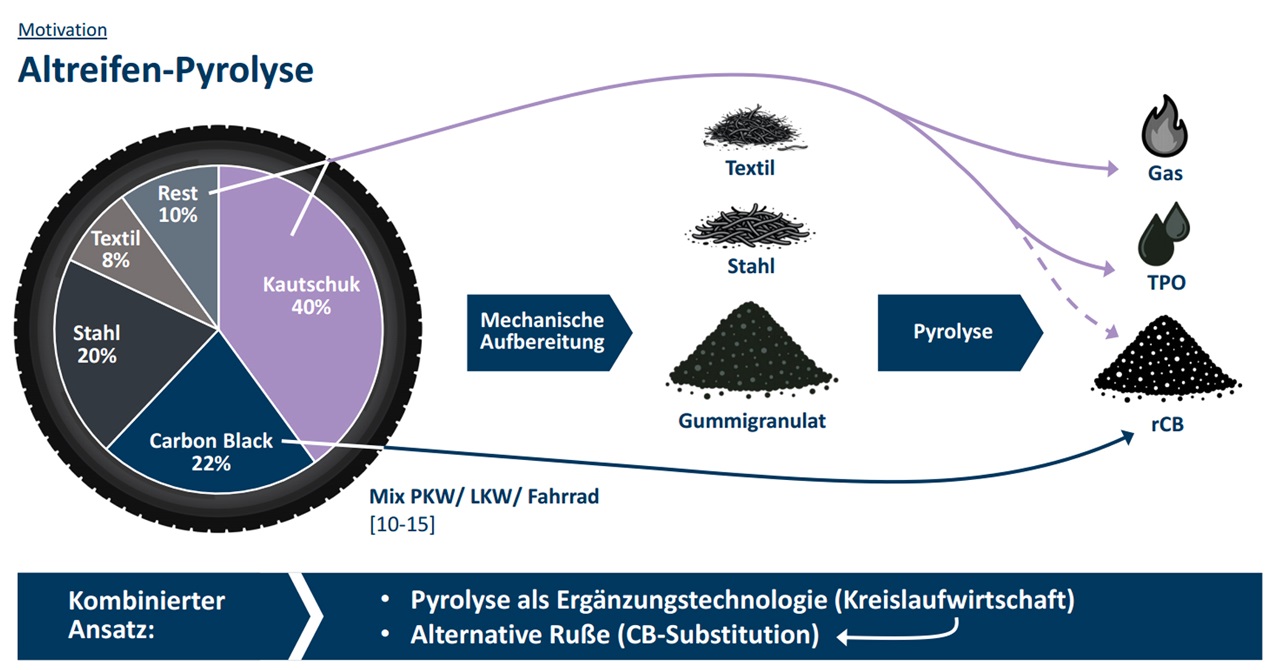
Image credit: Dr.-Ing. Sebastian Bogdahn
Bogdahn overcomes these limitations by integrating a technology-specific process model with a detailed life cycle assessment model. This combination enables a scientifically robust environmental evaluation of pyrolysis and its secondary raw materials using reliable primary data. A central component is a process model that mathematically describes material conversion by combining reaction kinetics, reactor behaviour and mass and energy balances.
Starting with laboratory-scale experiments, the model was scaled up and validated using a pilot-scale rotary kiln at the Institute of TH Köln. Comprehensive laboratory analyses of feedstocks and products supported development and validation. Optimal conditions for the investigated system were found at 650 degrees Celsius with a residence time of about one hour, achieving complete material conversion and high-quality recovered carbon black. Product distribution was roughly 40 percent rCB, 37 percent TPO and 23 percent pyrolysis gas by weight.
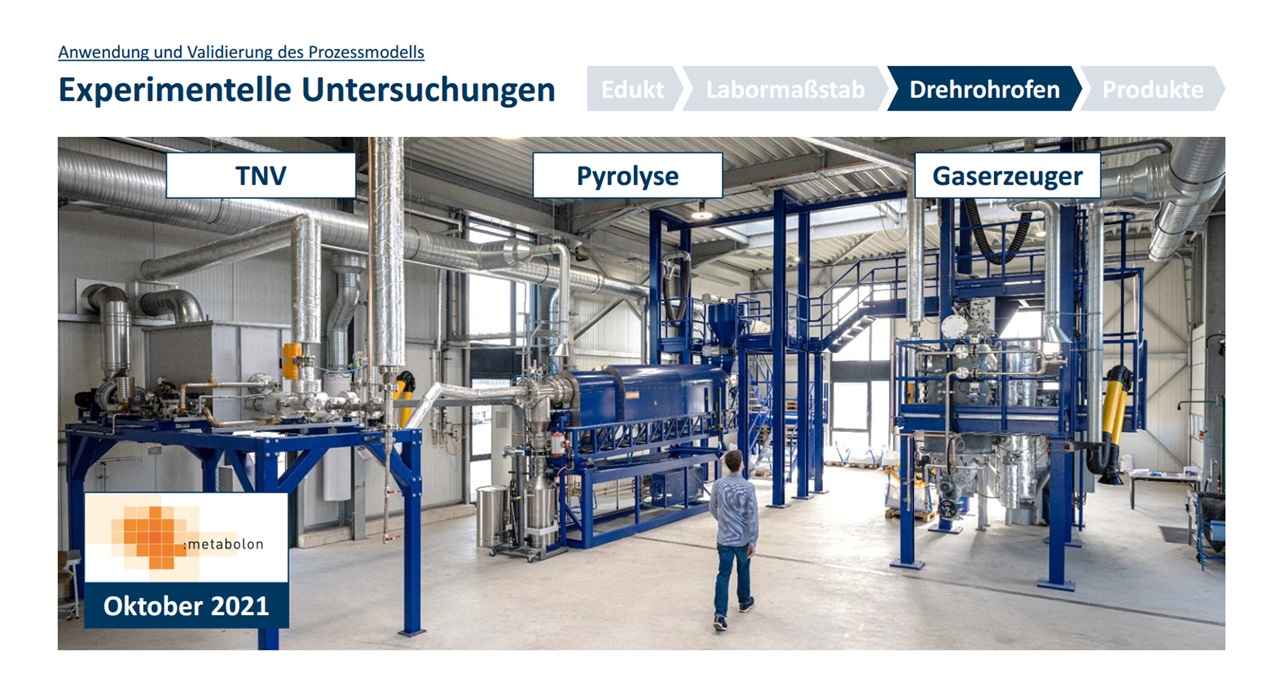
Image credit: Dr.-Ing. Sebastian Bogdahn
Using validated primary data, Bogdahn conducted a comprehensive environmental assessment and developed a methodological matrix covering relevant standards and guidelines to address inconsistent approaches. In the rotary kiln baseline scenario, one metric tonne of recovered carbon black results in a global warming potential over 100 years of about 918 kilogrammes of carbon dioxide equivalents, compared with the International Carbon Black Association’s global industry average of 3,910 kilogrammes for conventional fossil-based carbon black, a reduction of approximately 77 percent. Even after a quality adjustment for lower carbon content, the reduction remains about 70 percent. The study followed ISO 14067 and underwent independent external critical review under ISO 14071, also covering TPO and sustainable carbon black.
Further improvements remain possible. Emissions mainly stem from electricity consumption and gas combustion, with rCB processing accounting for about 44 percent, pyrolysis gas cleaning and combustion about 36 percent and tyre shredding about 19 percent. Sensitivity analysis confirms that renewable electricity offers substantial additional greenhouse gas reductions, reinforcing that a circular economy achieves genuine sustainability only when powered by renewable energy. Enhancing material quality through demineralisation and activation could enable higher substitution rates for fossil-based carbon black.
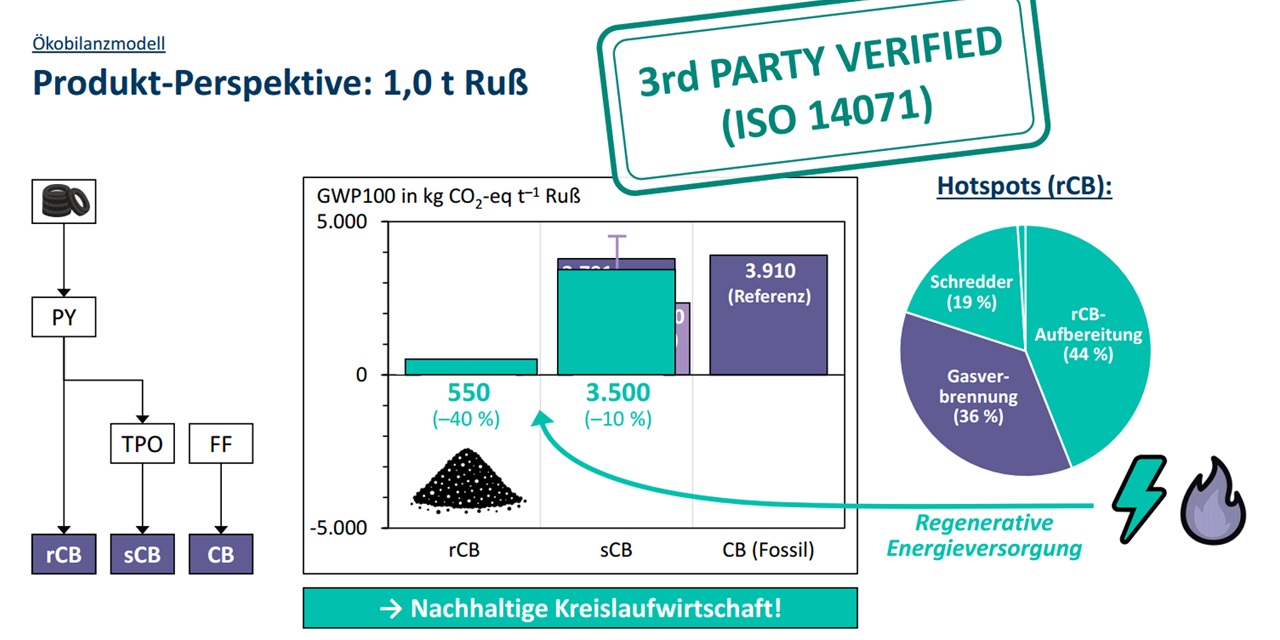
Image credit: Dr.-Ing. Sebastian Bogdahn
A central conclusion extends beyond pyrolysis itself. Raw materials, tyre manufacturing, the use phase and recovery pathways form an interconnected system spanning the entire tyre life cycle, closely linked to the carbon black, chemical, steel and energy sectors. Achieving circularity requires collaboration across systems and industries, along with greater methodological harmonisation and stronger integration of industrial value chains. The AZuR network’s work reflects this need, recognising that extended tyre use, repair, regrooving, retreading, mechanical recycling and appropriate chemical recycling must all function as interconnected elements of the value chain.
Tyres Europe Backs CARUSO Findings As EU Data Act Marks One Year
- By TT News
- October 15, 2026
Tyres Europe, as part of a coalition of 10 European associations representing consumers and automotive and mobility service providers, has issued a joint press release welcoming the latest CARUSO Connected Vehicle Field Test assessing the EU Data Act’s implementation across 29 major vehicle manufacturer groups. The findings confirm the legislation established important principles for accessing vehicle-generated data and encouraged some manufacturers to engage for the first time. One year on, however, the framework remains insufficient alone to enable a competitive, innovative connected mobility market.
Covering 15 automotive use cases across 28 vehicle manufacturer groups, the study concludes that while data access has improved, conditions for competitive, scalable, multi-brand services are still lacking. Access remains fragmented, inconsistent and often commercially or technically impractical across the car parc. Limited third-party access, differences in data scope, quality and coverage, and restrictive commercial terms continue to undermine the business case for innovative services. Genuine multi-brand development remains unattainable, preventing consumers and businesses from fully benefiting from connected mobility.
For many manufacturers, implementation has become a compliance exercise rather than a genuine effort to enable market access. Independent providers face limited datasets, restrictive terms, manual approvals, manufacturer-specific consent mechanisms and inconsistent technical solutions. Such approaches may satisfy the Data Act’s broadly defined obligations but are incompatible with the real-time, automated access modern digital services require.
Strong enforcement matters. Manufacturers respond faster where national authorities investigate complaints and apply enforcement mechanisms. Without consistent, harmonised, proactive enforcement across the European Union, Data Act rights risk remaining largely theoretical for a significant share of Europe’s vehicle fleet.
The coalition urges European Union institutions and Member States to enforce the Data Act consistently, issue clear guidance on fair, reasonable and cost-based compensation and use forthcoming reviews to reinforce rather than weaken it. Dedicated automotive legislation should establish common access conditions, interoperability requirements, initial technical and data delivery standards and safeguards against discrimination. Effective access must cover vehicle-generated data and the in-vehicle functions and resources needed to develop, scale and deliver digital mobility services, enabling fair competition, growth and investment.
According to the coalition, the Data Act was an important first step, but horizontal legislation alone cannot create a workable multi-brand market. Implementation varies widely: of 28 manufacturers, nine (32 percent) have barely implemented the Act; 18 (64 percent) lack adequate third-party pricing; 18 (64 percent) lack adequate data provision; and 19 (68 percent) lack an adequate API solution. Sixteen manufacturers (57 percent) enable none of the use cases, while only nine support the most feasible ones. Without stronger enforcement and dedicated automotive legislation, Europe will fall short of its innovation, consumer choice and fair competition ambitions.
CEAT Q2 FY27 Revenue Rises 26% to INR 47.62 Bln
- By TT News
- October 14, 2026
CEAT reported a 26 percent year-on-year increase in consolidated revenue to INR 47.62 billion in the second quarter of the 2026-27 financial year, while net profit stood at INR 1.12 billion as higher raw material costs continued to weigh on the tyre maker.
The company’s consolidated earnings before interest, tax, depreciation and amortisation (EBITDA) margin was 9.5 percent, according to its unaudited results for the quarter ended 30 September.
Arnab Banerjee, Managing Director and Chief Executive, said revenue growth was supported by premium segments across business units. He added that the conflict in West Asia had kept raw material costs high, prompting the company to tighten cost controls.
CEAT expects to deliver double-digit revenue growth in the second half of the financial year, alongside further price increases, Banerjee said.
On a standalone basis, revenue rose 23 percent year on year to INR 45.48 billion. EBITDA margin was 10.14 percent, while net profit reached INR 1.64 billion.
Kumar Subbiah, Chief Financial Officer, said commodity costs were expected to remain elevated in the third quarter. The company would continue to pursue measured price increases and improve its product mix to manage cost pressures.
Subbiah said debt increased during the quarter, largely because of capital expenditure of close to INR 4.9 billion to expand capacity in areas with high utilisation, as well as dividend payments.
He added that CEAT would maintain financial discipline while investing to meet demand and support profitable growth.
Michelin Expands Delhi Presence With Dwarka And Karol Bagh Outlets
- By TT News
- October 14, 2026
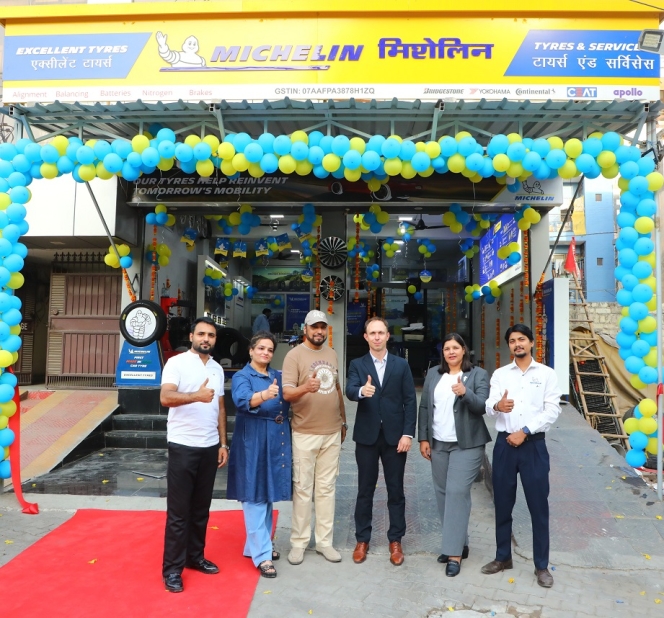
Michelin has strengthened its retail presence in India by launching two Michelin Tyres & Services outlets in Delhi, located in Dwarka and Karol Bagh. The openings make Michelin's premium tyre range, including the Made-in-India Primacy 5, accessible to customers in west and central Delhi, alongside professional fitment and tyre care. The Dwarka facility was inaugurated by Benjamin Coesnon, Marketing Director India.
The Dwarka outlet, operated with Excellent Tyres, covers 1,500 sft and caters to one of Delhi's largest planned residential sub-cities and its expanding south-west corridor. Excellent Tyres, established in 1994, brings over 30 years of experience in the capital's tyre trade. Meanwhile, the Karol Bagh store, run with Rana Tyres, spans 1,000 sft in a prominent automotive trade hub. Founded in 1977 and now led by its third generation, Rana Tyres contributes nearly five decades of technical knowledge and a loyal clientele.
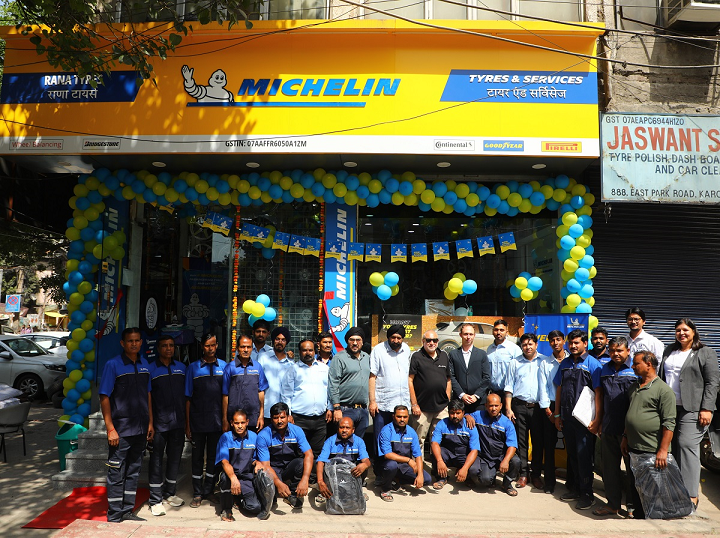
The expansion reflects Michelin's sustained commitment to India. Its distribution network now exceeds 800 points of sale, while over INR 28 billion has been invested in the Chennai manufacturing plant. A further INR 6.86 billion went into a passenger car tyre line that now produces the Primacy 5 for Indian buyers. The new stores aim to deliver safer, more durable and higher-performing mobility.
Shantanu Deshpande, Managing Director, Michelin India, said, " Delhi is one of the largest premium car markets in the country. Expanding our presence in Delhi will provide accessibility to today's customers and serve the next wave of premium car owners. With the Made-in-India Primacy 5 now available at these stores, customers in the capital can get Michelin's globally benchmarked safety and longevity, backed by expert service from trusted partners. India remains a key growth market for Michelin, and Delhi is central to how we continue to build our presence."
Comments (0)
ADD COMMENT