Uncertainties impact world rubber supply, demand
- By TT News
- December 28, 2020
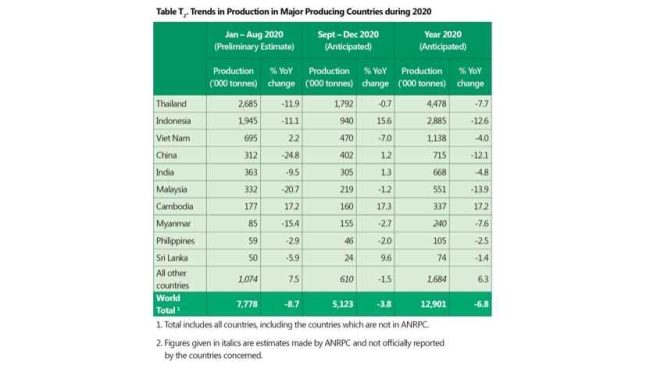
The downward revision in the world supply outlook for 2020 is largely due to the scaling down of the outlook for Thailand and India, according to ANRPC. The outlook on the production of NR in Thailand has been scaled down by 332,000 tonnes to 4.478 million tonnes. The country’s revised outlook for 2020 represents a 7.7% decline from the previous year as against a 0.9% anticipated fall reported a month ago.

The harvesting and primary processing of rubber in Thailand are severely affected by acute shortage of labourers. The migrant labourers from neighbouring countries and those from other provinces within the country find it difficult to reach back and resume the various farm management activities including tapping and primary processing. Aggravating the situation, tropical storm ‘Noul’ damaged rubber plantations in several provinces of Thailand in the last week of September besides causing heavy rains, flash floods, and water run-offs.
In August, northern Thailand was hit by the tropical storm ‘Sinlaku’ causing flash floods in 18 northern provinces of the country. The loss in output arising from previous year’s incidence of a new fungal leaf disease is already factored in. Abnormal leaf fall resulting from fungal diseases usually impacts on the yield performance of the affected for two succeeding years.
In India, the production anticipated in 2020 has been scaled down by 42,000 tonnes to 668,000 tonnes, ANRPC study said. The revised outlook represents a 4.8% decline from the previous year as against a 1.1% anticipated increase reported a month ago. The country’s NR production sector is impacted by a burst in the number daily new cases of Covid-19 infections in the State of Kerala since the beginning of September and the abnormal leaf fall caused by the outbreak of Phytophthora leaf disease during July and August. It is reported that the incidence of abnormal leaf fall during this year is less severe compared to the previous year.

 Demand fall
There has also been a fall in world consumption of NR by 11.7% y/y to 8.151 million tonnes during the first eight months of 2020 (Jan-Aug), as per preliminary estimates. Based on the revised estimates and forecasts, the world consumption outlook for the full year 2020 is marginally scaled up by 67,000 tonnes to 12.611 million tonnes by representing an 8.4% fall from the previous year. The outlook for 2020 as reported a month ago was 12.544 million tonnes by representing an 8.9% fall from the previous year.
China has marginally revised up its consumption outlook for 2020 in view of an observed earlier-than expected economic recovery and acceleration in growth. A survey conducted by Nikkei revealed that the growth has been more pronounced in the manufacturing sector. The Manufacturing Purchasing Managers’ Index (PMI) improved to 51.5 in September from 51.0 recorded in August and 51.3 anticipated for September, according to a survey conducted by the country’s National Bureau of Statistics and the China Federation of Logistics and Purchasing. The country’s automobile sector has made a major turnaround. The domestic retail sales of passenger vehicles, including minivans, SUVs and multipurpose vehicles, increased 7.4% y/y in September 2020, the third straight monthly gain. The domestic sales of passenger vehicles had increased 6.0% y/y in August 2020.

As per the revised outlook, China is anticipated to consume 5.055 million tonnes of NR during 2020, down 8.9% from the previous year. The country’s consumption outlook for 2020, as reported a month ago was 5.043 million tonnes, down 9.1% from the previous year.
India has scaled-up its consumption outlook for 2020 to 923,000 tonnes from 900,000 tonnes reported earlier in the year. Auto sales in India have made a U-turn. The domestic sales of passenger car increased 31.3% y/y in September 2020, the highest growth over the past 27 months. The trend reversal in passenger car is driven by preference for personal mobility during the pandemic, gradual opening up of markets, easing of supply-chains, labour availability, and excitement of new vehicle launches. The domestic sales of two-wheeler grew 12% y/y in September 2020, the highest growth over the past 21 months. Sales of tractor increased 16% y/y during the month, the highest growth over many years in the past. The domestic sales of LVC (Light Commercial Vehicles) and M&HCV (Medium and Heavy Commercial Vehicles) declined by 3.0% each during the month, after double digit declines till August 2020.
Looking ahead, according to ANRPC, the world demand for NR will remain constrained by the uncertainties clouding the global economic recovery, acceleration in the number of new coronavirus cases, reintroduction of control measures and partial lockdowns across countries and a likely long delay in the mass availability of the vaccine. On the positive side, there are increased hopes of further fiscal aid in the US to keep its economy on track. The White House has reportedly raised its stimulus offer from the earlier proposed $1.0 trillion to $1.5 trillion, and further to $1.8 trillion, though that is still short of $2.2 trillion proposed by the Democrats.

- AZuR Chemical Recycling Project Group
- AZuR Network
- End-Of-Life Tyres
- Tyre Pyrolysis
- Recovered Carbon Black
- Tyre Pyrolysis Oil
- Pyrolysis Gas
New Research Quantifies Environmental Benefits Of End-Of-Life Tyre Pyrolysis
- By TT News
- October 15, 2026
New research findings from a doctoral dissertation by Dr.-Ing. Sebastian Bogdahn examine how end-of-life tyres can yield high-quality recovered carbon black (rCB) through pyrolysis while delivering substantial environmental benefits. The work, titled ‘Production and Environmental Assessment of High-Quality Carbonaceous Materials from End-of-Life Tyre Pyrolysis’, was presented in condensed form at an AZuR Chemical Recycling Project Group meeting in Dillingen/Saar on 1 October 2026.
The dissertation tackles how end-of-life tyres can be recovered and recycled to maximise their value. Pyrolysis is identified as a complementary technology that helps close recycling gaps in the circular economy and offers an alternative to fossil-based carbon black, a material that plays a crucial role in determining tyre properties.
In the pyrolysis process, rubber granules from processed tyres undergo thermal decomposition without oxygen, producing three main streams: solid rCB, tyre pyrolysis oil and pyrolysis gas. Previous evaluations of such technologies often separated technical and environmental perspectives, relied on secondary data and lacked standardised methodologies, making findings difficult to compare.
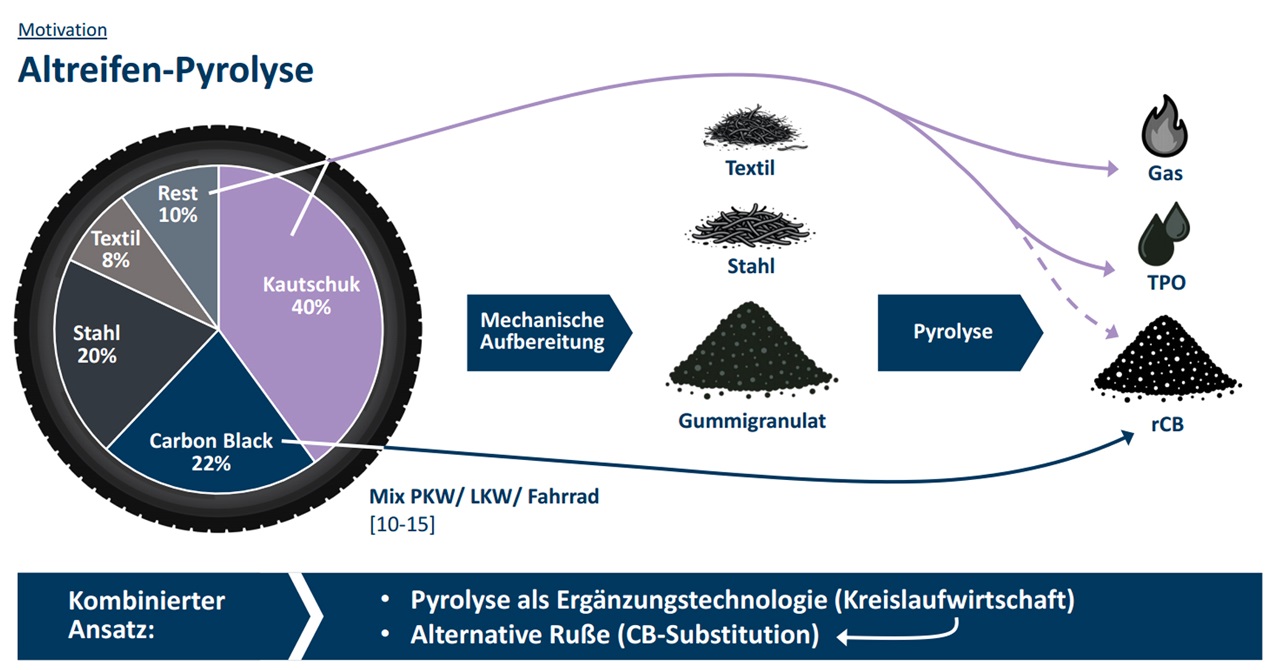
Image credit: Dr.-Ing. Sebastian Bogdahn
Bogdahn overcomes these limitations by integrating a technology-specific process model with a detailed life cycle assessment model. This combination enables a scientifically robust environmental evaluation of pyrolysis and its secondary raw materials using reliable primary data. A central component is a process model that mathematically describes material conversion by combining reaction kinetics, reactor behaviour and mass and energy balances.
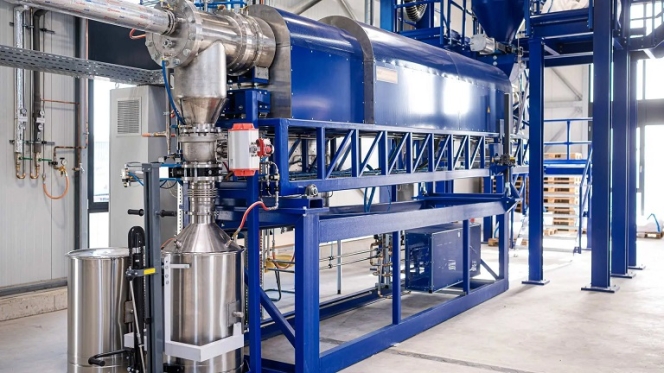
Starting with laboratory-scale experiments, the model was scaled up and validated using a pilot-scale rotary kiln at the Institute of TH Köln. Comprehensive laboratory analyses of feedstocks and products supported development and validation. Optimal conditions for the investigated system were found at 650 degrees Celsius with a residence time of about one hour, achieving complete material conversion and high-quality recovered carbon black. Product distribution was roughly 40 percent rCB, 37 percent TPO and 23 percent pyrolysis gas by weight.
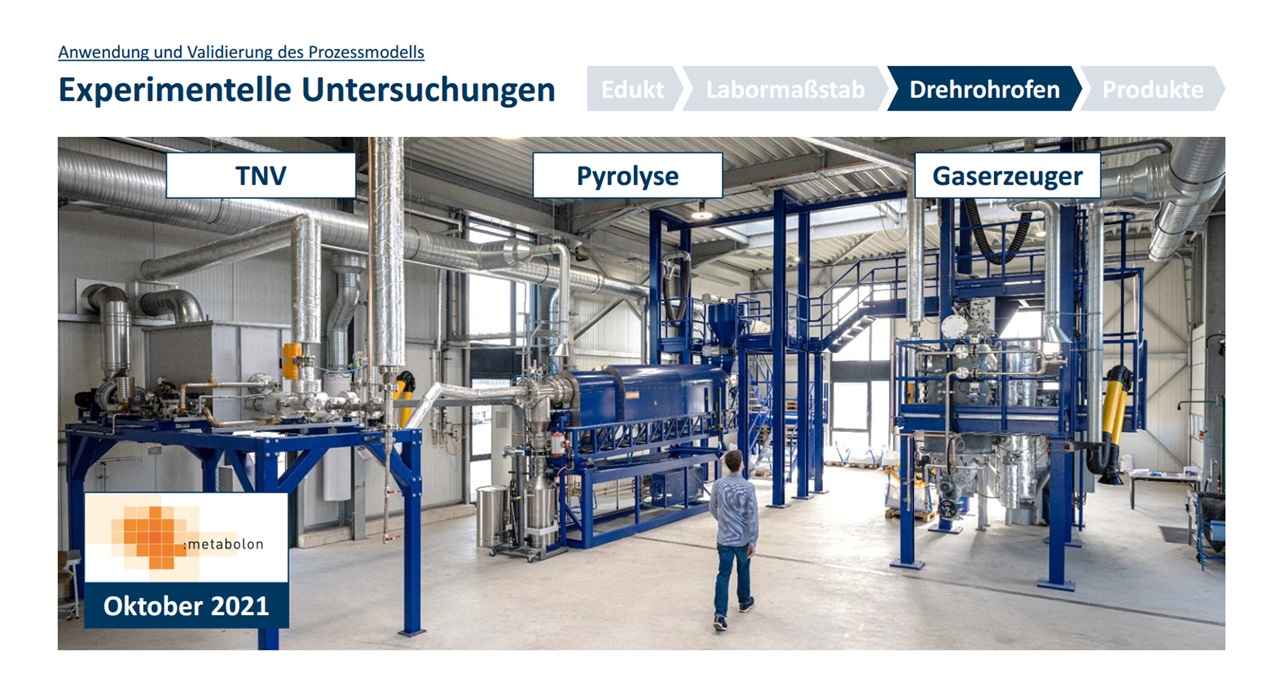
Image credit: Dr.-Ing. Sebastian Bogdahn
Using validated primary data, Bogdahn conducted a comprehensive environmental assessment and developed a methodological matrix covering relevant standards and guidelines to address inconsistent approaches. In the rotary kiln baseline scenario, one metric tonne of recovered carbon black results in a global warming potential over 100 years of about 918 kilogrammes of carbon dioxide equivalents, compared with the International Carbon Black Association’s global industry average of 3,910 kilogrammes for conventional fossil-based carbon black, a reduction of approximately 77 percent. Even after a quality adjustment for lower carbon content, the reduction remains about 70 percent. The study followed ISO 14067 and underwent independent external critical review under ISO 14071, also covering TPO and sustainable carbon black.
Further improvements remain possible. Emissions mainly stem from electricity consumption and gas combustion, with rCB processing accounting for about 44 percent, pyrolysis gas cleaning and combustion about 36 percent and tyre shredding about 19 percent. Sensitivity analysis confirms that renewable electricity offers substantial additional greenhouse gas reductions, reinforcing that a circular economy achieves genuine sustainability only when powered by renewable energy. Enhancing material quality through demineralisation and activation could enable higher substitution rates for fossil-based carbon black.
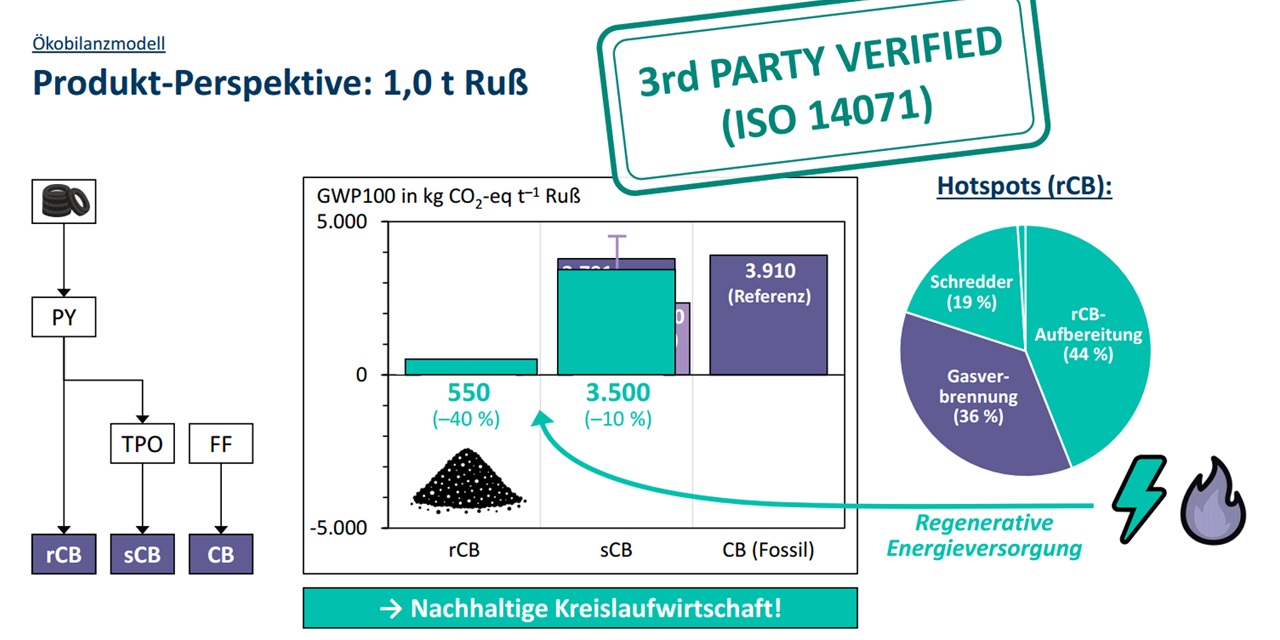
Image credit: Dr.-Ing. Sebastian Bogdahn
A central conclusion extends beyond pyrolysis itself. Raw materials, tyre manufacturing, the use phase and recovery pathways form an interconnected system spanning the entire tyre life cycle, closely linked to the carbon black, chemical, steel and energy sectors. Achieving circularity requires collaboration across systems and industries, along with greater methodological harmonisation and stronger integration of industrial value chains. The AZuR network’s work reflects this need, recognising that extended tyre use, repair, regrooving, retreading, mechanical recycling and appropriate chemical recycling must all function as interconnected elements of the value chain.
Tyres Europe Backs CARUSO Findings As EU Data Act Marks One Year
- By TT News
- October 15, 2026
Tyres Europe, as part of a coalition of 10 European associations representing consumers and automotive and mobility service providers, has issued a joint press release welcoming the latest CARUSO Connected Vehicle Field Test assessing the EU Data Act’s implementation across 29 major vehicle manufacturer groups. The findings confirm the legislation established important principles for accessing vehicle-generated data and encouraged some manufacturers to engage for the first time. One year on, however, the framework remains insufficient alone to enable a competitive, innovative connected mobility market.
Covering 15 automotive use cases across 28 vehicle manufacturer groups, the study concludes that while data access has improved, conditions for competitive, scalable, multi-brand services are still lacking. Access remains fragmented, inconsistent and often commercially or technically impractical across the car parc. Limited third-party access, differences in data scope, quality and coverage, and restrictive commercial terms continue to undermine the business case for innovative services. Genuine multi-brand development remains unattainable, preventing consumers and businesses from fully benefiting from connected mobility.
For many manufacturers, implementation has become a compliance exercise rather than a genuine effort to enable market access. Independent providers face limited datasets, restrictive terms, manual approvals, manufacturer-specific consent mechanisms and inconsistent technical solutions. Such approaches may satisfy the Data Act’s broadly defined obligations but are incompatible with the real-time, automated access modern digital services require.
Strong enforcement matters. Manufacturers respond faster where national authorities investigate complaints and apply enforcement mechanisms. Without consistent, harmonised, proactive enforcement across the European Union, Data Act rights risk remaining largely theoretical for a significant share of Europe’s vehicle fleet.
The coalition urges European Union institutions and Member States to enforce the Data Act consistently, issue clear guidance on fair, reasonable and cost-based compensation and use forthcoming reviews to reinforce rather than weaken it. Dedicated automotive legislation should establish common access conditions, interoperability requirements, initial technical and data delivery standards and safeguards against discrimination. Effective access must cover vehicle-generated data and the in-vehicle functions and resources needed to develop, scale and deliver digital mobility services, enabling fair competition, growth and investment.
According to the coalition, the Data Act was an important first step, but horizontal legislation alone cannot create a workable multi-brand market. Implementation varies widely: of 28 manufacturers, nine (32 percent) have barely implemented the Act; 18 (64 percent) lack adequate third-party pricing; 18 (64 percent) lack adequate data provision; and 19 (68 percent) lack an adequate API solution. Sixteen manufacturers (57 percent) enable none of the use cases, while only nine support the most feasible ones. Without stronger enforcement and dedicated automotive legislation, Europe will fall short of its innovation, consumer choice and fair competition ambitions.
CEAT Q2 FY27 Revenue Rises 26% to INR 47.62 Bln
- By TT News
- October 14, 2026
CEAT reported a 26 percent year-on-year increase in consolidated revenue to INR 47.62 billion in the second quarter of the 2026-27 financial year, while net profit stood at INR 1.12 billion as higher raw material costs continued to weigh on the tyre maker.
The company’s consolidated earnings before interest, tax, depreciation and amortisation (EBITDA) margin was 9.5 percent, according to its unaudited results for the quarter ended 30 September.
Arnab Banerjee, Managing Director and Chief Executive, said revenue growth was supported by premium segments across business units. He added that the conflict in West Asia had kept raw material costs high, prompting the company to tighten cost controls.
CEAT expects to deliver double-digit revenue growth in the second half of the financial year, alongside further price increases, Banerjee said.
On a standalone basis, revenue rose 23 percent year on year to INR 45.48 billion. EBITDA margin was 10.14 percent, while net profit reached INR 1.64 billion.
Kumar Subbiah, Chief Financial Officer, said commodity costs were expected to remain elevated in the third quarter. The company would continue to pursue measured price increases and improve its product mix to manage cost pressures.
Subbiah said debt increased during the quarter, largely because of capital expenditure of close to INR 4.9 billion to expand capacity in areas with high utilisation, as well as dividend payments.
He added that CEAT would maintain financial discipline while investing to meet demand and support profitable growth.
Michelin Expands Delhi Presence With Dwarka And Karol Bagh Outlets
- By TT News
- October 14, 2026
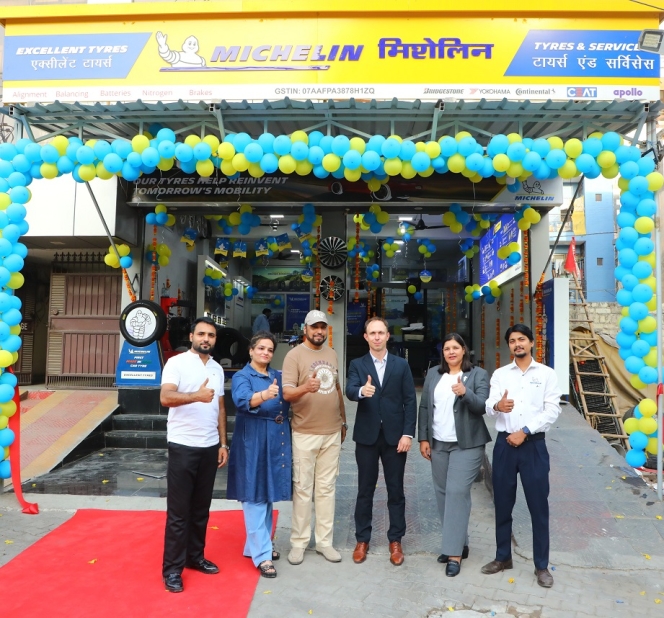
Michelin has strengthened its retail presence in India by launching two Michelin Tyres & Services outlets in Delhi, located in Dwarka and Karol Bagh. The openings make Michelin's premium tyre range, including the Made-in-India Primacy 5, accessible to customers in west and central Delhi, alongside professional fitment and tyre care. The Dwarka facility was inaugurated by Benjamin Coesnon, Marketing Director India.
The Dwarka outlet, operated with Excellent Tyres, covers 1,500 sft and caters to one of Delhi's largest planned residential sub-cities and its expanding south-west corridor. Excellent Tyres, established in 1994, brings over 30 years of experience in the capital's tyre trade. Meanwhile, the Karol Bagh store, run with Rana Tyres, spans 1,000 sft in a prominent automotive trade hub. Founded in 1977 and now led by its third generation, Rana Tyres contributes nearly five decades of technical knowledge and a loyal clientele.
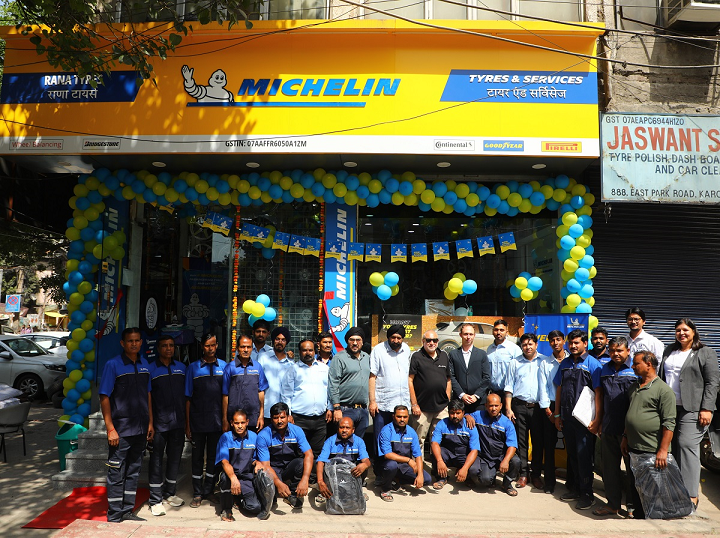
The expansion reflects Michelin's sustained commitment to India. Its distribution network now exceeds 800 points of sale, while over INR 28 billion has been invested in the Chennai manufacturing plant. A further INR 6.86 billion went into a passenger car tyre line that now produces the Primacy 5 for Indian buyers. The new stores aim to deliver safer, more durable and higher-performing mobility.
Shantanu Deshpande, Managing Director, Michelin India, said, " Delhi is one of the largest premium car markets in the country. Expanding our presence in Delhi will provide accessibility to today's customers and serve the next wave of premium car owners. With the Made-in-India Primacy 5 now available at these stores, customers in the capital can get Michelin's globally benchmarked safety and longevity, backed by expert service from trusted partners. India remains a key growth market for Michelin, and Delhi is central to how we continue to build our presence."
Comments (0)
ADD COMMENT