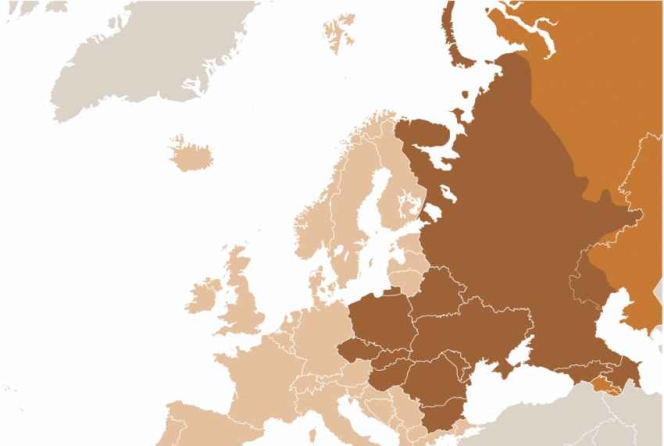

In 2014, Zivojin Sekulic was presenting a concept about Serbia as a future hot spot for tyre production in Shandong, in China, one of the world’s biggest tyre production province. By then, nobody was bullish on Serbia and saw the country as the next tyre production hub, but Sekulic applied analysis and research methods to support his prediction.
Sekulic has been with the industry for over a decade, and has been responsible for developing, managing and supporting operations in Europe, Asia, and the USA.
Several reasons could support Sekulic's claims. One of the reasons for that prediction was geopolitical relations between China, USA, EU and Euroasia. To de-risk trade tension, many tyre companies are exploring alternative production locations, and Serbia is emerging to be a viable place to target major markets. Also, Also, 'made in EU' effects are needed for OEM contracts which also help to brand building.
Having those reasons in mind, Sekulic forecast that Chinese tyre companies will come to the Eastern and South-Eastern Europe to setup tyre plants to avoid anti-dumping duties, apply made in EU effect to their brand and to get some OEM contracts as they need to be close enough to automotive plants due to specific logistic delivery contracts.
Five years later, Linglong Tire in 2019 started to build a tyre plant in Serbia with an investment of almost one billion USD. "Serbia is China's first strategic partner in central and eastern Europe and has a favourable environment for development and investment," said the Chinese tyre company. After the completion of the project, the annual output of various high-performance radial tyre will reach 13.62 million units, with yearly revenue of $ 600 million.
In the same year just a few months later, another Asian Tyre producer, Toyo Tire announced that it will setup a plant in Serbia. The Japanese company will invest around 3.91 million euros in the plant, which will produce tyres for passenger vehicles with an annual capacity of five million tyres. Toyo Tire will start construction of the Serbian Plant in May 2020, and manufacturing operations are expected start in January January 2022, with a capacity of five million tyres annually (based on tyres for passenger vehicles) by the summer of 2023.

Cooper Tire Serbia, a subsidiary of Cooper Tire & Rubber is also increasing production capacity at its Kruševac tyre manufacturing plant. With a strategic manufacturing footprint investment of approximately $55 million in equipment upgrades and facility expansion, the project will increase the size of the Kruševac facility to more than 882,000 square feet.
Cooper Tire Serbia will produce new, larger diameter tyres being demanded in Europe and other global markets. Total annual production capacity at the Kruševac plant will increase by approximately one-third after this expansion, which is expected later this year and will establish a footprint which could further double capacity with additional equipment and people.
"We can say that 2019 was an amazing year for the tyre Industry of Serbia. With already four tyre manufacturing plants of Michelin, Copper Tire, Mitas and Trayal, the country will have two more manufacturing plants soon. That is a huge success for Serbia as we all know that even countries with a bigger population and bigger size have lesser number of tyre plants in Europe," says Zivojin Sekulic.

A chat with Zivojin Sekulic:
Why are tyre companies showing increasing interest in Serbia for setting up plants – and generally in eastern Europe?
The reason for setting up tyre plants in Serbia is because of its specific geopolitical status. Serbia is in Europe, but not in the EU. That means particular goods produced in Serbia can be exported with 0% duty to EU, Russia, USA and countries of CEFTA and EFTA agreements and that's the market of almost one billion people. Comparing to anti-dumping duties for tyres produced in China, sounds like a good benefit, right?
Also, another reason is the label of “Made in EU” for tyre brands. The “Made in EU” effects help tyre companies to become recognisable and increase the prices, comparing to prices of tyres produced in China, and that means more significant profit.
Take the example of Hankook and their plant in Hungary. Only a few years after setting up their plant in Hungary they were selling more than 30% of their total annual production in EU and today with OEM contracts, excellent marketing strategy and outstanding R&D teams, they are in the race to become premium brand. So, imagine one day, maybe in five to eight years from today, Linglong can be close to the premium tyre brand and with the right strategy and marketing activities, if they decide to go that way.
One more reason is OEM contracts. Before setting up the plant in Serbia, Linglong signed a deal with VW and Renault, and now tyres produced in the Chinese company's tyre plant in Serbia will be delivered to these two automotive giants.
What benefits/ incentives that Serbia offers?
There are several benefits that country like Serbia is ready to offer to foreign investors. But I would like to highlight the benefits in general, not to go deeper in an analysis of specific incentives as that depends from situation to situation.
For example, the government is offering land where investors can set up a plant free of charge. There are also some tax incentives for more significant investments which are happening in the tyre industry. For instance, Cooper Tire's expansion project is supported by around $8 million in incentives provided by the Serbian government. Some investors can even get incentives per each employee that they will hire (basically like cashback card ). So, a general conclusion is that country like Serbia is really generous to foreign investors, and they should have that in mind.
Which companies are in the process of setting up?
At this moment Linglong is building the tyre plant in the city of Zrenjanin and Toyo announced that they will start building a plant in the city of Indjija very soon.
On the other side, there are major tyre companies - Mitas, Michelin, Cooper Tire, Trayal, which are producing tyres the country.
What's the future of tyre industry in Serbia?
Even I was right six years ago with a prediction that Asian tyre producers will setup tyre plants in Serbia in the near future that doesn't mean I will be right this time. But I genuinely believe that in Serbia there is a place for one more tyre plant. Specifically, I am thinking about a TBR , Agri and OTR tyre plant that can be built in a place where now Trayal's old plant is located which is still working and producing tyres for agriculture.
Going forward, the future of the Serbian tyre industry will move in another direction. After setting up plants, we will see R&D centres and Testing grounds and facilities in the country. I am predicting this because, for R&D, you need to have an excellent workforce and Serbia really has top-notch engineers and amazing developers. Currently, Continental has an R&D centre in the city of Novi Sad where several hundreds of engineers are employed.
In my working experience of 14 years in the tyre industry and 10 years in the IT sector, and having experience from Silicon Valley, I can tell you that engineers, researchers and software developers in Serbia are outstanding and not expensive like in the western EU or Silicon Valley. So, I am pretty sure that future intelligent tyres that will be based on sensors and specific software and machine learning will be designed and produced in some of the R&D centres based in Serbia.
Regarding testing facilities. Well, why should someone go to Spain or to Nordics to test summer or winter tyres if they can do it in Serbia as our climate is changed, so we have very hot summer and extreme winter, the perfect climate for tyre testing.
Q) Please share some information on your Project SMARTY?

My project SMARTY is related to the tyre industry and related to the development of smart tyres and smart trucks.
Using my vast experience from the tyre industry and IT industry, with a team of developers, I am working on the development of specific sensors, hardware and software that will be used in vehicles to optimise the costs and to prevent the accidents with tyres. We want to predict failure before it happens.
Currently, we have some working models and, shortly, we will start with sales of those models. The final goal is to make SMARTY device to become necessary in every vehicle to become smart or autonomous. Sensors for truck and OTR tyres we will unveil soon.
(Zivojin Sekulic: z.sekulic@gaj.rs)
Policy Changes A Priority
- By Gaurav Nandi
- October 27, 2026
Portugal’s retreading industry is caught between its established technical capabilities and a market increasingly shaped by low-cost new tyres, regulatory shifts and price-driven purchasing. Associaçao de Recauchutagem de Pneus (ARP) President David Laureano speaks to Tyre Trends about the necessary changes, current state of the industry and how to rebuild confidence and create conditions for investment.
Are policy changes necessary to create a level playing field for retreaders?
I consider policy changes a priority for boosting Portugal’s retreading sector and plan work on four fronts. The first is to review the environmental and economic treatment of retreading so that charges and incentives acknowledge the extension of tyre service life.
The second is to strengthen enforcement of compliance obligations for all operators placing tyres on the market. The third is to introduce criteria regarding lifecycle costs, performance and circularity in public procurement, enabling the participation of technically suitable retreaded solutions.
The last is to facilitate company access to instruments for industrial modernisation, energy efficiency, training and innovation. These measures should be developed in collaboration with public entities and other sector stakeholders. Policy quality improves when those who manufacture, use and manage tyres participate in their formulation.
 What are the ARP’s priorities under your leadership?
My priority is to strengthen a unified voice for the sector while respecting the diversity of the companies that comprise it. Building trust among users by demonstrating the quality of domestic retreaders. I want to contribute to an association that stays close to its members and is capable of gathering reliable data, fostering knowledge sharing and presenting well-founded proposals to public authorities.
I also view it as essential to bring the fleet industry, educational institutions and technology partners closer together. We can collaborate on training, research and the dissemination of best practices, thereby strengthening the sector’s collective capacity. The change I would like to see in the market is a more informed purchasing decision, one that recognises tyre performance and the value of extending its service life.
What role can retreading play in reducing raw material consumption and waste?
Retreading preserves a significant portion of the tyre structure by utilising a technically sound casing and enables a new cycle of use. This reduces the need for materials required to manufacture an entirely new structure and postpones the casing’s end-of-life.
Realising this potential requires effective management across the entire value chain including initial selection, maintenance, timely tyre removal and casing inspection. Benefits must be measured rigorously. Savings depend on the tyre type, process and usage conditions; therefore, we must communicate substantiated results rather than applying a single percentage figure to every situation.
What hinders greater acceptance by fleets and consumers?
Doubts regarding quality and safety persist, alongside insufficient information about the industrial process. The perception of poor quality was already among the obstacles identified in the sector characterisation study conducted by Valorpneu in 2019. Trust is built through transparency that requires explaining casing selection, production controls, traceability and the tyre’s suitability for its intended use.
There are specific United Nations regulations for retreading, namely Regulations No. 108 and No. 109. Under these regulations, all operators are required to conduct tests on the tyres they produce, and the tests are identical to those performed on new tyres. The sector also needs to make results more visible through fleet monitoring and comparable usage data.
We cannot focus solely on sales as after-sales service is crucial for building trust and ensuring continuity with the end customer, whether they are transport companies or private individuals.
How can retreading be better integrated into circular economy and sustainability policies?
Retreading should be considered right from the initial tyre selection. This entails prioritising casings designed for extended use, ensuring proper maintenance and establishing systems to evaluate their utilisation. Valorpneu specifically identifies extending service life, the potential for reconstruction and the segregation of tyres with retreading potential as preventive measures.
We would like to see this logic translated into specific objectives and indicators such as how many casings are utilised, how many usage cycles are achieved and how much resources are preserved. These results would help guide incentives and purchasing decisions.
What is the current state of the tyre retreading industry in Portugal?
Portugal possesses a retreading industry with experience, technical expertise and close ties to its customers. Its presence is particularly significant in the heavy-vehicle tyre market. However, it is a sector that needs to strengthen its position.
Commercial pressure challenges companies to demonstrate the product’s value over its lifespan, particularly in a market where the purchase price is a decisive factor. Our ambition is to unite the sector to transform existing industrial capacity into a stronger market presence driven by quality, information and constructive institutional representation.
What is the impact of low-cost imported tyres on retreaders?
Pressure from low-cost tyres is a key concern, one that has also been highlighted in ARP’s public communications. When the decision focuses solely on the initial price, it becomes harder to highlight the value of durability, technical support and the potential to reuse the casing for further service cycles.
Geographic origin alone does not determine a tyre’s quality. We advocate for competition based on verifiable criteria regarding safety, performance, compliance with environmental obligations and lifecycle costs. There is also the issue of continuity as retreading relies on the availability of suitable casings. Therefore, the choice of a new tyre should also take into account its retreadability potential.
Which segments show the highest demand?
Heavy vehicles form the sector’s core base. Road freight transport is therefore a central market, and we see opportunities to strengthen our presence among passenger transport and service fleets, tailored to the specific demands of each operation. There are also specialised applications.
Retreading data for 2024 covers commercial, agricultural, industrial and civil engineering tyres, among other categories. While these figures characterise the activity, they should not be confused with domestic market demand shares. Our goal is to work with each segment to identify where retreading offers a technically sound and economically advantageous solution.
How do regulatory uncertainty and capacity expansion affect investment?
An industrial facility invests with a multi-year horizon. Equipment, training and process improvements require confidence in future operating conditions. When rules or charges change, projects tend to be re-evaluated, complicating investment and expansion decisions.
A concrete example of a shift in the economic landscape is the Ecovalor (environmental fee). In 2025, the Valorpneu schedule indicated a zero Ecovalor for domestically retreaded tyres placed on the market. In 2026, it introduced a specific schedule with a 10 percent bonus, and for the heavy-duty category, the indicated rate is EUR 8.07 per tyre, plus VAT.
We believe that changes of this nature must be accompanied by dialogue with the sector, an assessment of their impact and predictability. Companies need to understand how their environmental contribution will be valued before committing to new investments.
How important is the total cost of ownership regarding demand?
It is fundamental. For a fleet, the purchase price is just one part of the equation. The assessment must include mileage, fuel consumption, maintenance, downtime and casing utilisation. Comparisons must be made under similar conditions regarding load, route, axle position and usage.
Retreading must demonstrate its value in this context through concrete results. I would like to see more long-term relationships between fleets and retreaders with records that allow for tracking cost-per-kilometre and improving decision-making over time. This benefits both parties.
Should retreading be recognised as a strategic industrial and environmental activity?
Yes. That is the vision I want to help affirm. It is an activity that brings together industrial production, technical expertise, transport services and resource preservation. This recognition must be reflected in industrial policies, investment instruments and purchasing decisions.
It must also be accompanied by the sector’s own commitment to quality, innovation and demonstrating its results. ARP aims to contribute to this effort alongside companies, fleets and public entities. We share a common interest in maintaining an industry capable of generating value in Portugal and making better use of the resources on which we all depend.
What is the outlook for the next three to five years?
I see growth potential, but that growth will depend on the conditions we are able to create. Increased fleet focus on operating costs, the need for efficient resource utilisation and industrial modernisation could create opportunities. To capitalise on them, we need suitable casings, customer trust and economic stability.
I would not venture a specific growth rate without a sufficiently solid statistical basis. Ambition must translate into concrete objectives by winning over users, increasing casing utilisation and strengthening corporate competitiveness.
- Satish Goyal
- Jairaj Zarekar
- Anand Kumar
- H. M. Meena
- Sanjeev Sharma
- Arup Kumar Misra
- Tushar Suhalka
- Varun Manjunath
- Jayant Vaidya
India’s Tyre Recycling Industry Examines Standards, Technology And Circularity At RE-GO 2026
- By TT News
- October 26, 2026
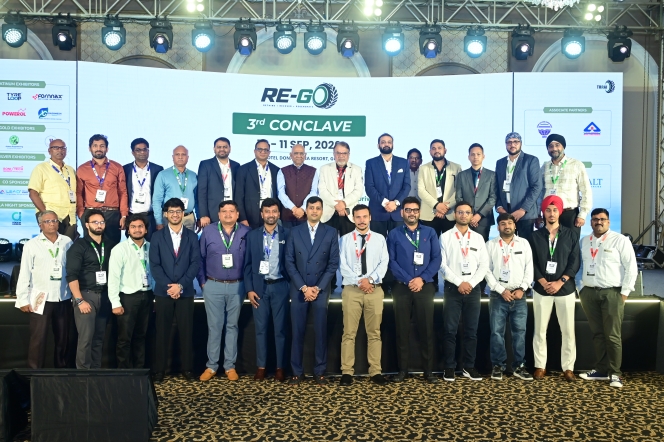
India’s tyre recycling industry discussed regulation, technology and material recovery at RE-GO 2026, a three-day conclave held in South Goa from 10 to 12 September. Organised by the Tyre & Rubber Recyclers Association of India (TRRAI), the event brought together more than 250 delegates, representatives from more than 200 companies and participants from more than 20 states.
The third annual conclave, hosted at Novotel Goa Dona Sylvia, included more than 20 speakers and experts, three panel discussions and more than 20 exhibitors and sponsors. The conference programme ran on 10 and 11 September , followed by a departure programme on September 12.
Regulation and technology dominate discussions
Held under the theme of policy, compliance and circularity, the conclave brought together recyclers, technology providers, tyre industry representatives, policymakers, regulators, standards professionals, consultants and business leaders.
Discussions covered regulation and standards, extended producer responsibility (EPR), traceability, automation, environmental performance, digitalisation, artificial intelligence, material recovery and circularity.
The technical programme examined automated pyrolysis, co-processing, national standards for tyre pyrolysis oil (TPO) and recovered carbon black (rCB), fleet management, EPR policy and compliance, and the Common EPR Portal. Other topics included life-cycle assessment (LCA), greenhouse gas emissions accounting, digital transformation and technical innovation.
Industry and regulatory representatives attend opening session
The inaugural session featured Satish Goyal, President of TRRAI, and Jairaj Zarekar, its Secretary. Other participants included Anand Kumar, Former Director and Scientist ‘F’ at the Central Pollution Control Board; H. M. Meena, Scientist ‘D’ and Joint Director at the Bureau of Indian Standards; and Sanjeev Sharma, Senior Vice-President And Business Head For Mobility Solutions And Fleet Management at JK Tyre & Industries.
Arup Kumar Misra, Chairman of the Assam Pollution Control Board, was the chief guest and delivered the keynote address, “Tyre Recycling: From Liability to Asset”. The address focused on turning end-of-life tyres into recoverable resources and sources of economic value.
Three panels examine the sector’s priorities
The conclave featured three high-level panel discussions on sustainable recycling policy, recycling technology and the development of a circular tyre economy.
The first examined policy, standards, EPR, compliance and sustainable development. The second focused on shredding, granulation, automation and continuous pyrolysis. The third considered how collection, technology, markets and manufacturing could be connected to support a circular tyre economy.
The panels were moderated by Tushar Suhalka, Varun Manjunath and Jayant Vaidya, respectively.
The event also included an exhibition featuring more than 20 exhibitors and sponsors, networking sessions and an awards and recognition ceremony.
TRRAI highlights collaboration and standards
TRRAI said it had more than 500 members, representing approximately 75 percent of the tyre recycling market. The association works on standardisation, professionalisation, technical advancement, regulatory dialogue and collaboration across the sector.
The conclave highlighted the role of co-operation among industry participants, government bodies, regulators, standards organisations, technology providers and technical experts. Its discussions reflected a focus on stronger standards, improved traceability, environmental accountability, digitalisation and circularity.
Renaud Lapointe Named President Of Metso's Aggregates Division
- By TT News
- October 24, 2026
Metso has named Renaud Lapointe as President of its Aggregates business area and a member of the Metso Leadership Team, with the appointment taking effect on 15 November 2026. He takes over from Markku Simula, whose departure from the company was announced on 11 August 2026.
Lapointe has been with Metso since 2005 and has served as President of the Europe and Central Asia market area since December 2024. Before that, he led the Metso Products business line within the Aggregates business area from 2018 to 2024, and between 2014 and 2017 he was Vice President of the Crusher Systems business line in the same segment. Earlier in his tenure, from 2005 to 2014, he held several leadership positions at Metso in France. Lapointe holds a degree in mechanical engineering from ISTIL in Lyon, France.
Lapointe said, "I am excited to return to the Aggregates business and lead such a highly respected global organisation. With its strong customer relationships, industry-leading solutions and talented team, the business is well positioned for continued success and growth.”
Sami Takaluoma, President and CEO, Metso, said, “Renaud brings experience from both our Aggregates business and our market area organisation. This combination will support the continued development of our offering and close cooperation with customers. I look forward to welcoming him to the Metso Leadership Team.”
JK Tyre Eyes Double-Digit Growth Despite Cost Pressures Testing Margins
- By Nilesh Wadhwa
- October 23, 2026
JK Tyre & Industries is targeting double-digit growth in FY2027, supported by healthy commercial vehicle demand, sustained OEM traction and a growing market for premium passenger car tyres. However, rising raw material costs and elevated freight rates continue to pressure margins, prompting the company to pursue further price increases and operational efficiencies.
Anshuman Singhania, Managing Director, JK Tyre & Industries, expects demand to remain stable through the second half of FY2027, with commercial vehicle tyre sales projected to record double-digit growth for the full year. While passenger vehicle demand could moderate slightly, healthy OEM order books and replacement market traction are expected to support the industry's growth momentum.
“We are very optimistic going ahead that demand would be quite stable,” Singhania said during the post-results media interaction, adding that the positive momentum was expected to continue through the third and fourth quarters.
Record Revenue in Q2 FY2027
JK Tyre reported its highest-ever consolidated quarterly revenue of INR 48.5 billion in Q2 FY2027, up 20 percent year-on-year (YoY). Consolidated EBITDA rose 28 percent sequentially to INR 3.43 billion, with an EBITDA margin of 7.1 percent. Profit after tax stood at INR 600 million.
Domestic sales grew 32 percent YoY, led by a 65 percent increase in OEM sales following the implementation of GST 2.0. Exports also gained momentum, rising 14 percent sequentially despite geopolitical uncertainties and challenging international market conditions.
Growth was broad-based across product segments. OEM volumes increased 76 percent in truck and bus radial (TBR) tyres and 35 percent in passenger car radial (PCR) tyres. The tubeless tyre portfolio grew 25 percent YoY, against estimated industry growth of 10 percent, while tipper tyre sales increased 20 percent compared with industry growth of 11–12 percent.
Sales in the two- and three-wheeler category rose approximately 85 percent YoY, driven primarily by scooters. Replacement sales increased 20 percent, reflecting continued traction across channels.
Despite the revenue growth, profitability remains under pressure as input and logistics costs rise faster than they can be recovered through pricing.
Raw Material Costs and Freight Weigh on Margins
JK Tyre's raw material basket increased approximately 9 percent sequentially in Q2, with the cumulative increase over the preceding six months estimated at around 30 percent. Singhania expects a further 4–5 percent increase in the basket during Q3.
Elevated container freight rates have added to the pressure, with increases across geographies affecting exports and shipments from India. Higher petrol and diesel prices have also contributed to rising logistics costs.
The company is seeking to offset these pressures through price increases, manufacturing efficiencies and a richer product mix. However, the timing of margin recovery will depend on the extent to which higher costs can be passed on in a price-sensitive market.
Further Price Hikes Planned
JK Tyre increased prices by approximately 4–5 percent in Q1 and a further 7 percent sequentially in Q2, taking the cumulative increase during the first half of FY2027 to around 11–12 percent. The company intends to implement another 4–5 percent increase in Q3, subject to market conditions.
“The raw material increase is putting a lot of pressure on margins. But we are steadily increasing our prices to pass through,” Singhania said.
OEM pricing is partly linked to input cost indices, allowing some increases to be recovered through contractual adjustments. In the replacement market, price increases have been implemented more gradually over the past two quarters, with further adjustments expected.
Singhania acknowledged that the industry typically experiences a lag between cost escalation and full price recovery. While the company expects margins to improve through better OEM mix, price indexation and operational efficiencies, it has not quantified the anticipated improvement.
Premium Tyres Gain Share
JK Tyre is increasing its focus on premium passenger car tyres, particularly those with rim sizes of 16 inches and above. The company said the share of these tyres in its passenger car OEM mix increased to approximately 40 percent in H1 FY2027, compared with 35 percent in FY2026. These sizes account for around 27 percent of its overall mix, including the aftermarket.
The shift towards larger rim sizes is being supported by new vehicle launches and wider adoption across passenger vehicle categories. JK Tyre has secured 10 OEM approvals during the year, eight of which involve models in the 16-inch-and-above category. These include the Maruti Suzuki Brezza, Mahindra Thar, Renault Duster and Tecton, and MG Tomahawk, as cited during the media interaction.
“The market is growing, but our market is growing at a faster rate,” Singhania said, highlighting the opportunity presented by new OEM programmes and rising demand for larger rim sizes.
The company expects this segment to support product realisation and improve its sales mix, with additional capacity helping it meet evolving OEM requirements.
Expansion Continues as Exports Offer Headroom
JK Tyre is proceeding with its INR 11.3 billion capacity expansion programme, which Singhania confirmed would not be deferred. The previously announced INR 50 billion capital expenditure programme is also progressing through its initial phase.
The investments are intended to support domestic demand and create capacity for export opportunities. JK Tyre reported encouraging demand from Latin America and Africa, while some markets in Asia and Europe softened amid geopolitical uncertainty.
The company plans to continue serving established markets across Latin America, the Middle East, Southeast Asia and Africa, alongside a limited presence in Europe, while prioritising domestic OEM and replacement requirements.
For the second half of FY2027, JK Tyre expects commercial vehicle demand to remain supportive and is targeting double-digit growth in the segment for the full year. Strong OEM order books, replacement demand and the increasing contribution of premium tyres are expected to underpin growth. The key challenge will be translating higher volumes into sustainable profitability as the company navigates raw material inflation, freight costs and the lag in price recovery.
Comments (0)
ADD COMMENT