Is Natural Rubber under mortal threat? Is there a possibility that factors like climate change, diseases etc. will bring the plantation industry to its knees?
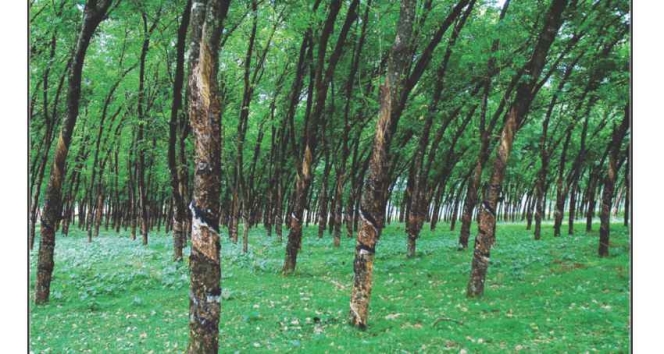
It is a fact that the traditional rubber growing regions in almost all rubber producing countries in Asia are increasingly constrained by adverse effects of Climate Change. The yield from Hevea in traditional regions is impacted by extreme weather, recurrent cyclones, depression rains and flash floods. The last couple of years have seen interruption to tapping due to unforeseen rains and floods. Another major constraining factor is the recurrent outbreak of new diseases. For example, the outbreak of a new fungal leaf disease (Pestalotiopsis leaf fall disease) reported in Indonesia in 2018 has now spread into around 387,000 ha of mature rubber trees in the country. An estimated 141,000 ha in Thailand, 16,000 ha in Malaysia and 4,000 ha in Sri Lanka are reportedly affected by new fungal leaf diseases.
The low rubber prices that continued over several years resulted in poor maintenance of rubber holdings in almost all producing countries. As resource-starved farmers could not apply fertilizers or adopt proper crop protection measures over several years, rubber trees became weak and lost their resistance to diseases and extreme weather. It is striking to note that the root cause of the decline in yield is the unattractive prices and the resultant poor maintenance of holdings. A major trend reversal of prices can bring glaring positive changes in the natural rubber production sector. The potential national average yield (i.e., the annual production from a unit hectare of tapped trees) is 20 to 30% higher than what is realized now. For example, the average yield in India is currently 1,400 kg per hectare. But a favorable price can increase the average yield to the range of 1,750-1,800 kg. The country had realized the average yield of 1,823 kg in 2012 when the prices ruled high. Moreover, a large extent of mature trees which are currently left untapped in the country will come back to production once farmers find the prices attractive. The country has around 200,000 hectares of mature trees which are left untapped.
More specifically, it is the uneconomic return from the venture that hinders the natural rubber production sector. There is no mortal threat to the supply base as far as prices stay remunerative and the net profit from the venture is attractive. No industry can sustain for a long if it is economically unviable and natural rubber is no exception.
Can a COVID19 like pandemic impact NR industry long term? Do plantations have an effective healthcare plan to ensure labourers’ health and safety?
NR sector globally has almost fully recovered from the impact of the Covide-19. This is particularly true with reference to the global production, consumption, trade, and prices of natural rubber. The prices in key physical markets had crossed over the pre-covid level even by October 2020 and firmed up further since February 2021.
It is true that the production and processing sectors in Thailand and Malaysia are partly hindered as cross-border travel restrictions prevent migrant workers from neighboring countries to return to works. This issue, to a large extent, is resolved by making use of local workers by providing them necessary skills training. Coming to the downstream manufacturing sector, large number of debt-burden units in the MSME sector are reportedly struggling hard to bring their businesses back to normal. On the other side, large-scale manufacturing units, particularly those in auto-tyre manufacturing, have made V-shaped recovery driven by the pent-up momentum generated on lifting of the lockdowns. For healthcare rubber products such as rubber gloves, the epidemic has been a major boon. Taking the global rubber industry as a whole, the industry has already come out from the impact of the pandemic.
Workers engaged in large plantations are provided with social security and healthcare facilities as per the regulatory provisions being followed by the governments in the respective countries.
What are the chances of NR getting totally replaced by alternative rubbers? Will this happen? If so, how soon?
NR getting totally replaced by any alternative material is an impossible event in any case. The relative share of NR in the total quantity of new rubber (i.e., natural rubber and synthetic rubber) globally consumed was less than 30% during early 1970s. From that low level, the relative share of NR has gone up to nearly 50% as of now (47.2% in 2020). Synthetic rubber and natural rubber are not competing each other because technical considerations limit the scope of substitution between the two.
Lack of sufficient economic benefits is considered to be a reason for planters looking for alternate crops that can bring faster financial returns. How real is this? How much of rubber plantations have been replaced by other crops?
A total extent of nearly 0.6 million hectares of rubber trees was estimated to have cut down during 2015-2020 period in Thailand, Viet Nam, China, Malaysia, and India for cultivation of other crops or for conversion of land for non-farm uses. The details are given below:
|
|
Extent of rubber area discarded during the period 2015-2020 (Hectares) |
|
Thailand |
440,000 |
|
Viet Nam |
72,000 |
|
China |
46,000 |
|
Malaysia |
24,000 |
|
India |
4,000 |
In the case of Thailand, farmers are offered attractive cash incentive (More than US$3500 per hectare) by the government for removing aged rubber trees and planting other crops. It means, the shift from rubber in Thailand is largely policy driven. The case of Thailand is an exception. Generally speaking, the crop shift from rubber over the past few years is caused by the unattractive net profit from the venture.
Is plantation industry too slow to modernise itself, technologically as well as in terms of attracting skilled labor?
It is a fact that technological progress is severely constrained in the smallholder-dominated rubber production sector. The unattractive prices that prevailed over the period since 2015 made the farmers deprived of resources. Although high-yielding clones are available, farmers are generally postponing the replating of aged low-yielding trees due to their inability to meet the huge replanting cost. Another factor that prevents smallholders from replanting is the uncertainty of the farmers over the long-term prospects of rubber cultivation. Unattractive prices have also discouraged farmers from adopting good agricultural practices. Poor return from the venture has compelled farmers to discontinue the application of fertilizers, pest and disease management measures, and proper maintenance of holdings. Larger section of farmers has discontinued the use of stimulants and rain-guarded tapping. However, technological progress continued in large plantations owned by corporates, enterprises, and the public sector.
NR supply has always been unstable due to various reasons. Is this prompting manufacturers to look for other options?
There is no serios supply constraint or supply uncertainty as of now except the seasonal shortage. Moreover, all the producing countries have huge potential to increase their supply if the prices become attractive. This point was elaborated earlier.
Is there a campaign being run by alternative rubber sector to put pressure on NR industry?
As stated earlier, NR does not face any threat from alternatives basically due to the reason that the only substitute for natural rubber is natural rubber. In the total global consumption of new rubber (i.e., natural rubber plus synthetic rubber), the relative share of NR is currently around 50% (47.2% in 2020) as against less than 30% in early 1970s. There is no reason to anticipate a fall in the relative share of NR in the next three decades at least.
Are environmental sustainability factors detrimental to NR cultivation?
Environmental considerations can only help NR to gain preference over synthetic rubber, polyurethane, and other materials in various applications because natural rubber is recognised as “an environment-friendly industrial raw material and renewable resource”. The following points establish such a view:
- Rubber plantations purify atmosphere by absorbing CO2 and releasing O2. Based on scientific research undertaken by rubber research institutes in five countries, it is empirically proven that a hectare of rubber plantation annually sequesters as much as 30 tonnes of CO2 from atmosphere which is near to that of the Amazonian base.
- Rubber plantations are a good source of timber and bulk of this goes into furniture industry thereby protecting large extent of forests from being logged every year. Secondary branches of the rubber trees go into the fiber board industry and small twigs are used by the rural people as a source of firewood, both indirectly saving forests.
- Rubber plantations contribute to sustainable soil productivity. Soil productivity has not deteriorated in any of the traditional rubber growing countries which have the history of growing rubber for more than 100 years and already completed 3-4 rubber plantation cycles.
- One of the key factors which had adversely affected food crops production in the last couple of years was climate change. Rubber plantations offer solution to this as it helps balancing carbon level in atmosphere. Rubber is no longer a mono crop. Several food crops are grown along with rubber plants in all NR producing countries. The concept of raising rubber plantations as agro-forestry is being increasingly promoted across countries. It is common among rubber farmers to maintain a portion of their land for other crops. Moreover, rubber holdings provide sources of ancillary income through activities such as horticulture, fishery, honeybee, goat farming, etc.
- In all major natural rubber growing countries, rubber has been identified as a major tool of poverty alleviation and thus helping to achieve the Millennium Development Goals (MDGs).
Are there any concerted efforts being taken up by organisations like ANRPC, IRSG or governments that subsidise NR cultivation?
Developmental activities such as promotion of new-planting and replanting in each country are undertaken by the respective governments only. Among the member governments of ANRPC, Thailand, Malaysia, India, and Sri Lanka provide financial incentives to farmers to promote the cultivation of rubber. The governments usually mobilize the funds needed for the purpose from the same sector by levying a cess on the quantity of NR exported from the country or consumed within the country. The financial assistance cannot be termed as a ‘subsidy’ because the funds needed for the purposes are mobilized from the same sector.
Is it possible to have a globally uniform price structure for NR that can ensure interrupted supply?
In a market driven global economy, commodity prices are largely determined by the forces of supply and demand. This is particularly true in the case of NR which is a strategic industrial raw material coming from more than 10 million smallholder farmers world over. It is not practical to regulate NR prices globally as it is a real challenge to bring together all major producing countries and consuming countries for such a common agenda on terms acceptable to all. (TT)
Birla Carbon Announces Asia-Wide Speciality Materials Price Hike Of Up To 15%
- By TT News
- September 22, 2026
Birla Carbon has confirmed a price increase of up to 15 percent for its Speciality Materials products across Asia, scheduled to take effect on 1 October 2026. The company pointed to significant and sustained rises in feedstock costs, driven partly by ongoing geopolitical instability and disruptions in global feedstock markets, as the reason behind the adjustment.
Although Birla Carbon pursued operational efficiencies, supply chain optimisation and disciplined cost management to soften the impact, the scale and persistence of the cost escalation left a price adjustment unavoidable. The company's sales teams will engage customers directly to explain the details and help them navigate the transition.
ACE Laboratories, Abdallah Consulting Launch VericarbSM To Standardise Recovered Carbon Black
- By TT News
- September 20, 2026
ACE Laboratories, an independent ISO/IEC 17025-accredited polymer testing laboratory, has partnered with Abdallah Consulting, LLC, a prominent tyre pyrolysis advisory firm, to introduce VericarbSM. This independent certification programme verifies that materials marketed as recovered carbon black (rCB) meet established criteria for rCB.
Recovered carbon black, derived from end-of-life tyres via pyrolysis, serves as a sustainable substitute for virgin carbon black in rubber and polymer applications. However, the emerging market has lacked the standardisation and independent verification that established supply chains provide. VericarbSM addresses this gap through independent material characterisation and rubber performance data, offering stakeholders a consistent basis for evaluating rCB products.
For producers, certification accelerates market entry and improves buyer approval rates. Consumers gain more capable suppliers and reduced evaluation time, while investors benefit from clearer volume sizing and fewer costly test failures. The programme is jointly administered by both organisations.
Erick Sharp, CEO, ACE Laboratories, said, “The rCB market has enormous potential, but growth has been held back by uncertainty about material quality and consistency. VericarbSM gives producers a way to prove their product and gives buyers the independent data they need to say yes.”
Dave Abdallah, Founder, Abdallah Consulting, said, “One key reason for the delayed growth of recovered carbon black is lack of product performance information in the customer’s language. ASTM standards are critical; in fact, most testing done in the process follows ASTM methods. But customers relate to a product better when its performance is shown in applications relevant to them. VericarbSM solves the language issue by showing verified rCB in terms of rubber performance while simultaneously adding credibility via third-party analysis and reporting.”
Zeon Establishes Kurashiki Subsidiary To Absorb Tohpe's Acrylic Rubber Business
- By TT News
- September 18, 2026
Zeon Corporation established Zeon Chemicals Kurashiki Co., Ltd. on 23 July 2026 to take over the acrylic rubber operations of fellow group firm Tohpe Corporation. The new entity, headquartered in Kurashiki City, Okayama Prefecture, is wholly owned by Zeon with paid-in capital of JPY 10 million and is led by representative Koji Minami.
On 21 August, Tohpe and the new subsidiary signed an absorption-type company split agreement, prompting Zeon to begin the procedures required under the Companies Act. Operations at the new company, focused on manufacturing and selling acrylic rubber and related activities, are scheduled to commence on 30 October 2026.
Acrylic rubber, known for its heat resistance, is used in automotive components including oil seals and hoses. The Zeon Group already maintains four production sites across Japan, United States and Thailand, forming a global supply network for the material.
The restructuring follows Zeon’s 11 May 2026 announcement that it would transfer Tohpe shares to NATOCO Co., Ltd. of Miyoshi City, Aichi Prefecture, as part of Tohpe’s paints business divestiture. Tohpe’s acrylic rubber operations, which complement Zeon’s Elastomers Business, will now be positioned as a key specialty rubber manufacturing site, with closer operational coordination intended to strengthen Group competitiveness and corporate value.
Revyre Targets SBS Market With Tyre-Derived Polymer After Auckland Road Trial
- By Gaurav Nandi
- September 14, 2026
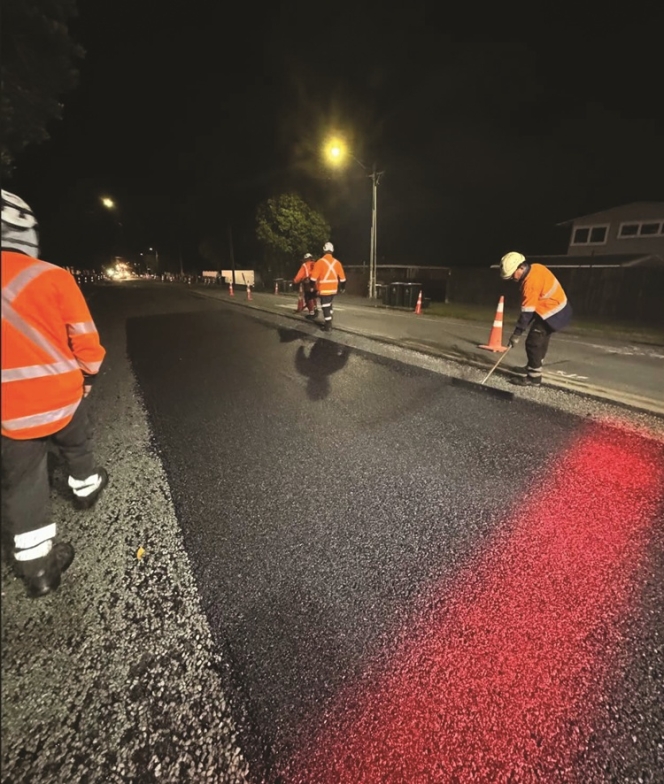
The company is betting that a polymer manufactured from end-of-life truck tyres can disrupt the market for petroleum-based styrene-butadiene-styrene (SBS), a widely used road-binding additive whose pricing and availability are tied to global oil markets. After completing a live road trial with Road Science and Auckland Transport in New Zealand, the company is preparing to use the results as a springboard for expansion into Australia and Sub-Saharan Africa, positioning the recycled material as a lower-cost, lower-carbon alternative to virgin polymers.
New Zealand-based Revyre Global Limited is positioning a polymer manufactured from end-of-life truck tyres as a lower-cost alternative to petroleum-based styrene-butadiene-styrene (SBS) after completing a live road trial with Road Science and Auckland Transport in New Zealand.
The company has spent several years developing the product as a direct replacement for SBS. Unlike conventional tyre-derived asphalt, which relies on crumb rubber, the company’s Chief Executive Officer Shaun Zukor told Tyre Trends that its proprietary thermomechanical process produces a remanufactured polymer with blending characteristics similar to SBS, allowing it to be used in existing asphalt infrastructure.
“Our primary objective was to develop a drop-in replacement for SBS, which is a petroleum-derived synthetic polymer,” Zukor said. “SBS is expensive, made from virgin materials and is widely used to improve road durability, fatigue resistance and overall pavement performance.”
The company began engaging Road Science, a division of Downer, and Auckland Transport after completing laboratory validation with engineering consultancy WSP in New Zealand.
Before approaching customers, it invested around 18 months in laboratory testing to validate the material’s performance.
Following successful laboratory trials, Road Science carried out its own evaluations before, together with Auckland Transport, deciding to trial the material on Blockhouse Bay Road, one of Auckland’s busiest roads.
The project then underwent another lengthy approval process involving Auckland Council and scientific advisers.
“It took another year to a year and a half to obtain all the necessary approvals from the council and its scientific advisors,” Zukor said. “They wanted to verify that all the claims in our technical literature were accurate.”
Construction of the trial road took place over three days in March and the company expects to receive the first performance data around September. Those results are expected to support commercialisation in overseas markets.
“Our business is focused only on New Zealand at the moment because we’re using it as a proof of concept,” Zukor said. “Once those results are available, we’ll publish them. That will place us in a much stronger position to take the product into Australia and Sub-Saharan Africa.”
The company estimates that entering Australia would take another 12 to 18 months after trial results are available and a planned New Zealand manufacturing facility becomes operational.
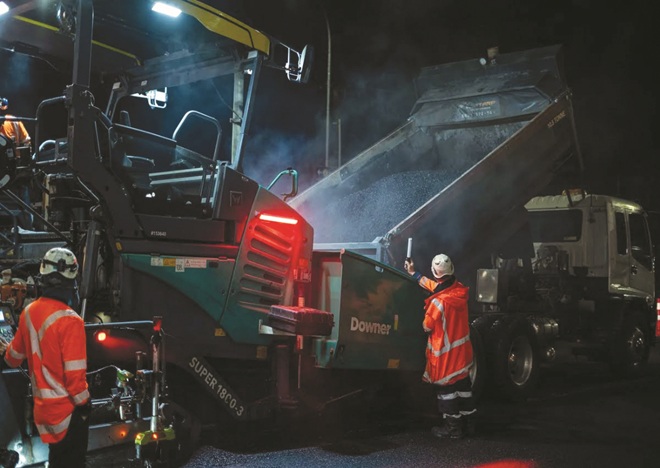
Although the current road project used only a small quantity of material because it is a demonstration, Zukor said the commercial opportunity could expand significantly.
“We used a relatively small amount of material for this particular project, but if the opportunity grows as expected, supplying the Auckland Transport network alone could eventually consume between 40–50 percent of our production capacity,” he noted.
MATERIAL ECONOMICS
The company currently manufactures the material primarily from truck and bus radial (TBR) tyres and earthmover tyres because of the higher natural rubber content.
While the SBS substitute represents the company’s immediate focus, it has divided its broader product portfolio into three categories. Revpol A, manufactured mainly from passenger and light truck tyres is intended for lower-performance rubber products such as rubber tiles, shoe soles and conveyor belts.
Revpol B targets asphalt applications and new tyre manufacturing, while Revpol C, produced largely from earthmover tyres, is designed for higher-performance applications.
The company is not currently manufacturing at its own facility but plans a new production unit in New Zealand. Until that facility is operational, product for trials is being supplied by its Canadian partner.
The technology relies primarily on a thermomechanical recycling process rather than chemical recycling. Whole tyres are broken down with steel separated from the rubber before the rubber is processed to a 30-mesh particle size and passed through Revyre’s proprietary thermomechanical process.
Zukor said only a very small amount of non-toxic, FDA-approved chemicals are used and that the process is driven primarily by operating parameters rather than chemical reactions.
He added that one of the key advantages of the technology is that it can be incorporated into existing SBS blending infrastructure with minimal changes as most development work focused on determining the optimum blending ratio rather than overcoming technical limitations.
“The primary technical challenges relate to the blending ratio,” he said, adding, “The higher the percentage of Revpol you add, the higher the temperatures and shear forces required in the bitumen blending terminals.”
Although the company has successfully blended as much as 20 percent Revpol into bitumen during development, Zukor said performance gains diminish beyond a certain point.
It has identified an optimum blend of between 5 percent and 10 percent depending on the application, ranging from conventional roads to heavy-duty pavements and airport runways.
“Any facility that currently blends SBS using its existing infrastructure can also blend our product using that same infrastructure,” he said.
CATALYST FOR SAVINGS
Zukor believes the material can reduce both costs and environmental impacts while improving pavement performance.
“We want to create a product that is environmentally sustainable, has an abundant raw material supply and is 20–40 percent cheaper than virgin materials while also having a significantly lower carbon footprint,” he stated.
Laboratory testing has produced encouraging results. According to Zukor, New Zealand’s wheel-tracking standard requires materials to withstand 800,000 load cycles, while Revyre’s product continued to perform until testing was halted at two million cycles.
“Our product achieved nearly two to three times the required wheel-tracking performance compared with standard bitumen,” he noted.
He also added that the objective is to produce road surfaces that are less expensive, more durable and environmentally sustainable while simultaneously addressing the challenge of managing end-of-life tyres.
“We believe this product ticks all of those boxes and have obtained a patent for it,” he said.
MANUFACTURING SCALABILITY
Although the company is currently relying on manufacturing capacity in Canada, Zukor said its modular production model could support significant expansion once commercial demand develops.
“We can currently produce up to 10,000 tonnes of this product, but because our production facilities are modular, capacity can easily be scaled anywhere from 1,000 tonnes to 50,000 tonnes, depending on market demand and the requirements of a particular region,” said Zukor.
Once the planned New Zealand facility becomes operational, Zukor expects its tyre feedstock to be supplied through Tirewise, the country’s extended producer responsibility (EPR) scheme for end-of-life tyres.
Under the programme, every imported tyre attracts a levy that funds incentives for registered collectors, processors and end users to move tyres through the approved recycling chain. Zukor said Revyre intends to register again as a processor after commissioning its new plant.
GOING PAST HURDLES
Zukor acknowledged that customer adoption remains the biggest hurdle. Road contractors also need to validate new formulations through laboratory testing before incorporating them into their pavement designs. Hence, Revyre is focusing on multinational contractors already operating in New Zealand to accelerate adoption, believing successful validation locally could support deployment elsewhere within those organisations.
He also believes global dependence on petroleum-derived SBS strengthens the case for tyre-derived alternatives.
“If you look at SBS, it’s already a product that’s in very high demand globally. Because it’s petroleum-based, its availability and pricing are heavily influenced by global macro-economic and geopolitical events,” Zukor said.
He said the company’s commercial proposition rests on three principles viz-a-viz consistent quality, supply and pricing.
According to Zukor, replacing virgin SBS with tyre-derived polymers could help localise supply chains, reduce exposure to petroleum price volatility and improve environmental outcomes while lowering costs for road owners.
Beyond New Zealand, Revyre is also evaluating opportunities in North America through its Canadian partner and is exploring future markets for tyre-derived materials.
Comments (0)
ADD COMMENT